


Can TORM (CPSE:TRMD A) Stay Undervalued On Raised Long Term Earnings Expectations?
TORM (CPSE:TRMD A) raised its longer term earnings expectations, sharpening focus on whether higher projected cash generation can support a stock that has delivered roughly a 9x return over the past five years.
At a share price of DKK264.4, TORM has kept positive momentum going, with a 1 month share price return of 16.5% and a 90 day gain of 34.9%. The year to date share price return of 111.2% and a 1 year total shareholder return of 121.8% indicate that recent optimism is building on already very strong longer term gains rather than reversing them.
Scan other tanker and energy shipping opportunities that show similar momentum and cash generation traits using our curated list of list of solid balance sheet and fundamentals (205 results)
TORM now appears to be a high quality operator with upgraded earnings ambitions, paired with a share price that has already re-rated significantly. The question for investors is whether the current valuation still leaves enough potential upside for new buyers.
Most Popular Narrative: 2% Undervalued
TORM closed at DKK264.4, only modestly below the most followed fair value estimate of DKK269.3. This implies limited valuation slack but still points to a small discount based on updated earnings power.
Disciplined capital allocation, including accretive vessel acquisitions, lease repurchases and a conservative balance sheet with long debt maturities, provides flexibility to capture potential future rate upside, which should support dividends and long term earnings potential.
See why 9 investors see TORM as 2% undervalued.
Result: Fair Value of DKK269.3 (UNDERVALUED)
Still, the narrative around TORM can change quickly if Red Sea disruptions ease and trade routes shorten, or if new product tankers increase effective fleet supply faster than demand.
Find out about the key risks to this TORM narrative.
Another View: Cash Flows Paint A Tougher Picture For TORM
The first narrative around TORM hinges on a modest undervaluation gap to a DKK269.3 fair value anchored in earnings and analyst assumptions. Our DCF model tells a different story. On that basis, the share price of DKK264.4 sits above an estimated future cash flow value of DKK205.81, which points to the stock looking overvalued on this stricter lens and raises the question of which signal you weight more heavily when cash generation is expected to decline.
For readers who want to see exactly how those cash flows are treated in the model, Look into how the SWS DCF model arrives at its fair value.
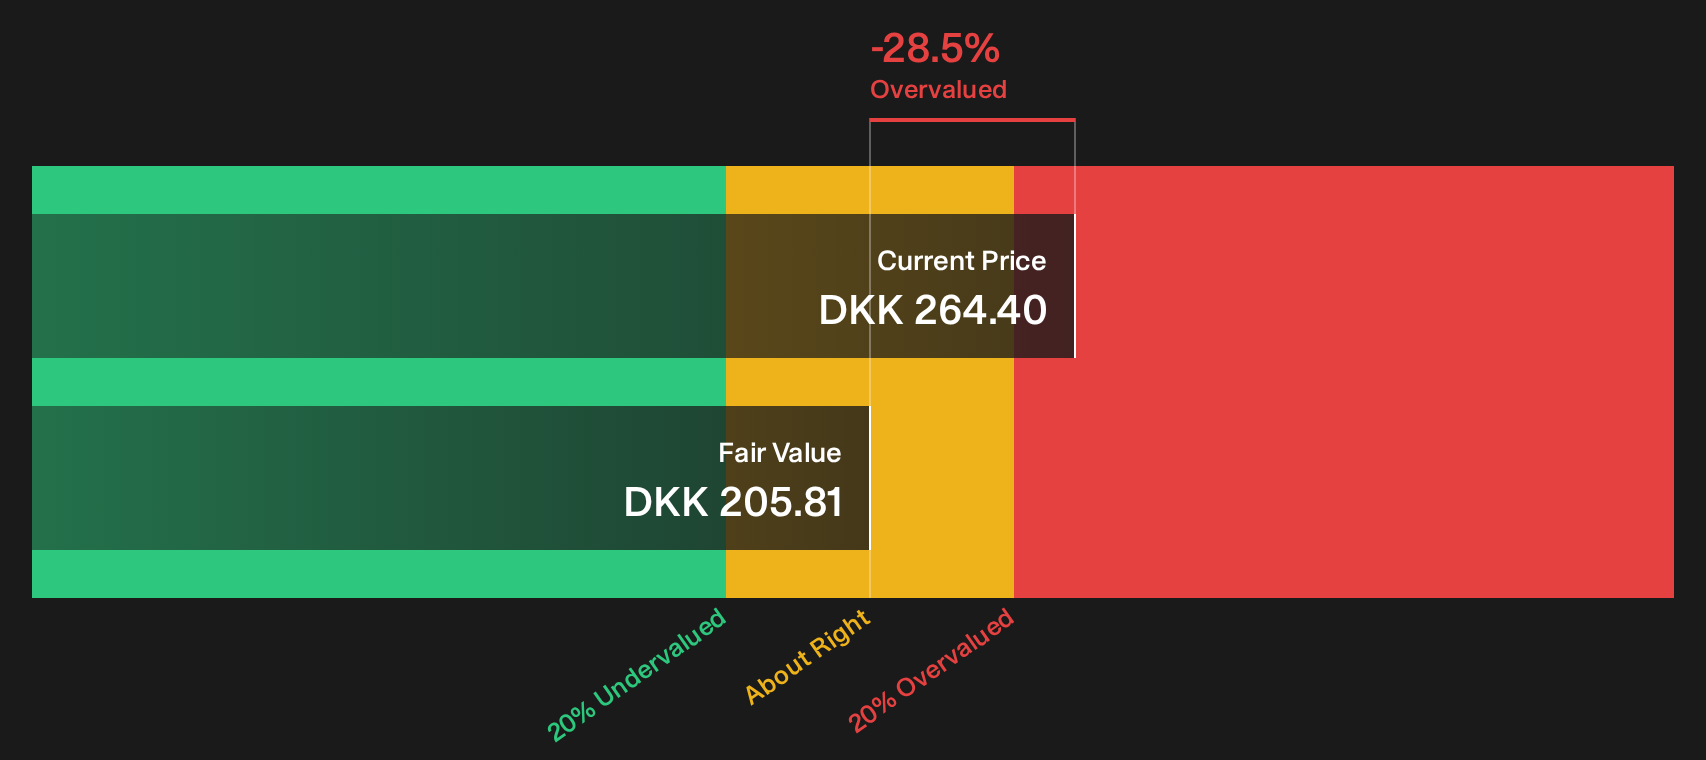
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TORM for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on TORM so far. If you want to move quickly and decide where you land, consider both sides of the story with 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond TORM?
If you like what you see in TORM but do not want to rely on a single stock, consider broadening your watchlist using data driven screeners.
- Spot potential turnaround opportunities early by reviewing our curated list of 122 elite penny stocks with strong financials.
- Zero in on quality at a reasonable price by scanning companies highlighted in the 194 high quality undervalued stocks.
- Prioritise resilience and focus on businesses featured in the 221 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com