


Why Wilmar International (SGX:F34) Could Be 41% Undervalued As Haze Inquiry Deepens
Wilmar International (SGX:F34) is back in focus after Singapore’s National Environment Agency asked the agribusiness and several peers for information on possible links to recent haze causing fires in Indonesia.
The investigation arrives after a softer patch for Wilmar International’s shares, with a 30-day share price return down 8.49% and a 90-day share price return down 14.14%. However, the year-to-date share price return is 9.51% and the 1-year total shareholder return is 16.23%, which suggests earlier positive momentum has cooled as investors reassess risk.
Spot potential alternatives as this haze inquiry unfolds by scanning the hand-picked 221 resilient stocks with low risk scores list, which aims to balance regulatory exposure with resilient financial profiles.After a solid 1-year total return of 16.23% and a recent slide linked to the haze inquiry, investors are left weighing Wilmar International’s valuation. Is most of the upside already taken, or is there still meaningful room ahead?
Price-to-Earnings of 11.4x: Is it justified for Wilmar International?
Wilmar International changes hands at a P/E of 11.4x, which sets the reference point for how the market is weighing its earnings against the current share price of SGD3.34.
The P/E ratio compares what investors pay today for each dollar of profit. For a large agribusiness with multiple segments and exposure to different regions, this yardstick helps you see whether the market is assigning a premium or discount to its current earnings power.
On one hand, the stock is described as good value when you line up its 11.4x P/E against the broader Asian Food industry at 14.5x. That points to a clear discount. On the other hand, when you compare it to a peer set on 9.8x, Wilmar International screens as more expensive. The fair P/E estimate of 12.7x sits above the current multiple, which signals that the valuation could feasibly shift higher if earnings quality and growth match that benchmark.
Explore the SWS fair ratio for Wilmar International.
Result: Price-to-Earnings of 11.4x (UNDERVALUED)
Still, the haze inquiry and any shift in Indonesian regulatory pressure could weigh on sentiment around Wilmar International and its long-running plantation activities.
Find out about the key risks to this Wilmar International narrative.
Another View: Wilmar International Through A Cash Flow Lens
The P/E points to Wilmar International trading at a discount, yet the SWS DCF model paints an even starker picture. With the share price at SGD3.34 and an estimated future cash flow value of SGD5.71, the stock screens as materially undervalued. Which signal carries more weight for you?
Look into how the SWS DCF model arrives at its fair value.
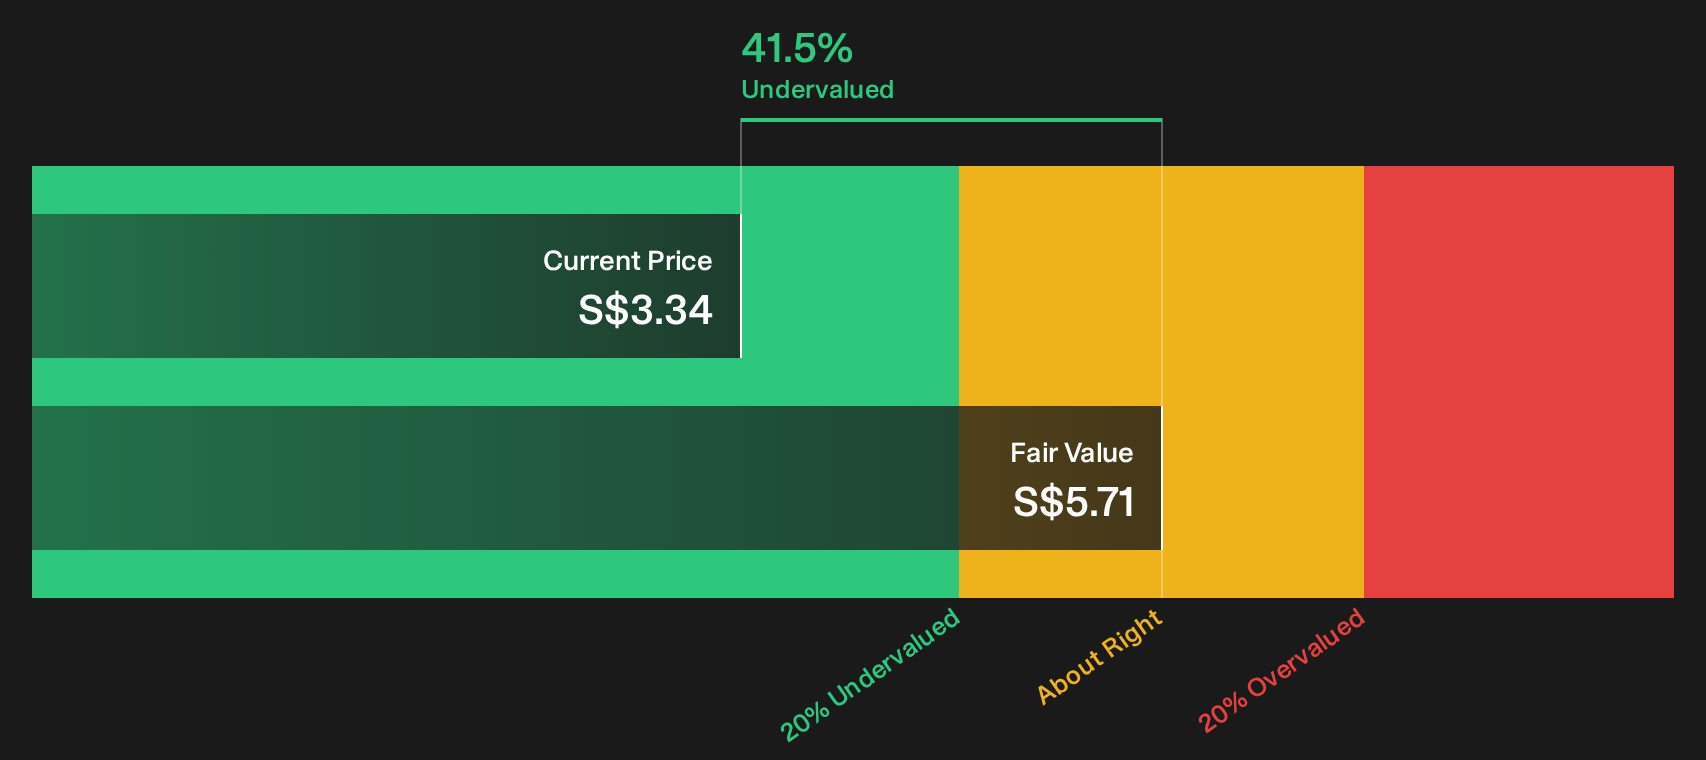
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Wilmar International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Wilmar International can easily pull sentiment in both directions, so move quickly and review the full picture for yourself, starting with its 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Wilmar International?
If Wilmar International has sharpened your focus on valuation and risk, do not stop here. Broaden your watchlist now or you might miss stronger opportunities emerging alongside it.
- Target steadier compounding potential by reviewing companies on the 226 dividend fortresses that combine income with disciplined payout profiles.
- Hunt for price dislocations by scanning the 613 high quality undiscovered gems where solid fundamentals have yet to attract wider attention.
- Prioritize resilience under pressure by filtering for businesses in the list of solid balance sheet and fundamentals (205 results) that pair healthier leverage levels with dependable balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com