


AEON REIT Investment (TSE:3292) Secures ¥24.3b Refinancing As Valuation Stays In Focus
AEON REIT Investment (TSE:3292) has secured a JPY 24.3b debt refinancing package and a series of interest rate swaps, reshaping how its upcoming loan and bond maturities are funded and hedged.
The refinancing news comes at a time when AEON REIT Investment’s security price has weakened, with the unit at ¥105,400 after a 1 day share price return of 1.54%, yet still down 6.89% over 30 days and 23.51% year to date. While the 1 year total shareholder return has declined 15.52%, the recent uptick in the share price indicates that investors may be reassessing the risk around upcoming maturities and the REIT’s longer term debt profile.
Spot opportunities beyond AEON REIT Investment by scanning a curated 22 resilient stocks with low risk scores that focuses on balance sheet resilience and more predictable cash flows.After a sharp year to date decline and with a fresh refinancing plan in place, AEON REIT Investment now sits at a different risk profile than it did months ago. Is that enough to justify investing today instead of waiting for a cheaper entry?
Preferred P/E of 17.3x: Is it justified for AEON REIT Investment?
Valuation for AEON REIT Investment currently leans on a P/E of 17.3x, which sits close to peers yet above the broader Asian retail REIT group.
The P/E ratio compares the unit price to earnings per share and gives you a shorthand way to see how much investors pay for each unit of profit. For a property trust such as AEON REIT Investment, that matters because income streams are a central part of the thesis.
Against direct peers, the P/E of 17.3x lines up almost exactly with the peer average of 17.5x, which suggests the market is pricing AEON REIT Investment in line with similar vehicles rather than giving it a clear premium or discount. Compared with the Asian retail REITs industry average of 12.4x and an estimated fair P/E of 19.6x, the current multiple looks higher than the broader group yet below the level the fair ratio points toward. This is a range the market could shift closer to if sentiment or fundamentals change.
Explore the SWS fair ratio for AEON REIT Investment.
Result: Price-to-earnings of 17.3x (ABOUT RIGHT)
Still, a P/E near peers leaves little cushion if AEON REIT Investment faces weaker rental demand or higher refinancing costs on its JPY 24.3b debt package.
Find out about the key risks to this AEON REIT Investment narrative.
Another View On AEON REIT Investment’s Value
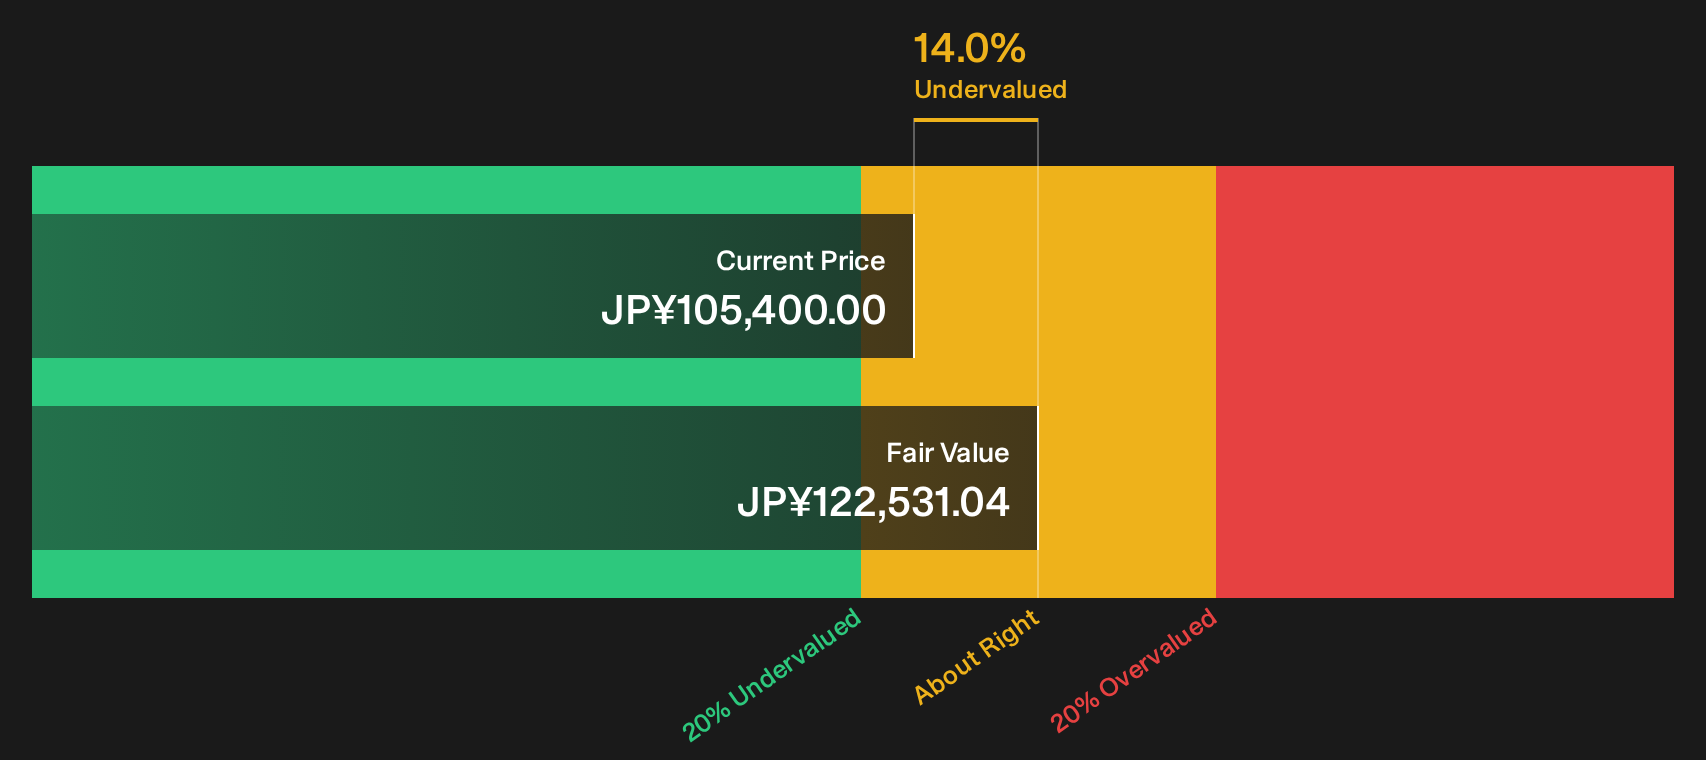
The preferred P/E points to a fairly full price for AEON REIT Investment, yet the SWS DCF model tells a different story. On that approach, the unit at ¥105,400 trades below an estimated future cash flow value of ¥122,531, which presents AEON REIT Investment as undervalued based on those long term projections. Which signal do you trust more when earnings growth is modest and debt refinancing is a key consideration?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AEON REIT Investment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The debate around AEON REIT Investment now feels finely balanced, with both risks and rewards in play. Act quickly and review the underlying metrics for yourself, then weigh those findings against the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond AEON REIT Investment?
If AEON REIT Investment no longer feels like the only option on your radar, broaden your opportunity set and pressure test your thesis with other targeted ideas.
- Spot potential value gaps early and compare them to AEON REIT Investment by running a focused search through 14 high quality undervalued stocks.
- Strengthen the income side of your portfolio by lining up candidates in the 29 dividend fortresses that can complement or contrast AEON REIT Investment.
- Aim to get ahead of the crowd by checking a tightly filtered 72 high quality undiscovered gems that most investors are not paying attention to yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com