


Seatrium (SGX:5E2) Lands Karpowership Deal On Questions Over Whether Valuation Has Caught Up
Seatrium (SGX:5E2) just secured a contract from Karpowership to convert and integrate five hydrogen-ready Whale Class Powerships, putting a fresh spotlight on how this new work might shape investor expectations.
For context, Seatrium’s share price closed at SGD1.81, with a 1-day share price return of 1.69% as the Karpowership contract hit the headlines. However, the 30-day and year-to-date share price returns are down 13.81% and 16.59% respectively, and the 1-year total shareholder return has declined 15.90%, pointing to pressure in the recent trend despite a positive 5-year total shareholder return of 16.94%.
Compare Seatrium's contract-driven story with other capital goods players winning new work by scanning our hand-picked 613 high quality undiscovered gems in similar industrial and energy-transition niches.
Seatrium now trades at SGD1.81 while consensus and intrinsic estimates sit materially higher. The real puzzle is where fair value lands inside that gap after this Karpowership contract pop.
Most Popular Narrative: 11% Overvalued
Fair value in the most followed Seatrium narrative sits at SGD1.63, below the last close of SGD1.81. This points to a market price above that framework while the recent Karpowership win adds fresh moving parts to the story.
Planned expansion into floating wind, FLNG and higher value conversion work, such as powerships and FSU or FSRU projects, requires incremental yard investment and complex engineering. Weaker than expected order conversion from the US$32b pipeline could leave underutilised capacity and dampen gross margin improvement.
See why 3 investors see Seatrium as 11% overvalued.
Result: Fair Value of SGD1.63 (OVERVALUED)
Still, if Seatrium converts more of its reported US$32b pipeline, or continues to lift gross margin from yard divestments and digitalisation, that bearish script can change quickly.
Find out about the key risks to this Seatrium narrative.
Another Valuation Lens On Seatrium
The bearish narrative pegs Seatrium’s fair value at SGD1.63, which frames the stock as 11% overvalued versus the recent SGD1.81 price. A different lens tells a very different story. Simply Wall St’s DCF model estimates future cash flows at roughly SGD5.11 per share, which screens as deeply undervalued instead.
This kind of gap between an earnings based view and a cash flow model often reflects very different assumptions about order conversion, margins and contract risk. Which framework lines up more closely with how you see Seatrium’s pipeline and balance sheet playing out over the next few years Look into how the SWS DCF model arrives at its fair value.
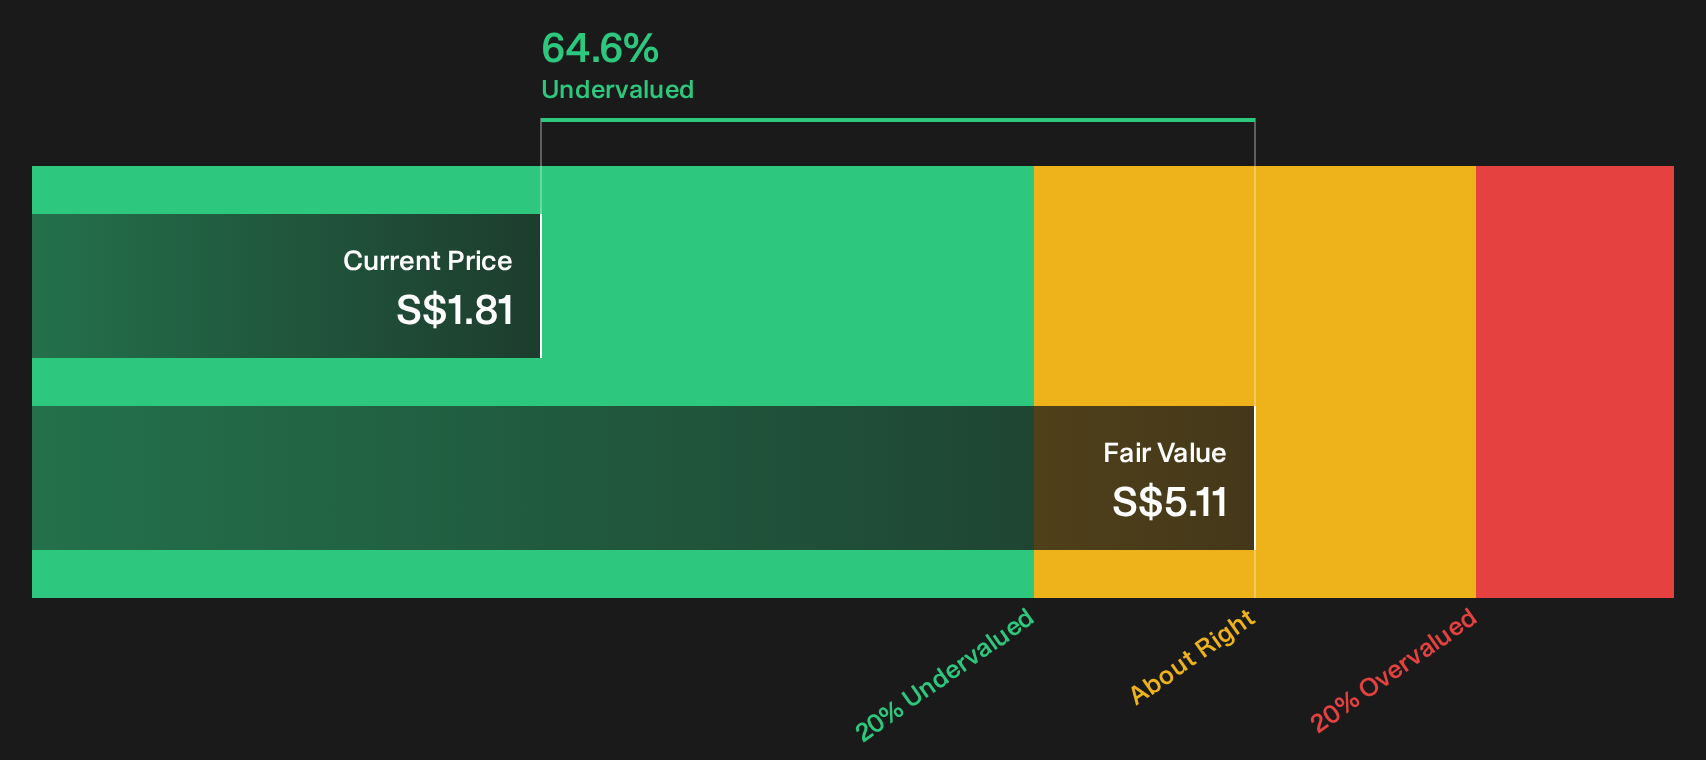
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Seatrium for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Seatrium feels familiar, consider acting promptly. Review the data and weigh both sides yourself with the 2 key rewards and 1 important warning sign.
Hunting For More Ideas Beyond Seatrium?
Do not stop at Seatrium. Use this move as a springboard to refresh your watchlist with other clear, numbers backed opportunities using the Simply Wall St screener.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (205 results) so you are not relying on one contract story to carry your portfolio.
- Spot potential value gaps early by reviewing the 194 high quality undervalued stocks that combine quality fundamentals with pricing that still looks conservative on key valuation checks.
- Lock in ideas that prioritise stability by filtering through 221 resilient stocks with low risk scores and avoid finding out too late that one holding dominated your downside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com