


Sartorius Stedim Biotech (ENXTPA:DIM) Confirmed Guidance, Is The Premium Valuation Fully Priced?
Sartorius Stedim Biotech (ENXTPA:DIM) is back in focus after Q3 2026 results and a confirmation of full year guidance, alongside tariff related customer compensation and project delay risks that investors are weighing carefully.
Recent trading tells a mixed story for Sartorius Stedim Biotech. The share price has gained 29.44% over the past 90 days, but the 1 year total shareholder return is flat at around a 0.07% decline. This hints that momentum has only recently picked up as the latest earnings and confirmed guidance recalibrate how investors are pricing growth against tariff compensation and project delay risks.
Scan Sartorius Stedim Biotech alongside other premium life science tools businesses by reviewing the hand picked list of solid balance sheet and fundamentals (205 results) that may better balance quality and valuation risk.
Sartorius Stedim Biotech has already rerated sharply on solid Q3 numbers and confirmed guidance. The real debate now is how much of the valuation upside still lies ahead rather than already in the rear view mirror.
Most Popular Narrative: 11% Undervalued
The most followed narrative puts Sartorius Stedim Biotech’s fair value at €237.29, above the last close of €210.60, which frames recent Q3 strength as only part of the story rather than the whole move.
The main thing that has to go right is that Sartorius Stedim Biotech continues to turn its heavy 2020 to 2025 CapEx build-out and new platforms in areas like intensified bioprocessing, bioanalytics and advanced cell models into sustained customer adoption and cash generation, as equipment demand and advanced therapy projects recover.
See why 3 investors see Sartorius Stedim Biotech as 11% undervalued.
Result: Fair Value of €237.29 (UNDERVALUED)
Still, the narrative around Sartorius Stedim Biotech can shift quickly if equipment orders soften again or if tariff related refunds and project delays have a greater impact than expected.
Find out about the key risks to this Sartorius Stedim Biotech narrative.
Another View: Earnings Multiple Paints A Tougher Picture For Sartorius Stedim Biotech
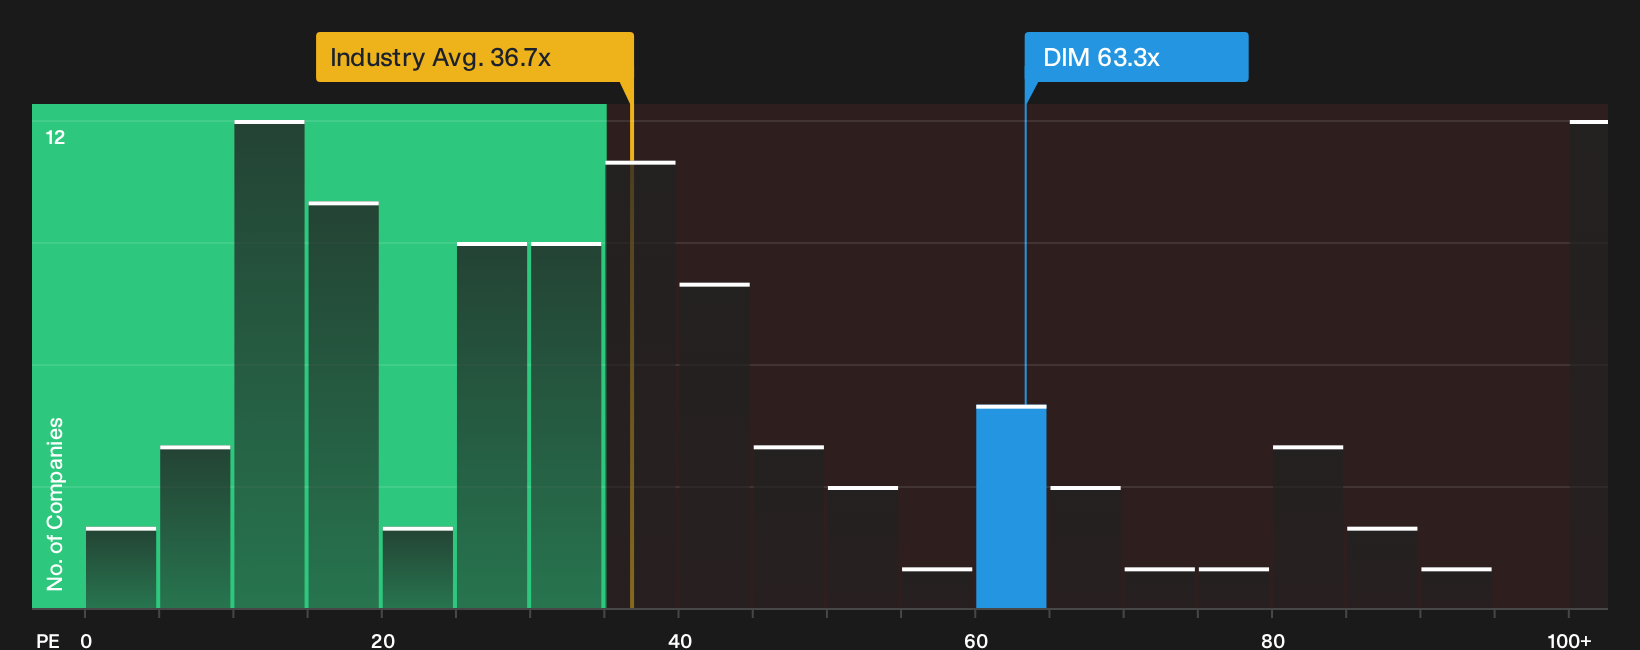
Sartorius Stedim Biotech screens as 11% undervalued on the narrative fair value of €237.29. Yet the market is already paying a rich P/E of 63.3x, compared with 36.7x for the global life sciences sector, 24.4x for peers, and a fair ratio of 33.1x that the regression model points to.
That gap means a lot of the optimism around earnings growth is already embedded in the current price, so any wobble in growth expectations could see the multiple drift back toward the fair ratio and compress returns even if profits keep rising.
See what the numbers say about this price in our detailed multiples breakdown, then decide which signal you want to trust more: the narrative fair value or the rich earnings multiple. See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Reading this, you can sense the push and pull between optimism and caution around Sartorius Stedim Biotech. Act quickly, review both the upside and the risks, and weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sartorius Stedim Biotech?
If Sartorius Stedim Biotech has sharpened your eye for quality, do not stop here. Put that mindset to work across a broader opportunity set today.
- Target potential mispricings by scanning a curated 194 high quality undervalued stocks that surfaces businesses where fundamentals and current pricing appear out of sync.
- Zero in on resilience by reviewing a 221 resilient stocks with low risk scores focused on companies with sturdier balance sheets and more stable risk profiles.
- Get ahead of the crowd by hunting through a 613 high quality undiscovered gems that highlights quality stocks still flying under most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com