


Does Strong Energy Revenue Change The Bull Case For Bolloré (ENXTPA:BOL)?
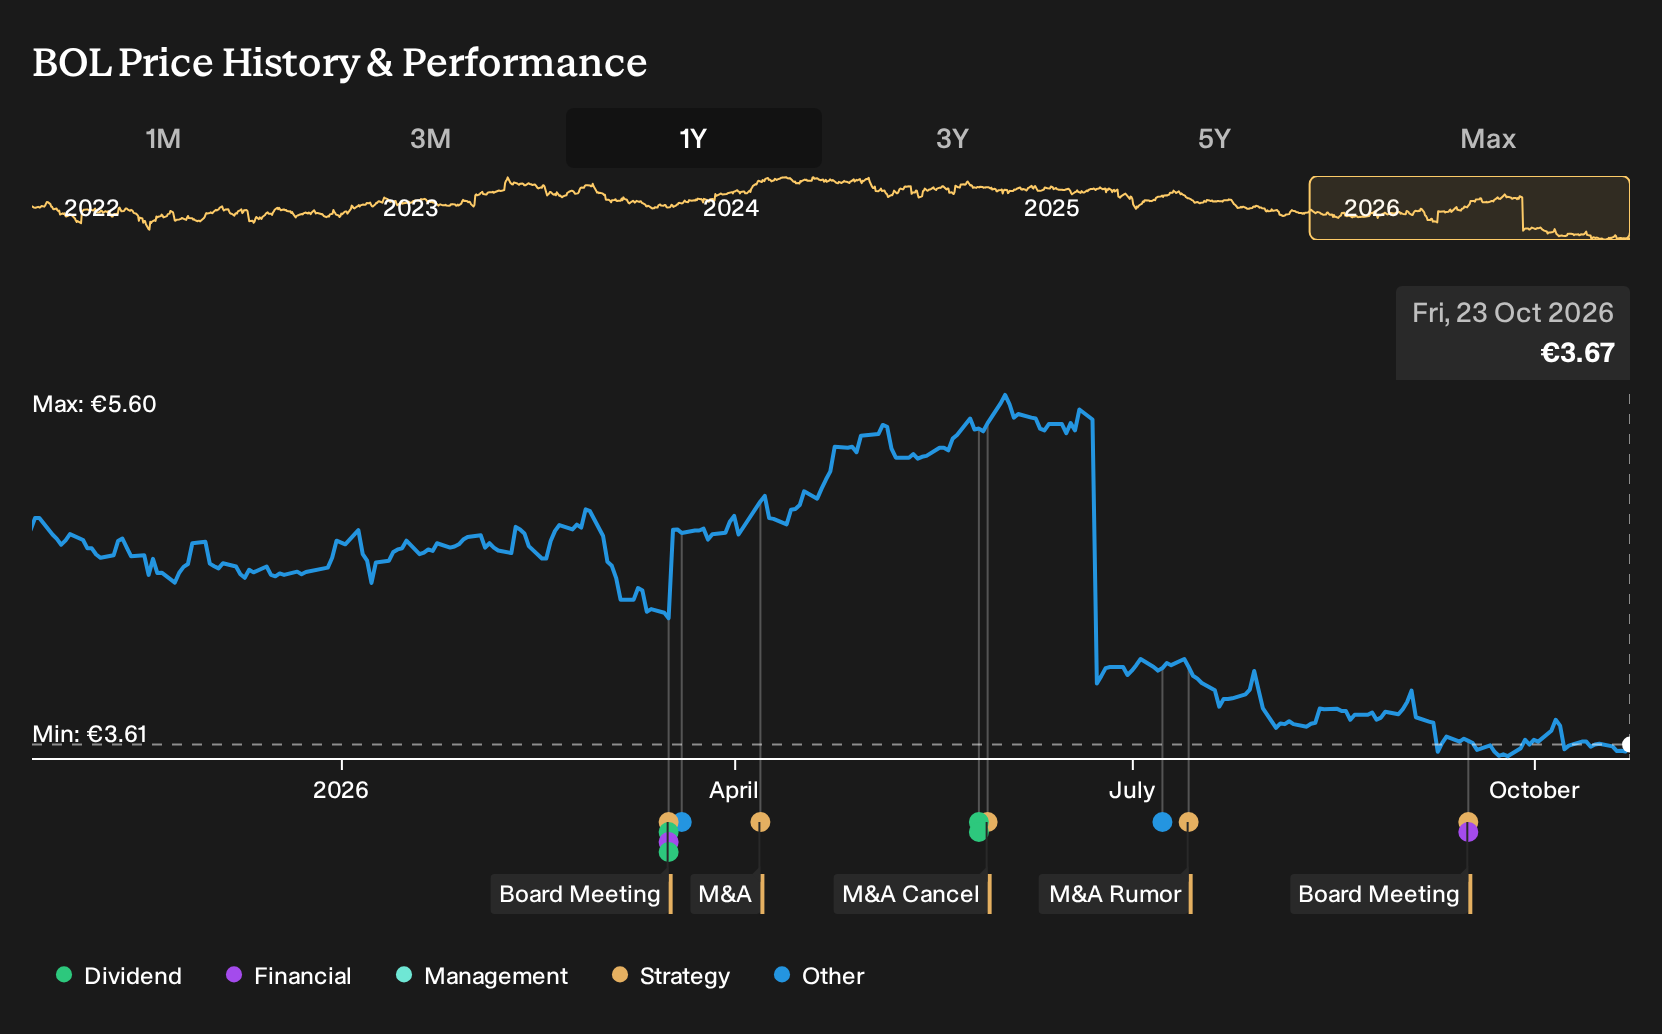
- Bolloré SE reported group revenue of €937 million for the third quarter of 2026 and €2,581 million for the first nine months, with the period shaped by strong Bolloré Energy activity, the proposed closure of Bluebus production, a refocus on 4th generation batteries and exceptional interim dividends of about €2b.
- The mix of higher energy related revenue, an exit from electric bus manufacturing, battery repositioning and sizeable cash returns highlights how Bolloré is reworking its industrial footprint and capital allocation at the same time.
- We will now look at how Bolloré’s investment narrative could shift as it leans on energy revenue and exits Bluebus production.
Compare Bolloré's repositioning around energy and dividends with other potential setups by scanning our hand picked 194 high quality undervalued stocks that also pair cash generation with disciplined balance sheets.
What Is Bolloré's Investment Narrative?
The investment case for Bolloré really hinges on whether you buy into a cash generative energy business that is being reshaped while capital is actively returned to shareholders. The Q3 revenue of €937 million and nine month figure of €2,581 million, driven by Bolloré Energy, underline how much the group now leans on that fuel distribution engine. The Bluebus exit and refocus on 4th generation batteries point to tighter capital discipline in industry, but they also introduce execution questions around restructuring and future battery demand.
In the short term, the key swing factors are simple. Can energy earnings hold up with pricing and volumes moving in different directions? Can management manage job cuts and factory changes without operational disruption or extra cash drain? Against that, you have exceptional interim dividends of about €2b landing on top of a P/E of 43.9x, profit margins that moved down to 7.8% from 14.3%, and dividends that recent free cash flow has not fully covered. For a shareholder, belief in Bolloré now means trusting that energy cash flows and battery repositioning justify that premium and the rich payout.
Even so, there is a less comfortable side to this story that starts with the way Bolloré funds...
There's only one way to know the right time to buy, sell or hold Bolloré. Head to Simply Wall St's company report for the latest analysis of Bolloré's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly €2.61 to €4.19 per share, which already shows how far retail views on Bolloré can stretch. Those opinions were formed before the Q3 2026 revenue update and Bluebus exit plan, so you should stress test them against the energy tilt and dividend focus yourself.
Explore another Bolloré fair value estimate, including one that suggests as much as 14% upside from the current price.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A great starting point for your Bolloré research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Bolloré. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Bolloré's overall financial position at a glance.
Looking For More Ideas Beyond Bolloré?
Once you have a view on Bolloré, it often helps to compare that thesis with other opportunities that line up with your risk tolerance and income or growth goals. The Simply Wall St Screener can quickly surface stocks that mirror the qualities you care about, whether that is resilient balance sheets, dependable income or underappreciated quality.
- For investors who want quality at a measured price, compare Bolloré with a curated set of potentially resilient compounders through the 194 high quality undervalued stocks.
- If capital strength and financial durability matter most to you, filter for companies with robust funding profiles using the list of solid balance sheet and fundamentals (205 results).
- For those who prioritise regular income, line up Bolloré against higher yielding payers by scanning a focused group of 226 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com