


Is Talen Energy (TLN) Still Cheap After Its Run Up And Valuation Debate?
Recent commentary around Talen Energy (TLN) has focused on a very large multi-year share price run, contrasting that move with its higher price-to-sales ratio and a bespoke valuation model that still indicates potential undervaluation.
Recent trading has cooled. The latest 1-day share price return declined 1.06% and the 7-day share price return fell 7.58%. However, the 30-day share price return is up 7.72%, while the 3-year total shareholder return of about 7x still points to very strong longer term gains for Talen Energy.
Scan how Talen Energy compares and spot other utilities with similar potential rerating setups using our curated list of 29 high quality undervalued stocks.
Talen Energy has already delivered a very large 3 year gain, yet the current share price still sits well below both analyst targets and intrinsic estimates. So where does fair value actually land in that gap?
Most Popular Narrative: 29% Undervalued
The most followed narrative on Talen Energy pegs fair value at about $460.59 using an 8.33% discount rate, compared with a last close of $327.91. The debate now centers on whether the cash flow story can bridge that gap.
The current valuation implies Talen Energy is undervalued relative to its guidance and outlook, given management’s expectation of roughly $4b of adjusted free cash flow from mid 2026 through 2028 and a policy to return at least 70% of that amount to shareholders via buybacks.
See why 56 investors see Talen Energy as 29% undervalued.
Result: Fair Value of $460.59 (UNDERVALUED)
Still, the Talen Energy story can be knocked off course if prolonged GAAP losses continue or if softer PJM power pricing keeps squeezing revenue and earnings multiples.
Find out about the key risks to this Talen Energy narrative.
Another View: What Talen Energy’s P/S Ratio Is Telling You
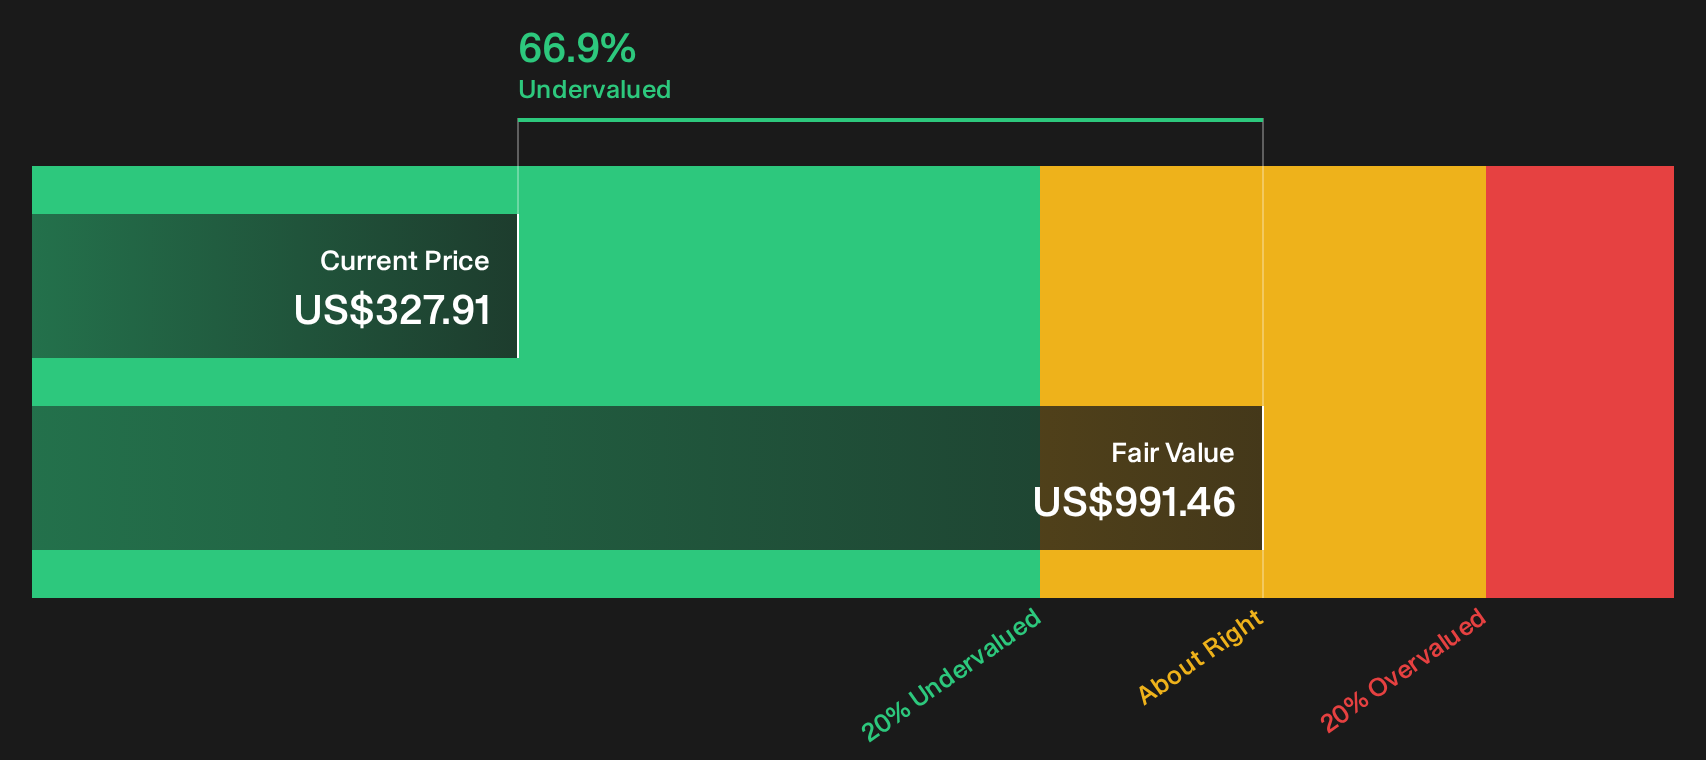
The SWS DCF model points to strong upside for Talen Energy, with an estimated future cash flow value of $991.46 against a share price of $327.91, which screens as undervalued. That is a very different signal from a simple P/S check that flags TLN as expensive. Which signal would you trust more in your own work?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages around Talen Energy’s valuation and risk reward profile can pull you in opposite directions, so move quickly, review the underlying numbers yourself, and then pressure test your own thesis against the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Talen Energy?
If you stop with Talen Energy, you only see one angle. Broaden your watchlist now so you do not miss other compelling setups.
- Target potential mispricings by scanning for proven quality that still trades cheaply through our curated 29 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with cleaner finances via the list of solid balance sheet and fundamentals (24 results).
- Spot under-the-radar opportunities early by reviewing the 21 high quality undiscovered gems before the crowd catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com