


What Otis Worldwide (OTIS) Fiduciary Breach Investigation Means For Shareholders
- Otis Worldwide is facing an investigation into possible fiduciary breaches by certain officers and directors, raising fresh questions about oversight and capital allocation discipline.
- The governance probe arrives while Otis Worldwide is leaning heavily on its service led model and modernization backlog. Any trust gap around leadership decisions could shape how confidently investors view those long dated cash flows.
- Next is an examination of how Otis Worldwide's governance investigation could reshape the existing investment narrative around its service led model.
Otis Worldwide Investment Narrative Recap
To own Otis Worldwide, you need to be comfortable with a service-led elevator and escalator model where recurring maintenance and modernization work drive most of the value. The short-term swing factor is whether management can stabilise service retention around current levels and protect the 2.5 million unit portfolio while working through cost headwinds and mixed new equipment demand.
The governance investigation sits alongside this operational backdrop. If it stays contained, the main story still rests on converting a larger modernization backlog and connected base into healthier margins. The bigger risk right now is that weaker service profitability and productivity issues linger, which would keep pressure on earnings and cash generation.
One data point investors are watching is the recent reset to 2026 adjusted EPS guidance to US$4.01 to US$4.05 after an earnings miss. That guidance ties directly to Otis Worldwide execution on pricing tools, productivity programs and the roll out of AI-driven micro pricing in maintenance and repair.
The guidance cut and slower ramp in those digital tools highlight how sensitive the model is to service margins and retention. For you as a shareholder, the question is whether modernization growth, connected units on Otis ONE and efficiency initiatives can offset the current drag from higher costs and a more cautious pricing approach while governance questions remain in the background.
What The 2029 Consensus Implies For Otis Worldwide
Otis Worldwide's narrative projects US$17.4b revenue and US$1.9b earnings by 2029. That path assumes 5.2% yearly revenue growth and an earnings increase of about US$400m from US$1.5b today.
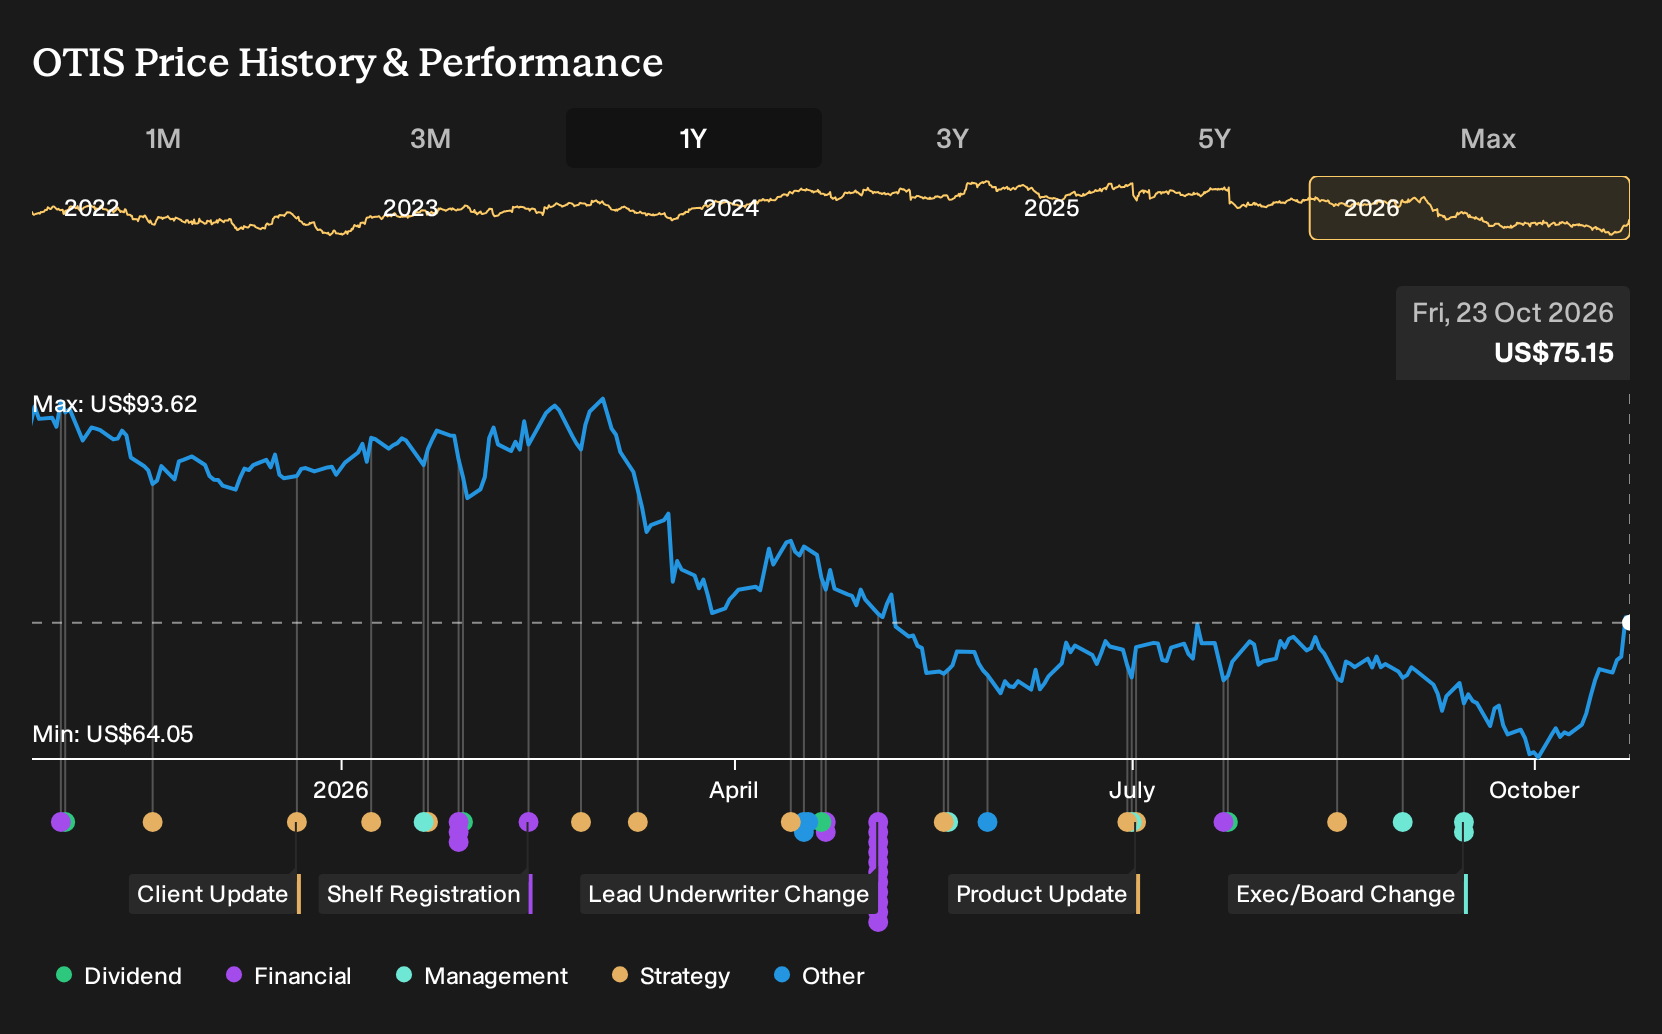
Uncover how Otis Worldwide's fair value indicates a 17% potential upside to its current price, which could narrow quickly if Otis Worldwide executes on its service thesis.
Exploring Other Perspectives
One alternate take on Otis Worldwide puts less weight on the modernization backlog and more on the risk that execution simply stays slow. The most cautious analysts were pencilling in about US$17.0b of revenue and US$1.9b of earnings by 2029 before this governance news, which could push that already muted story in either direction.
Explore 4 other Otis Worldwide fair value estimates, including one that suggests it could be worth just $73.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Otis Worldwide research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Otis Worldwide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Otis Worldwide's overall financial health at a glance.
Looking For More Investment Ideas Beyond Otis Worldwide?
If the governance story at Otis Worldwide has you reassessing your risk tolerance, it can help to widen the lens and compare with other opportunities that better match your preferences on income, resilience and long term potential.
- For investors who care most about financial resilience and balance sheet strength, the list of solid balance sheet and fundamentals (24 results) can help you focus on businesses with sturdier foundations.
- If you want potential mispricings where quality and valuation line up more cleanly than they do for Otis Worldwide right now, you can scan through the 29 high quality undervalued stocks.
- Those hunting for income ideas can zero in on companies built around regular payouts by reviewing the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com