


What ASML Holders Bought Into
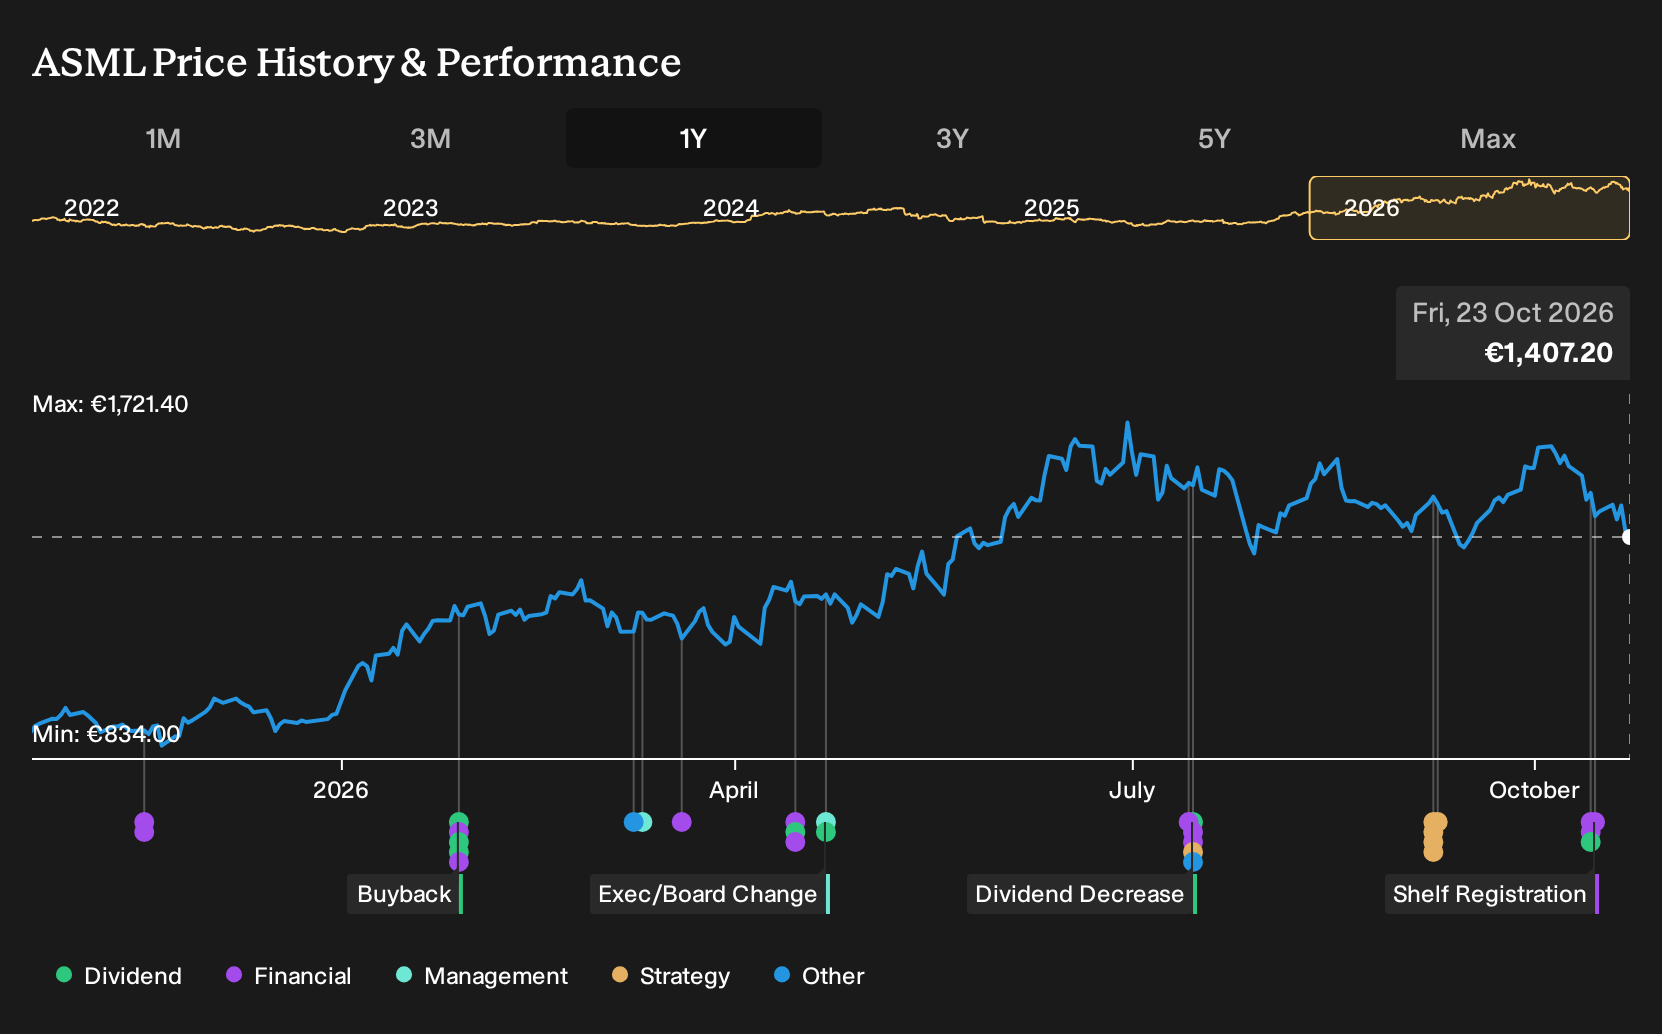
If you looked at ASML a year ago, you saw the only EUV supplier positioned between a bullish camp arguing for accelerating AI-driven tool demand and a cautious group focused on export controls and High-NA adoption risks. Investors who held ASML over the past year are up 58.4%, including dividends. If you had been deciding on 23 October 2025, how would you have weighed explosive AI orders against mounting China restrictions and fresh local competition headlines?
The move put ASML in the middle of this trade. Scan 55 AI infrastructure stocks for other companies exposed to it.
The Two ASML Stories Investors Had To Compare
The shares cost €888 at the start of the period, and you had to decide which ASML story felt more realistic.
The bullish Narrative pointed to a Fair Value of €950, a price implied by expectations of 11.9% annual revenue growth and net margin rising from 29.3% to 30.8% by 2028. Supporters leaned on AI, cloud and tech sovereignty to argue for stronger EUV and High-NA demand and a surge in ultra high margin service contracts.
The more cautious Narrative anchored on a Fair Value of €769 and still expected High-NA EUV and AI demand to drive system sales, but only with 7.2% revenue growth and a 30.5% margin assumption. This side focused on export restrictions, tariffs and High-NA adoption timing as key risks to those earnings hopes.
What The ASML Evidence Did To The Argument
ASML’s Q3 2026 report showed revenue of €11.7b and net income of €5.0b, with net margin at 42.5% versus 28.3% a year earlier. That combination of higher sales, wider profitability and a backlog that shifted from taking orders to allocating supply clearly leaned toward the optimistic AI demand story. Fresh MATCH Act headlines and new Chinese lithography capacity still challenged the idea of an unconstrained addressable market, so the evidence cut both ways.
The hinge assumption here was not just AI excitement but whether demand would translate into sustained pricing power and higher margins. For any other chip equipment stock, it is useful to track reported backlog, realised gross and net margin, and how export rules actually show up in segment sales rather than treating them as abstract risk.
What You Would Be Paying For In ASML Today
ASML now trades at €1,407, well above the level used in the current cautious Narrative, which places its Fair Value below today’s share price rather than at or above it.
The Narrative highlights an exceptional competitive moat and service flywheel, yet suggests buyers now must assume that rich AI driven capacity plans and High-NA adoption all line up. How does export constraint risk and potential lithography catch up elsewhere align with that expectation?
"The problem is not ASML. The problem is the price investors are being asked to pay for it."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Go Straight To The Source
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 44% below our estimate - turn long term ocean monitoring demand and traffic sensors into higher margin solution bundles.
- Company 2 - 22% below our estimate - expand robotics guided joint procedures as hospitals adopt more Mako based surgical workflows.
- Company 3 - 36% below our estimate - scale high horsepower engine capacity to meet multiyear data center power contracts.
Those are three of them. See all 194 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com