


Xcel Energy (XEL) Faces Wildfire And Credit Pressure, Is It Still 13% Undervalued?
Fresh scrutiny of Xcel Energy (XEL) centers on more than $1.1b in wildfire related liabilities, limited remaining insurance, and a recent negative credit outlook from Moody's. This combination puts financial risk front and center for investors.
Against that backdrop, Xcel Energy’s recent share price tells a mixed story. The stock is up 11.82% on a 30-day share price return but has declined 3.30% over 90 days, while a 48.09% three-year total shareholder return points to longer term resilience despite the wildfire and credit concerns now back in focus.
Compare Xcel Energy's wildfire risk and credit pressure with peers that screen stronger on balance sheet strength and fundamentals using our hand picked list of solid balance sheet and fundamentals (24 results).
After an 11.82% 30 day rebound and fresh scrutiny on more than $1.1b of wildfire liabilities, Xcel Energy now forces a choice: Do you pay up today or wait for a cleaner entry as the risk is repriced?
Most Popular Narrative: 13% Undervalued
Xcel Energy’s most followed narrative pegs fair value at $89.44, above the recent $78.05 close. This puts the wildfire liability overhang in the context of a longer term electrification and data center build-out story.
The main thing that has to go right is that Xcel Energy continues to secure constructive regulatory outcomes and effectively implement large load tariffs so that billions of dollars of data center driven grid and generation investment are recovered on terms that protect existing customers and support allowed returns.
The current valuation implies investors are pricing Xcel Energy below what this narrative views as fair for a regulated utility with reaffirmed 2026 EPS guidance of $4.04 to $4.16, a long record of meeting guidance, and a visible multi decade capital programme tied to data center and clean energy demand.
See why 17 investors see Xcel Energy as 13% undervalued.
Result: Fair Value of $89.44 (UNDERVALUED)
Still, the wildfire liabilities and any shift in regulatory support or tariff design could quickly weaken the bullish Xcel Energy narrative that investors are leaning on today.
Find out about the key risks to this Xcel Energy narrative.
Another View: Xcel Energy Through A Different Lens
The analyst-led narrative frames Xcel Energy as about 13% below fair value, yet the DCF cross-check points in the opposite direction. Our DCF model puts future cash flow value closer to $71.73 per share, which would leave today’s $78.05 price looking overvalued instead of cheap.
That gap forces a simple question for anyone studying Xcel Energy: Are earnings based forecasts too generous, or is the cash flow model too strict on wildfire risk and funding needs, and which one would you lean on when pressure rises?
Look into how the SWS DCF model arrives at its fair value.
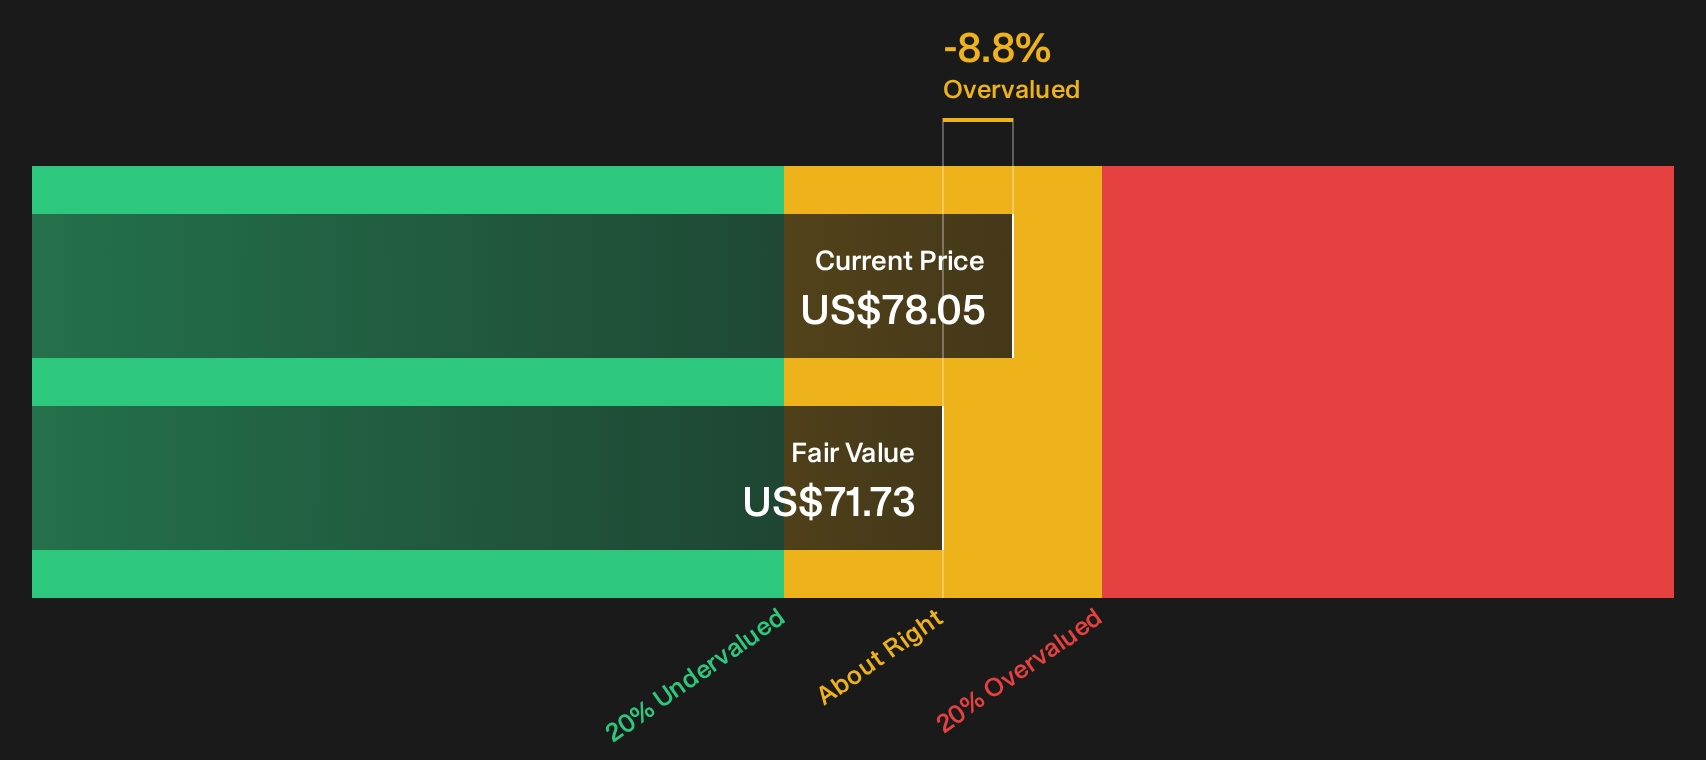
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Xcel Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of wildfire risk and valuation tension around Xcel Energy feels finely balanced, consider promptly reviewing the data yourself and pressure testing both sides of the story using our 2 key rewards and 2 important warning signs.
Looking for more Xcel Energy style investment ideas?
If Xcel Energy has you thinking harder about risk, value, and balance sheet strength, do not stop at a single ticker. Broaden your watchlist now with curated ideas that fit clear, disciplined criteria.
- Target quality at a discount by scanning companies that combine resilient fundamentals with appealing valuations using our 29 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that offer 5%+ yields while aiming to keep payouts supported by underlying cash flow through the 5 dividend fortresses.
- Dial down portfolio stress by focusing on businesses that carry lower risk scores and sturdier financial profiles inside the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com