


Does Earnings Beat Change The Bull Case For Manhattan Associates Stock (MANH)?
- Kesko Corporation announced it selected Manhattan Associates' ActiveWarehouse platform, including Wave Coordinator, Labour and Warehouse Associate Agents, and is evaluating further inbound-focused agents through Agent Foundry to support its warehouse operations.
- The decision gives Manhattan Associates another reference client for embedded AI agents in real warehouse workflows, reinforcing how demand for automation and productivity gains is feeding into the company’s cloud and agent adoption story.
- We will look at how Manhattan Associates' strong quarterly revenue beat and guidance raise interact with this client win to reshape its investment narrative.
Scan how Manhattan Associates fits into the wider push for AI driven logistics, and compare it with a hand picked set of 95 robotics and automation stocks shaping the future of warehouse automation.
Manhattan Associates Investment Narrative Recap
To hold Manhattan Associates you need to believe its warehouse and supply chain software can keep attracting long contracts to the Manhattan Active cloud platform, and that embedded AI agents move from pilots into everyday workflows. The Kesko agreement fits this story, but by itself does not radically change the near term outlook.
The key short term swing factor remains execution on cloud bookings and on prem to cloud conversions after a strong revenue beat and raised EPS guidance. The main risk is that high expectations, a rich P/E multiple and recent insider selling meet any slowdown in bookings, AI agent adoption or Active implementations.
The most relevant recent update is the strong quarter where Manhattan Associates reported US$297.8m in revenue, up 9.3% year on year and 3.5% above analyst estimates, alongside a full year EPS guidance raise. Management pointed to record first half results, strong demand and accelerated revenue growth, which set a high bar for follow up quarters.
Set against that backdrop, wins like Kesko become proof points for three big drivers that readers should watch. These are continued interest in embedded AI agents, the Editions packaging that opens smaller and mid market sites, and the conversion engine from on prem to cloud. Any wobble in bookings or RPO against that strong starting point would likely matter more than individual deal headlines.
Manhattan Associates' current consensus setup points to revenues of US$1.4b and earnings of US$306.5m by 2029. This is based on analyst forecasts of 8.2% yearly revenue growth and an earnings increase of about US$96.3m from US$210.2m today.
Uncover why Manhattan Associates' fair value indicates a 4% potential downside to its current price; this valuation premium leaves little room for error.
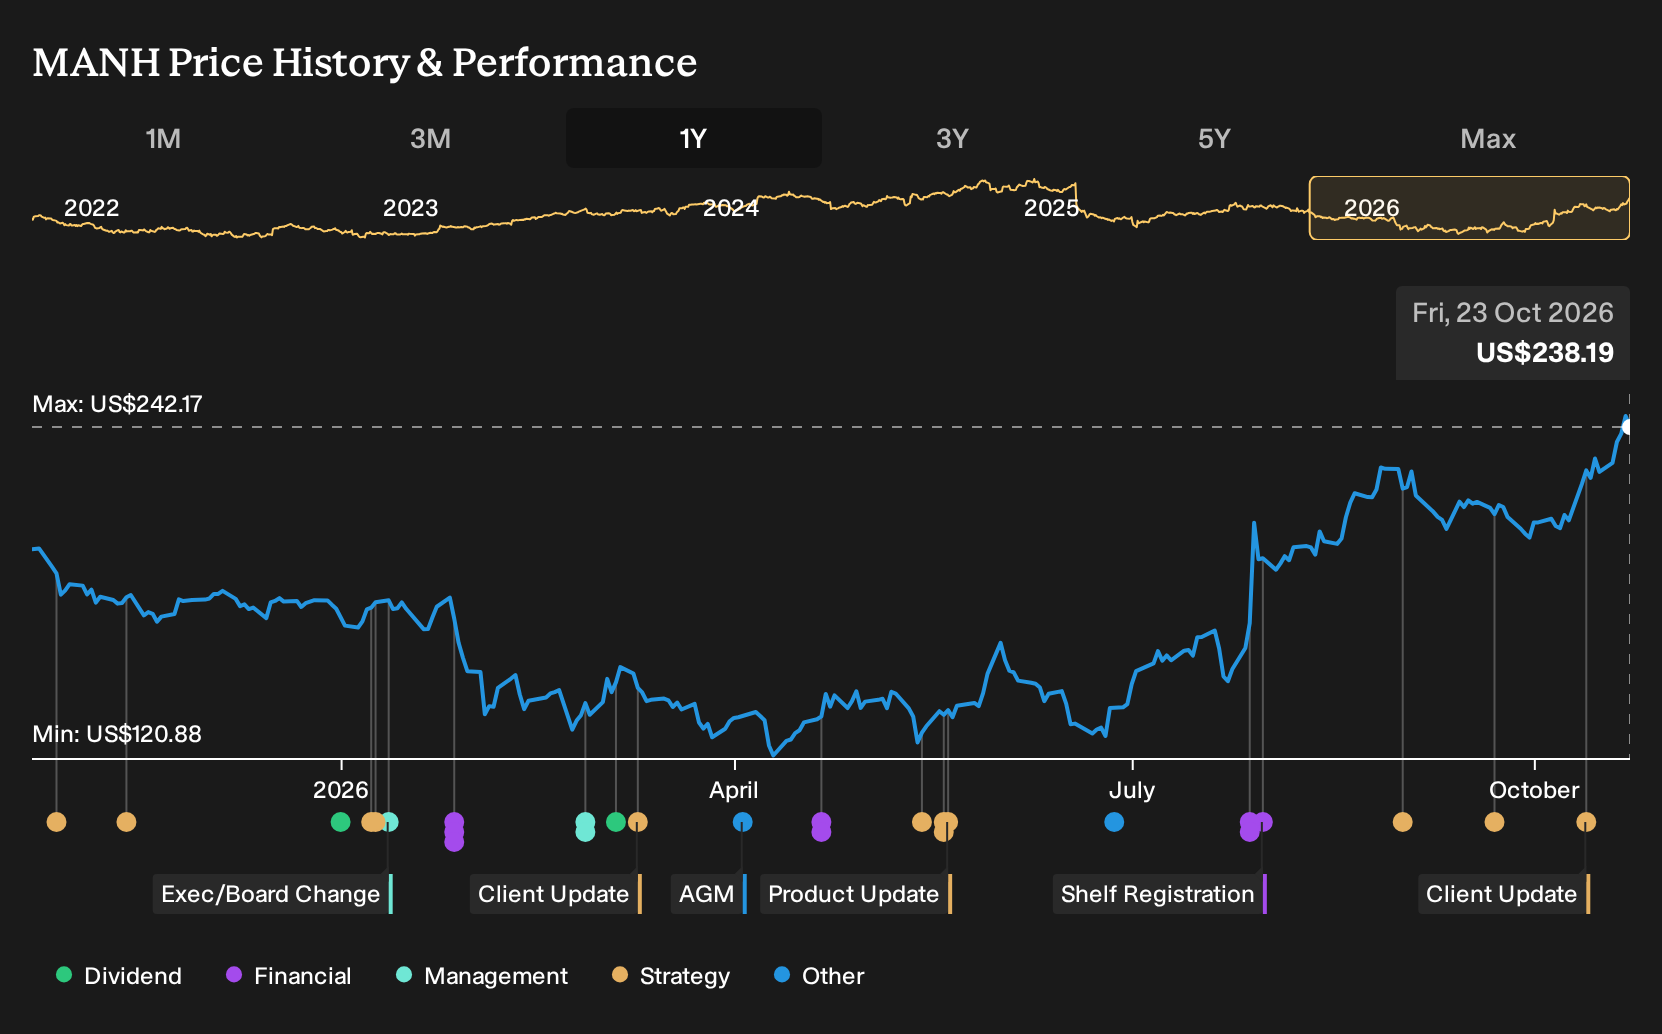
Exploring Other Perspectives
One alternate view around Manhattan Associates hinges on governance risk rather than cloud upside. The most cautious analysts focus on investigations into potential fiduciary duty breaches and had previously expected 9.5% yearly revenue growth with earnings of about US$322.2m by 2029. You should treat the Kesko AI agent win as fresh information that might shift both camps over time.
Explore 5 other Manhattan Associates fair value estimates, including one that suggests up to 9% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Manhattan Associates research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Manhattan Associates. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Manhattan Associates' overall financial health at a glance.
Looking For More Investment Ideas Beyond Manhattan Associates?
If Manhattan Associates is already on your radar, it can help to set it alongside other candidates with different strengths so you can judge risk, quality, and income potential side by side.
- If capital preservation sits high on your list, start with companies that pass our resilience filters and review the 30 resilient stocks with low risk scores.
- For investors hunting for strong balance sheets and cleaner fundamentals, use the list of solid balance sheet and fundamentals (24 results) as a quick way to surface candidates worth a closer look.
- If you prefer businesses the market may not be paying full attention to, scan through a curated set of 21 high quality undiscovered gems and see which ones fit your checklist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com