


Westinghouse Air Brake Technologies (WAB) On Strong Q3 Results And Reaffirmed Guidance Is It Fully Valued
Westinghouse Air Brake Technologies (WAB) has just put fresh numbers on the table. Third quarter results, full year 2026 guidance and a new shelf registration are now shaping how investors reassess the stock.
Recent trading has cooled some of that enthusiasm, with the share price down 5.0% over the past week and 9.5% over the last three months. Even so, Westinghouse Air Brake Technologies still carries a 25.9% year to date share price gain and a 38.5% one year total shareholder return, which points to solid longer term momentum as investors reassess the latest earnings beat, reaffirmed 2026 guidance and the fresh shelf registration.
Compare Westinghouse Air Brake Technologies with other rail and heavy-industry operators by scanning our hand picked 42 power grid technology and infrastructure stocks that may also be reacting to infrastructure demand and capital spending cycles.
Westinghouse Air Brake Technologies is now trading below both analyst targets and one intrinsic value estimate, even after a strong run. Is the recent pullback a sensible risk check or an opportunity the market is mispricing?
Most Popular Narrative: 17% Undervalued
On the most followed narrative, Westinghouse Air Brake Technologies screens only slightly below an intrinsic value estimate of $329.58. The last close at $272.35 is framed through an 8.73% discount rate and multiyear rail demand assumptions.
Sustained global investment in rail infrastructure and modernization across freight and transit, including large international awards in regions such as Australia and Latin America, is feeding into Westinghouse Air Brake Technologies’ multiyear backlog above US$30b and could support more stable revenue and earnings over several years.
Growing adoption of fuel efficiency and decarbonization programs, including locomotive modernization cycles and initiatives like EVO Advantage and Zero to Zero, is increasing the opportunity to attach higher value equipment and aftermarket solutions that can support both revenue and net margin expansion.
See why 23 investors see Westinghouse Air Brake Technologies as 17% undervalued.
Result: Fair Value of $329.58 (UNDERVALUED)
Still, the narrative around Westinghouse Air Brake Technologies can crack if tariffs keep squeezing margins or if insider selling leads to a sharper valuation reset.
Find out about the key risks to this Westinghouse Air Brake Technologies narrative.
Another View: What Multiples Say About Westinghouse Air Brake Technologies
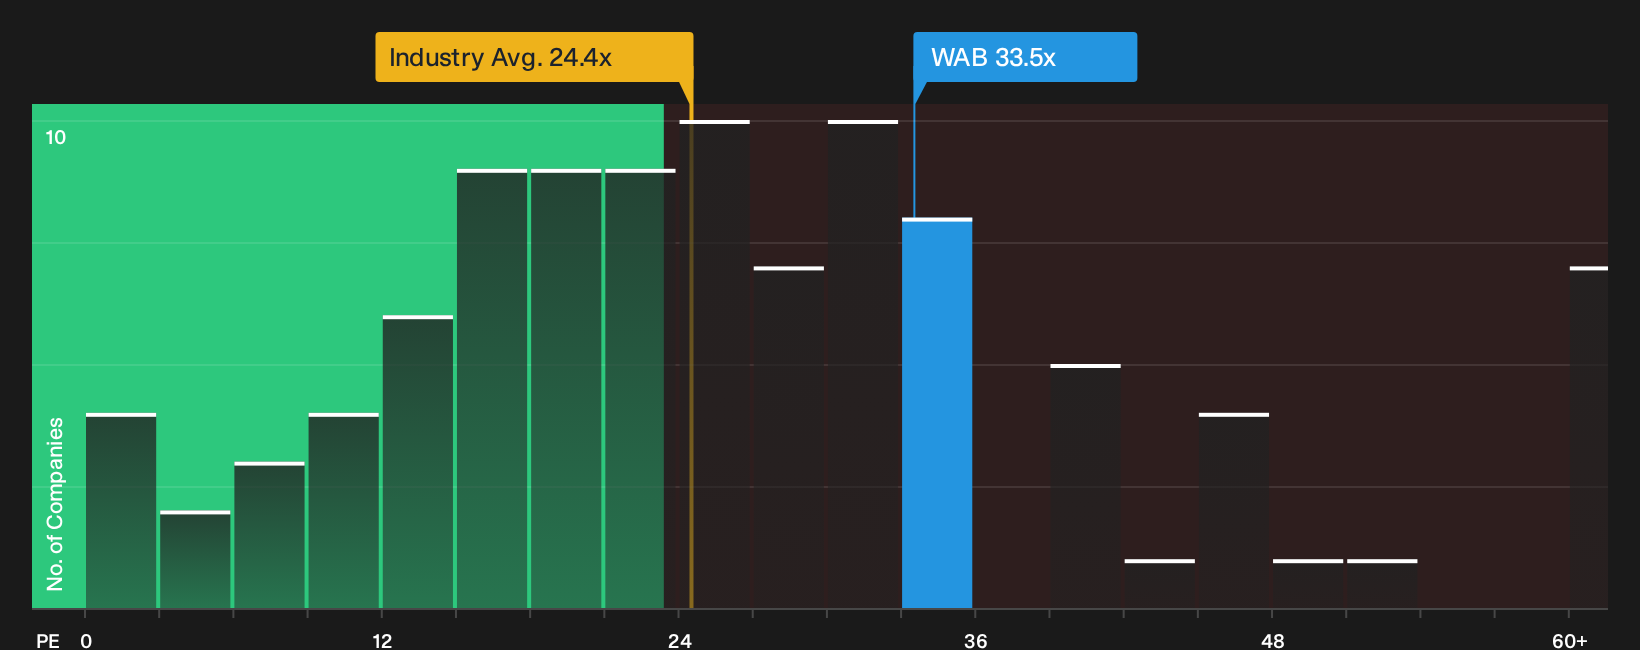
The first narrative leans on discounted cash flows and analyst targets to frame Westinghouse Air Brake Technologies as slightly undervalued. A simple earnings multiple tells a sharper story. WAB trades on a P/E of 33.5x versus 24.4x for the US Machinery group and a fair ratio of 31.6x, which points to a valuation that already bakes in strong execution and leaves less room for error if expectations slip.
If you prefer to anchor your work on market based ratios rather than models of future cash flows, it is worth stress testing that earnings multiple against your own assumptions and risk tolerance before leaning on the bullish narrative. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Westinghouse Air Brake Technologies so far. Act quickly, review both the risks and the upside potential, then weigh the 4 key rewards and 2 important warning signs.
Looking for more Westinghouse Air Brake Technologies investment ideas?
If you stop with Westinghouse Air Brake Technologies, you risk missing other opportunities. Use the Simply Wall Street Screener to broaden your watchlist intelligently right now.
- Target potential mispricings by scanning a focused universe of companies trading below intrinsic value using the 29 high quality undervalued stocks.
- Strengthen your income stream by filtering for companies with payout profiles that match your comfort level using the 5 dividend fortresses.
- Dial back risk by building a shortlist of businesses with resilient finances drawn from the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com