


Navy Contract Wins Might Change The Case For Investing In HII Stock
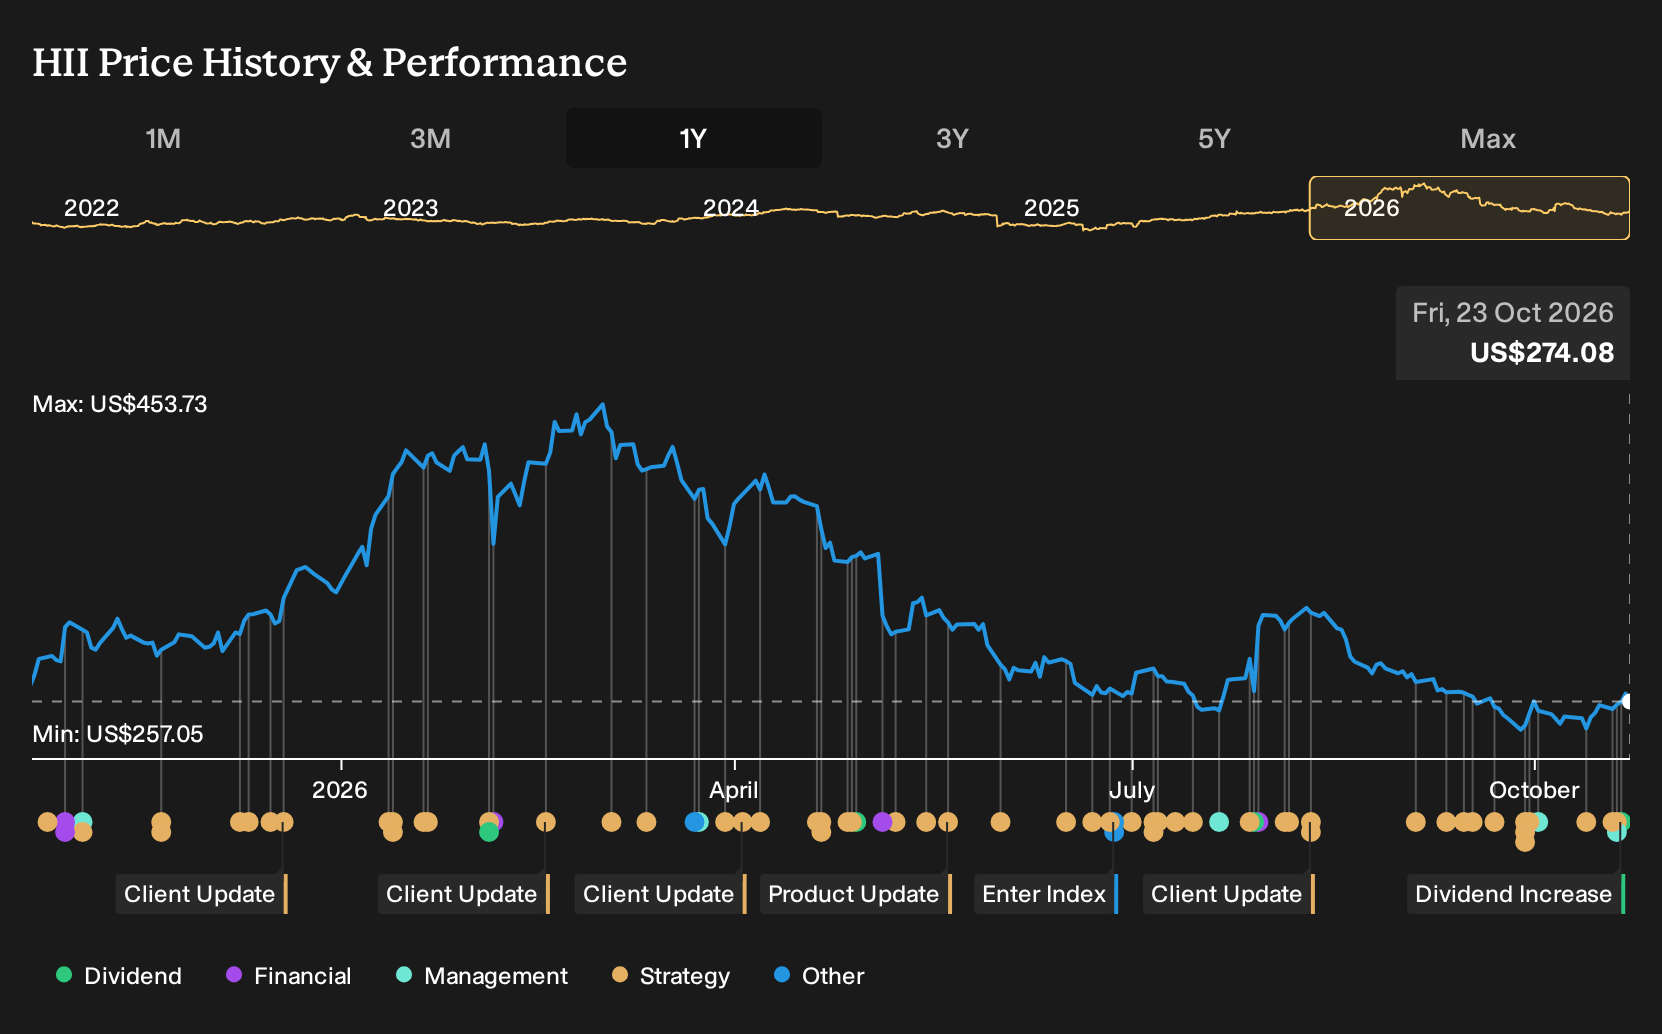
- Huntington Ingalls Industries recently reported a series of contract wins across Zumwalt-class destroyer work, AUKUS submarine design support, and a 10-vessel ROMULUS unmanned surface fleet, along with a higher quarterly dividend of $1.41 per share payable in December 2026.
- The mix of nuclear shipbuilding work, autonomous vessel programs, and a rising cash payout highlights how HII’s backlog-driven model connects long-duration defense projects to a growing income stream for shareholders.
- We will now explore how Huntington Ingalls Industries’ investment narrative is influenced by the ROMULUS autonomous vessel contract momentum.
Scan Huntington Ingalls Industries’ latest contract and dividend momentum against a curated field of peers by reviewing 42 power grid technology and infrastructure stocks that are helping modern defense and infrastructure networks run reliably.
Huntington Ingalls Industries Investment Narrative Recap
To own Huntington Ingalls Industries, you need to believe its backlog-heavy model can convert long-duration carrier, submarine and destroyer work, plus Mission Technologies contracts, into steadier cash generation and gradually higher shipbuilding margins. The key short-term swing factor remains whether throughput and cost discipline hold as Newport News carrier execution and supply chain pressures are worked through.
The dividend increase to US$1.41 per share and fresh Navy wins do not fundamentally change that near-term catalyst. They do, however, raise the bar on free cash flow delivery at a time when debt is not well covered by operating cash flow and 2026 guidance is back-end weighted.
The ROMULUS Medium Unmanned Surface Vessel award is the clearest operational link to the recent news. A 10-vessel order supports the view that Huntington Ingalls Industries can build a meaningful, potentially higher-margin autonomous systems line alongside traditional hulls, while deepening ties to the U.S. Navy on emerging concepts of unmanned operations.
For catalysts, this program sits where investors are watching execution most closely. Successful delivery of the first ROMULUS 151 units, reliable scaling at the Pocasset unmanned campus, and disciplined cost control could support Mission Technologies earnings and help offset any margin pressure if carrier programs or cash conversion fall short of expectations.
Huntington Ingalls Industries Consensus Growth Setup
Analysts are effectively tying the Huntington Ingalls Industries ROMULUS thesis to the same set of numbers that underpin the broader shipbuilding and Mission Technologies story. Their models point to revenue expanding at 5.2% a year over the next three years, with profit margins rising from 5.0% today to 6.3% as higher throughput, automation projects and unmanned programs feed through the income statement.
On earnings, the consensus view anchors on profit today of US$661.0 million stepping up to US$965.0 million by 2029. That is an increase of about US$304.0 million. Forecast earnings per share of US$25.03 in 2029 sit inside a wider range, with the more optimistic forecasts calling for profit closer to US$1.2b, so ROMULUS execution and unmanned campus scaling could be one of the swing factors that push outcomes toward either end of that band.
Huntington Ingalls Industries' narrative projects US$15.3b revenue and US$965.0 million earnings by 2029. This rests on 5.2% yearly revenue growth and an earnings increase of about US$304.0 million from US$661.0 million today.
The valuation bridge that links those operational goals to the current share price is straightforward. To line up with the analyst consensus target, investors would need to assume Huntington Ingalls Industries reaches that US$15.3b top line and US$965.0 million profit in 2029 and trades on a P/E of 18.9x, compared with about 15.9x today and a reported sector multiple of 34.1x. The implied fair value target of US$356.42 per share sits about 25.0% above the recent US$267.22 price, with published targets stretching from US$281.0 to US$406.0.
None of this hinges only on unmanned vessels. It does, however, give ROMULUS and the broader autonomous portfolio a clear role in the numbers. If those contracts help lift margins toward the projected 6.3% level and support the shift from US$661.0 million to US$965.0 million of earnings by 2029, they strengthen the case for the higher P/E multiple that analysts are using in their models.
Uncover why Huntington Ingalls Industries' fair value indicates a 30% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view you may want to stress test focuses on Huntington Ingalls Industries’ unmanned business as a slower burn. The most cautious analysts were pencilling in revenue of about US$15.2b and earnings of roughly US$892.4 million by 2029 before this dividend hike and ROMULUS contract, which could eventually nudge those expectations in either direction.
Explore 4 other Huntington Ingalls Industries fair value estimates, including one that suggests it could be worth just $287.18.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Huntington Ingalls Industries research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Huntington Ingalls Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Huntington Ingalls Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Huntington Ingalls Industries?
Once you understand where Huntington Ingalls Industries sits in your portfolio, it often helps to line it up against other opportunities that match your risk tolerance and income goals. The Simply Wall St Screener can help you scan across markets quickly and focus on companies that fit the kind of profile you are actually looking for.
- If you want potential upside without ignoring quality, start with a focused list of 21 high quality undiscovered gems that pair strong fundamentals with lower market attention.
- For investors who prefer resilient balance sheets and fewer surprises, filter the market using a 30 resilient stocks with low risk scores that concentrates on businesses with steadier financial profiles.
- If income is a priority and you want yield supported by fundamentals, look through a 5 dividend fortresses that spotlights companies offering higher payouts backed by solid cash generation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com