


EssilorLuxottica Stock And the Eyewear Shares Worth Watching Now
Eyewear suddenly looks a lot more interesting to investors. A strong Q3 update that put sales at €7.49b and showed 20% growth in smart glasses and wearables has pushed EssilorLuxottica into the spotlight, even as family governance disputes create fresh headlines. This mix of momentum and uncertainty can create mispricing. This article unpacks how the news hits three stocks from the Global Eyewear & Vision Care Leaders screener.
The three stocks covered next are only a sample from this theme, and the full Global Eyewear & Vision Care Leaders screen surfaced 12 more companies with similarly detailed stories that are not covered here. To size up the sector properly, head straight into the Global Eyewear & Vision Care Leaders screener to identify, compare, and analyze the highest conviction candidates for your watchlist.
EssilorLuxottica Société anonyme (ENXTPA:EL)
Overview: EssilorLuxottica Société anonyme is a global eyewear and vision care group that designs, manufactures, and sells lenses, frames, sunglasses, optical equipment, and related services through wholesale partners and its own retail stores worldwide.
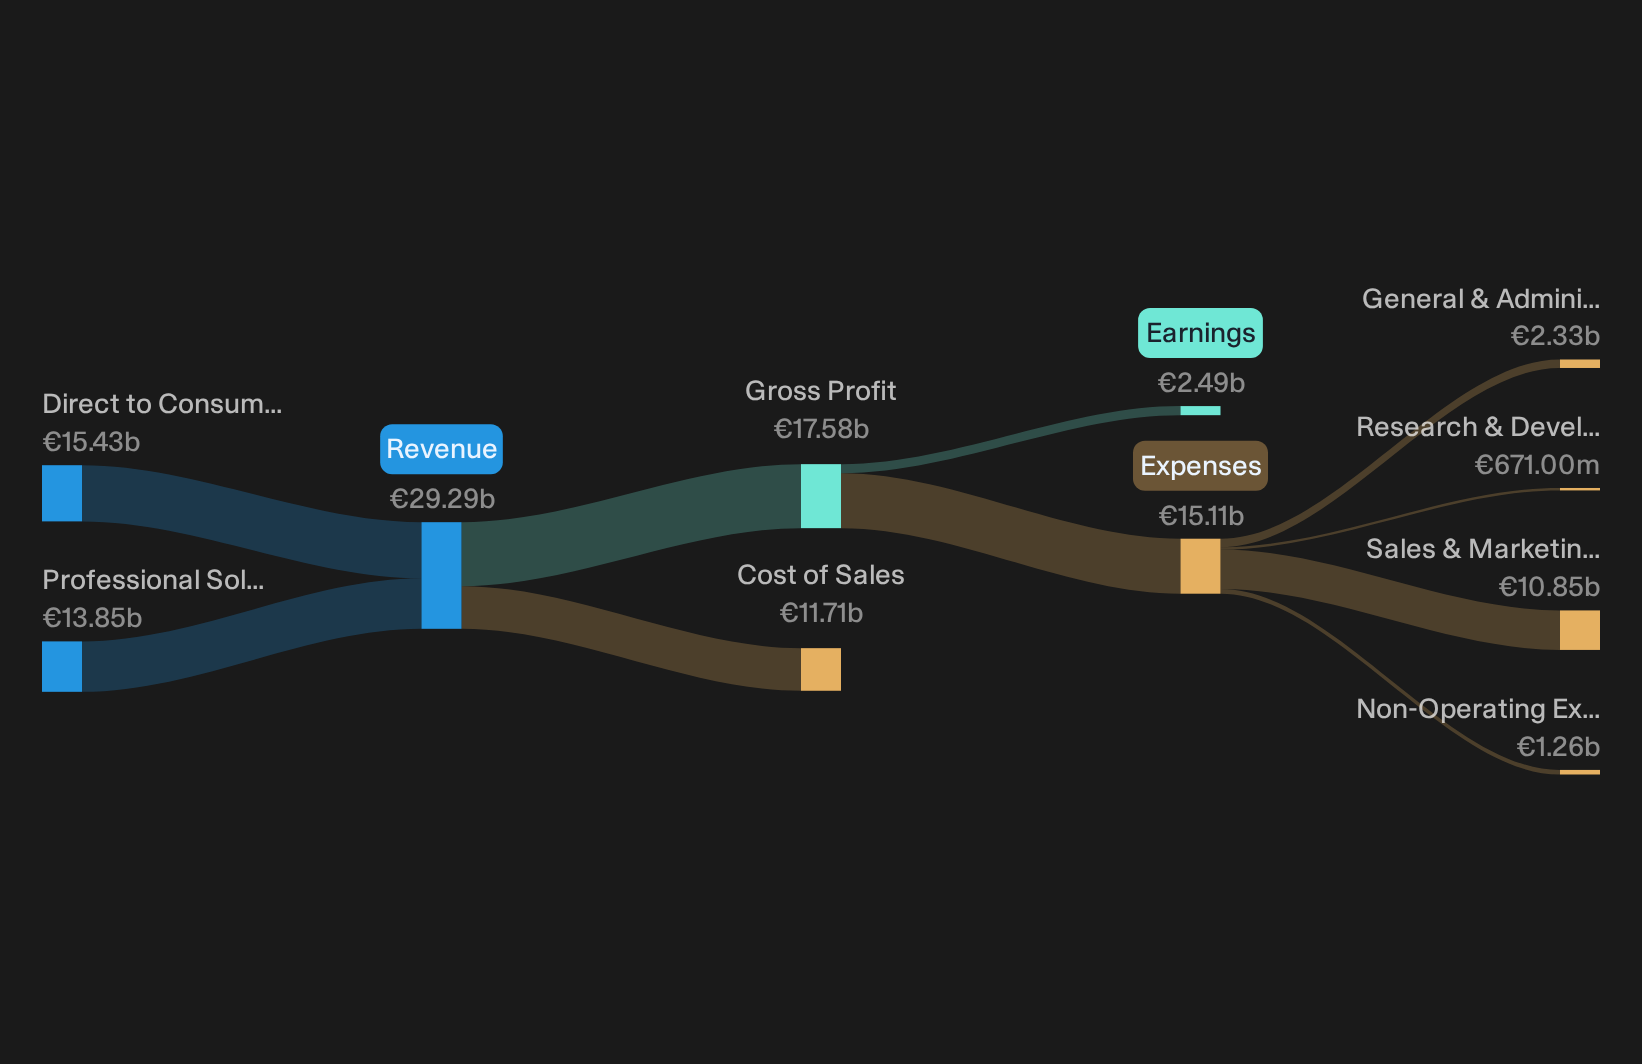
Operations: EssilorLuxottica Société anonyme generates €15.4b from Direct to Consumer and €13.9b from Professional Solutions, combining retail reach with wholesale partnerships across global eyewear and vision care.
Market Cap: €83.3b
For a theme built around large, established eyewear and vision care leaders, EssilorLuxottica Société anonyme is the integrated giant that connects lenses, frames, retail, and emerging tech like smart glasses in a single, sector wide platform.
"Although EssilorLuxottica is expanding into eye surgery centers and oculomics based diagnostics within its retail network, the added clinical oversight, staffing, and regulatory requirements could push fixed costs higher and dilute operating margins if procedure volumes or pricing do not ramp as planned."
What matters now is how this quiet shift in mix and complexity feeds through to the margin profile investors are counting on.
That margin question is exactly what makes reading the full narrative for EssilorLuxottica Société anonyme so useful, as it weighs cost creep against EssilorLuxottica Société anonyme's broader earnings story.
Bausch + Lomb (BLCO)
Overview: Bausch + Lomb develops prescription and consumer eye health products, including contact lenses, eye drops, pharmaceuticals, and surgical devices used worldwide.
Operations: Bausch + Lomb generates about $3.0b from Vision Care, $1.4b from Pharmaceuticals, and $948 million from Surgical products and equipment.
Market Cap: $6.2b
Bausch + Lomb fits this Global Eyewear & Vision Care Leaders theme as a pure eye health specialist, tightly linked to prescription demand and long term medical needs rather than fashion cycles or short lived gadget trends.
"Rising global prevalence of dry eye and greater diagnosis in both primary care and specialist settings support sustained prescription growth for Miebo, Xiidra and future combination therapies, underpinning double digit revenue expansion and higher earnings from the Pharma segment."
What really moves the needle for investors is how one quiet shift in product mix could reshape both margin profile and long term earnings power.
That mix shift is already in motion, and the full narrative for Bausch + Lomb shows how Miebo and Xiidra could accelerate or stall Bausch + Lomb's earnings story.

National Vision Holdings (EYE)
Overview: National Vision Holdings is a U.S. optical retailer that sells prescription glasses, contact lenses, and eye exams through value focused chains.
Operations: National Vision Holdings generates about $2.0b from Owned & Host stores, with minimal contribution from corporate and deferred revenue items.
Market Cap: $1.5b
National Vision Holdings plugs cleanly into this theme as the U.S. storefront layer of the eyewear chain. It is where insured and value oriented customers decide how often to get exams, upgrade lenses, and spend on frames.
"Expansion of managed care customer base and broader vision insurance adoption is accelerating, as evidenced by the double-digit managed care comp growth and ongoing initiatives to capture more insured customers."
The real swing factor is how one quiet shift in who pays the bill ultimately reshapes pricing power, margins, and store productivity.
That shift in who pays is exactly what the full narrative for National Vision Holdings unpacks, revealing how managed care growth could accelerate National Vision Holdings' earnings power and store efficiency.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. By the time every headline catches on, early entry points can be gone. Scan curated shortlists while it matters, still under the radar. Consider acting while these opportunities remain less widely followed.
- Spot quietly building momentum and track 193 high quality undervalued stocks that pair healthy balance sheets with cash generation before they are widely caught on screens.
- Explore the infrastructure backbone of the AI boom by scanning 55 AI infrastructure stocks that are positioned to support data, power, and chip demand worldwide.
- Prepare for potential electrification bottlenecks by reviewing 16 top copper producer stocks that supply critical metal for grids, EVs, and industrial upgrades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com