


3 Founder Run Stocks With Revenue Growth Up To 27%
The Federal Reserve is widely expected to hold interest rates steady again in October, which keeps money tight and puts pressure on companies that are only managed quarter to quarter. Founder-led businesses can sometimes respond differently when the person who built the company still sets the tone and owns a large stake. This article highlights three founder-run stocks from our screener that show how that long-term mindset can matter for investors today.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses where leadership is deeply invested in long term outcomes. However, if you want the names that matter most, these 30 top founder-led companies are the strongest companies we've found.
Braze (BRZE)
Braze is a founder-led customer engagement specialist, built around CEO Bill Magnuson’s long-term product vision rather than short-term quarterly targets. The business sells a single, unified platform that helps brands run personalised messaging across channels. This makes it a clear fit for this screener’s focus on owner-operators.
Braze generates about US$834 million from its customer engagement platform and has a market value of roughly US$5.2b. This puts it firmly in mid-cap territory among software peers while still tightly linked to its founding leadership.
Braze shows how a founder still in the driver’s seat can shape an AI-first product roadmap that larger platforms now want to plug into.
"Braze's acquisition of OfferFit is expected to enhance AI-driven optimization capabilities and lead to revenue growth through deal size expansion and differentiation in the market."
What really matters from here is how one quiet assumption around future profitability and capital discipline holds up as those AI ambitions scale.
That quiet assumption is exactly what the full narrative for Braze unpacks, separating hype from the areas where Braze’s AI push could genuinely accelerate or quietly stall.

Spotify Technology (SPOT)
Spotify Technology is a founder-led audio streaming platform where Daniel Ek still actively shapes how listeners experience music, podcasts, and audiobooks. This lines up closely with this screener’s focus on leaders building long-term legacies rather than simply managing quarterly results.
Spotify runs a dual model of paid subscriptions and advertising, with Premium bringing in about €16.9b and Ad-Supported contributing roughly €1.9b, and the business carries a market value of about US$120.1b.
Spotify Technology shows how a founder still closely involved in product decisions can try to use better discovery, pricing, and new formats to squeeze more value out of an already large listener base instead of just chasing raw user numbers.
"Ongoing advances in AI driven personalization, including the Large Taste Model that is already lifting metrics such as autoplay saves, podcast discovery and DJ engagement, point to a product that could further improve user retention and support higher net margins as listening intensity increases."
The real test is how one quiet shift in how the business prices and packages those richer experiences eventually feeds through to long-run profitability.
When that pricing shift starts to bite, the full narrative for Spotify Technology shows how Spotify Technology’s AI, format mix and cost base could be quietly accelerating the story from here.

Super Micro Computer (SMCI)
Super Micro Computer is a founder-led hardware specialist where Charles Liang still guides how its modular servers, AI racks, and data center products are designed and shipped, which is exactly the kind of long term, personally committed leadership this screener is hunting for.
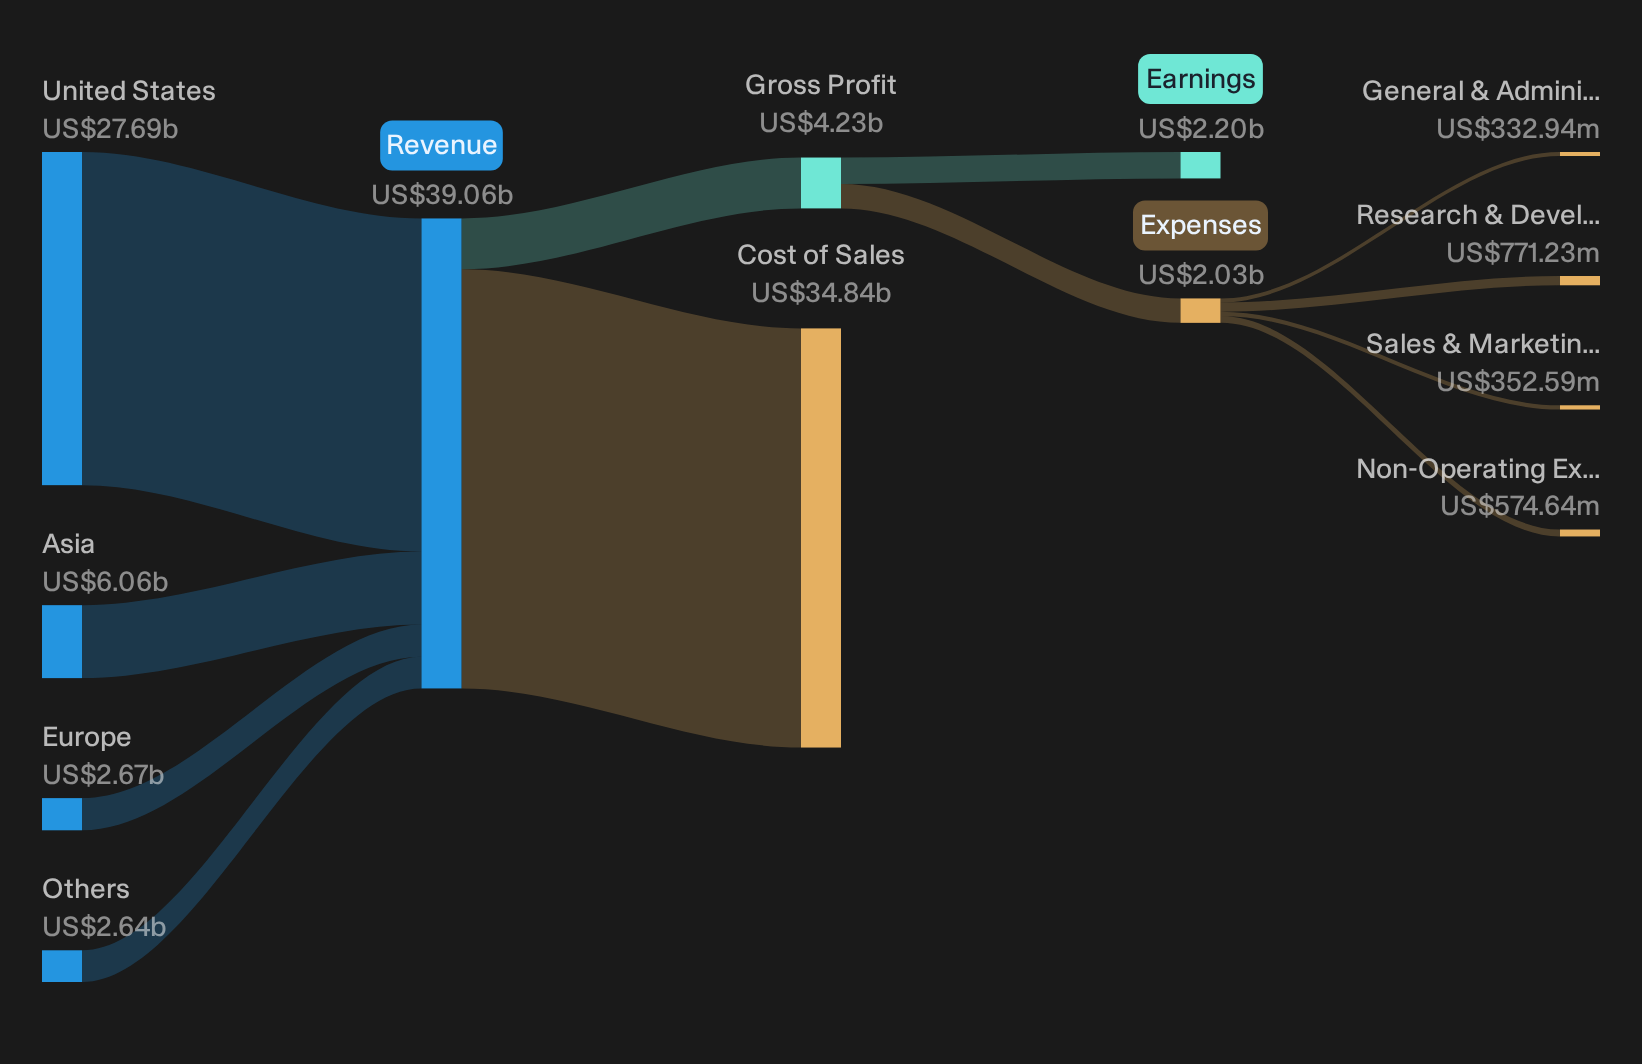
Super Micro Computer develops high performance server and storage solutions under a single broad segment that generated about US$39.1b, and the business carries a market value near US$21.6b.
For founder-led investors, Super Micro Computer is a way to back a builder who is still deeply involved in how AI infrastructure is engineered and sold, rather than a hired executive chasing the next quarter.
"The company's launch and rapid expansion of its Data Center Building Block Solution allows customers to deploy turnkey, energy efficient and customized AI data centers faster than traditional solutions."
What ultimately matters is how one quiet shift in the mix of higher value solutions versus lower margin hardware shapes the earnings power tied to that founder vision.
If that shift in mix is what you care about, the full narrative for Super Micro Computer shows where Super Micro Computer’s earnings power could be quietly accelerating or stalling next.
Seeking Fresh Alternatives Before They Fly
New themes are breaking out while older stories lose momentum. Get a look at fresh ideas that are under the radar for now, before the crowd catches up, and consider them while they still may offer distinct characteristics.
- Target cash-generative value plays with strong balance sheets before sentiment changes by screening a curated 29 high quality undervalued stocks that still look mispriced while it matters.
- Seek potential compounding income streams while yields remain elevated by focusing on a hand-picked group of 5 dividend fortresses built to keep paying.
- Position for possible AI-related developments by reviewing 55 AI infrastructure stocks that could benefit if spending on chips, servers and data centers continues to grow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com