


Sherwin Williams (SHW) Stock Could Still Be A Bargain Despite Its 47% Run
Sherwin-Williams has delivered a 46.7% share price gain over the past three years, which puts a lot of weight on whether its underlying cash flows really support where the stock trades today. With the paint maker now around US$337 per share, the key issue is how that price lines up against the cash the business is expected to generate for shareholders.
- The 46.7% three year return raises the stakes for anyone asking if Sherwin-Williams' recent share performance is fully backed by its future cash generation.
- Sherwin-Williams relies heavily on turning its established coatings franchise into steady cash inflows, so assumptions about how efficiently it converts sales into free cash can significantly influence any intrinsic value estimate.
- If you'd rather focus on earnings, this one's for you. See why Sherwin-Williams's 30.3x P/E tells a different valuation story.
The stock's next move may depend on whether the current US$337.06 price can be squared with the intrinsic value suggested by its projected cash flows.
You can pressure test the cash flow story of Sherwin-Williams against a broader set of opportunities by scanning 29 high quality undervalued stocks.
Does Sherwin-Williams Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model used here projects what Sherwin-Williams might return to shareholders in actual cash over time, then discounts it back to today. On the latest numbers, the business produced about $3.0b of free cash flow over the past twelve months, which already reflects a sizeable cash engine behind the US$337.06 share price.
The forecast set assumes that Sherwin-Williams keeps growing free cash flow from this $3.0b base, with analysts expecting it to move toward roughly $3.8b by 2029 and then continue increasing at more modest rates in the following years. That profile looks more like a mature compounder than a turnaround, which can matter when judging how much risk is priced in at US$337.06. The DCF output points to an estimated intrinsic value that is meaningfully above the current share price, so the model suggests the market is not fully reflecting the projected cash generation. Find out what Sherwin-Williams could be worth using our Discounted Cash Flow (DCF) estimate.
The Sherwin-Williams Narrative: What Would Justify Today's Price?
Narratives on Sherwin-Williams sit between the DCF puzzle and your own view of the future, spelling out which combinations of growth, margins and earnings would need to occur for the stock to be worth materially more or less than today's price on Simply Wall St's Community page. Each narrative ties a specific fair value to a clear story about Sherwin-Williams' potential catalysts and key risks, so you can track over time which version of events appears to be taking shape.
One of the top community narratives on Sherwin-Williams: roughly fairly valued
"The numbers imply the current Sherwin-Williams share price already reflects a fair valuation that incorporates mid to high single digit sales growth..."
Discover why this Narrative puts Sherwin-Williams at roughly fairly valued.
One more Sherwin-Williams check that sits outside the cash flow math
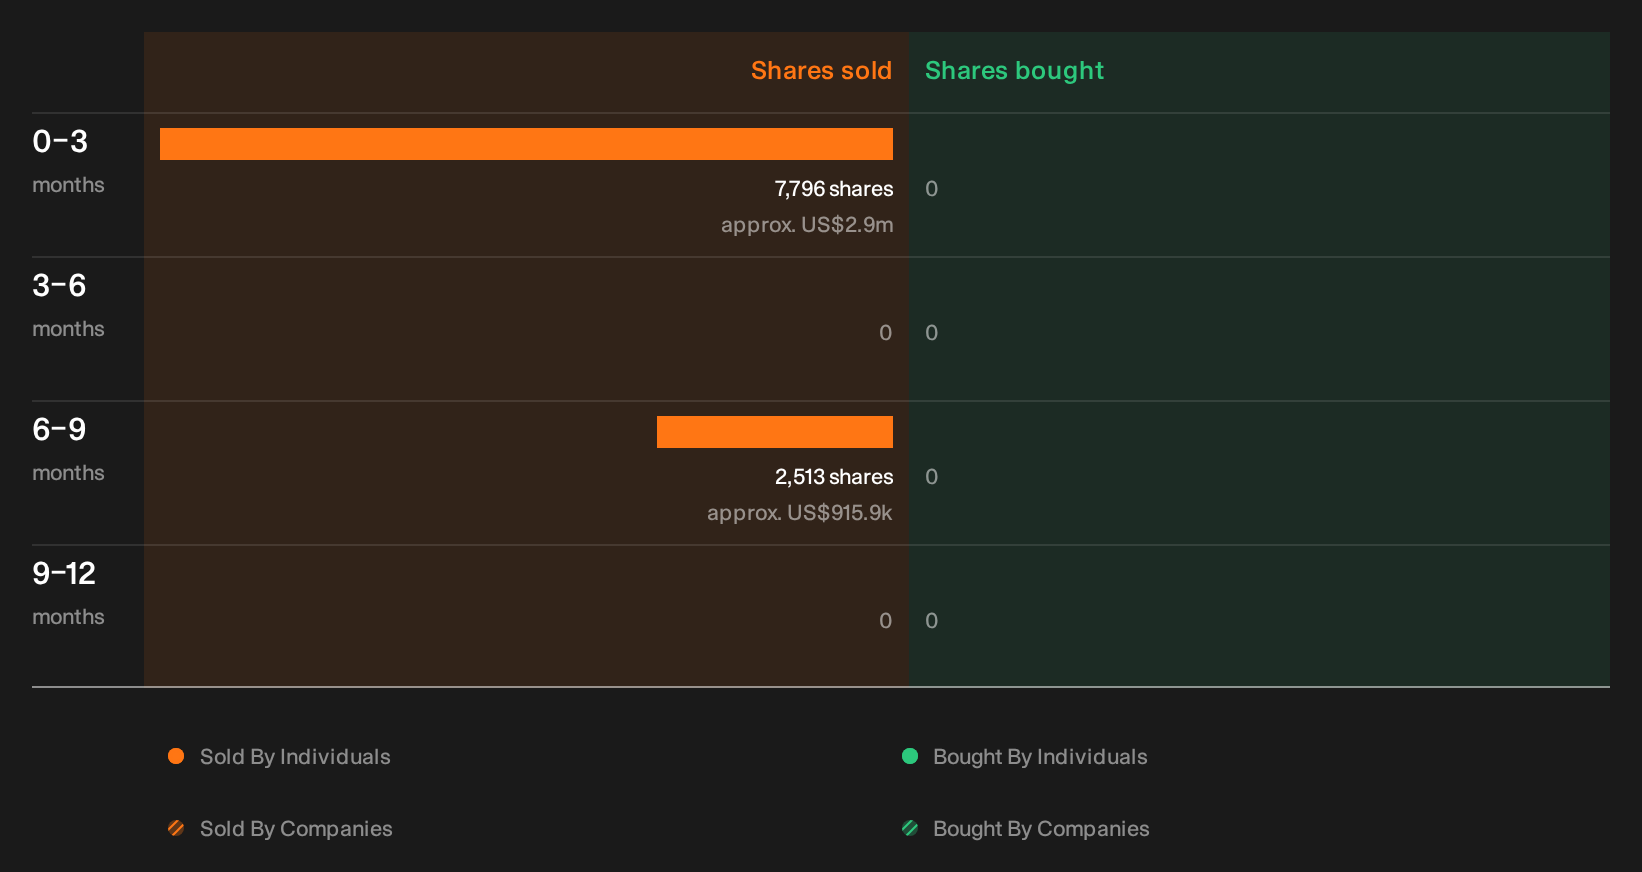
Price and projected cash are only part of the picture, because recent transactions by Sherwin-Williams insiders can send their own quiet signal about expectations. See the recent insider selling flagged for Sherwin-Williams.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com