


Earnings Beat Might Change The Case For Investing In RTX Stock (RTX)
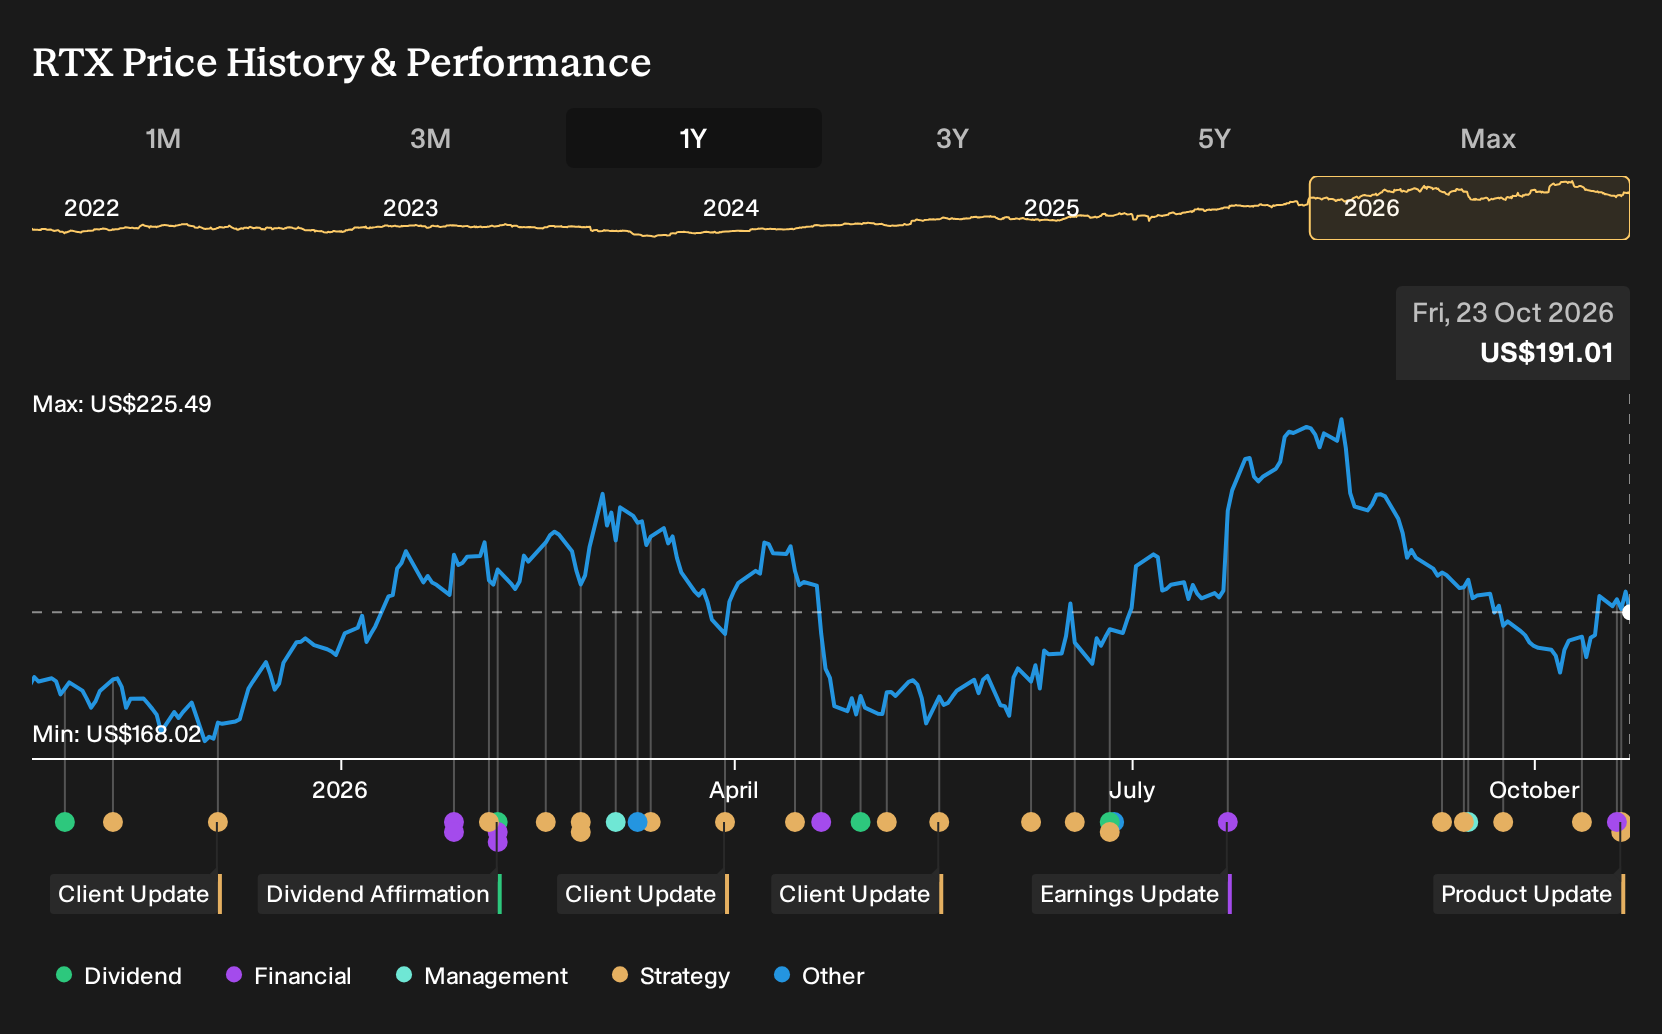
- RTX reported third quarter 2026 results with revenue of US$24,965 million and net income of US$2,583 million, raised full year guidance, and highlighted a record backlog supported by long term defense awards, including Tomahawk and AMRAAM production contracts.
- Fresh U.S. government work for Raytheon radars and Javelin launchers, together with Collins Aerospace’s new ARINCDirect OpenAPI and planned radio altimeter upgrades, points to RTX deepening its role in both defense programs and higher value recurring aviation services.
- The next area of attention is how RTX’s stronger earnings print and record contracted backlog could reshape the existing investment narrative.
RTX Investment Narrative Recap
To own RTX, you need to be comfortable with a defense and aerospace group that leans heavily on long term government programs and high margin aftermarket services. The short term swing factor is how quickly RTX can turn a record backlog into deliveries and cash without eroding margins through overtime, expedited freight or pricing pressure.
The main risk right now is execution against those tight production and supply chain constraints while funding around US$10b of annual capex and engineering. The latest earnings beat and guidance raise point to solid progress on that front, but they do not eliminate exposure to tariffs, shifting defense budgets or potential cost overruns.
The Collins Aerospace ARINCDirect OpenAPI launch ties directly into that execution story. RTX is pushing deeper into connected aviation services where data integration, flight support and digital tools can create higher value, recurring revenue streams that complement traditional hardware sales and could support more predictable cash generation if adopted at scale.
For you as an investor, the interesting link is between this type of software like service capability and RTX effort to grow commercial aftermarket activity. ARINCDirect OpenAPI can reinforce Collins’ role inside customers’ daily workflows, yet it still carries the usual risks around integration complexity, customer adoption speed and the need to keep investing in software and infrastructure to maintain reliability and security.
RTX's current analyst storyline points to revenues of US$113.0b and earnings of US$10.9b by 2029, based on a projected 6.5% annual revenue growth rate and an earnings increase of about US$3.2b from US$7.7b today.
Uncover why RTX's fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
RTX attracts only 2 fair value estimates from the Simply Wall St Community, yet they cluster tightly between US$224.72 and US$228.83. That narrow band contrasts with real execution risks around tariffs, government budgets and heavy capex. Use that gap between community optimism and these constraints to explore sharply different viewpoints.
Explore another RTX fair value estimate, including one that suggests as much as 20% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your RTX research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for RTX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RTX's overall financial health at a glance.
Looking for more investment ideas beyond RTX?
Once you have an initial view on RTX, it can help to widen the lens and see how other businesses stack up on value, balance sheet strength and income potential using the Simply Wall St Screener.
- If you want potential mispricing with quality fundamentals, start with a curated set of 29 high quality undervalued stocks that already screen for both business strength and attractive pricing.
- For investors who care most about resilience, focus on a 30 resilient stocks with low risk scores that filters for companies with more stable risk profiles.
- If balance sheet strength matters most to you, zero in on a list of solid balance sheet and fundamentals (24 results) so you can compare RTX with peers that also keep financial foundations in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com