


Hasbro (HAS) Raised Its Outlook, Is The Upside Already Priced In?
Hasbro (HAS) raised its full-year 2026 earnings outlook after reporting a strong third quarter with higher sales, revenue, and net income than a year earlier, and reaffirmed its quarterly dividend.
The share price reaction has been intense rather than gradual, with a 7 day share price return of 18.91% and a 30 day share price return of 33.32% helping lift Hasbro to US$117.44. The year to date share price return of 41.55% and 1 year total shareholder return of 58.06% point to momentum that has been building over time rather than appearing overnight.
Spot potential follow through by comparing Hasbro's earnings driven move with other consumer names showing fresh strength using the 29 high quality undervalued stocks.The rally and the raised 2026 guidance put Hasbro only slightly below analyst targets, while a much larger modeled intrinsic discount lingers in the background. Is that a genuine margin of safety, or cautious pricing for good reason?
Most Popular Narrative: 4% Overvalued
Hasbro now trades above the most widely followed fair value estimate of $112.62, with the $117.44 close implying investors are paying a premium for the story that analysts have modeled off a 7.53% discount rate.
Rapidly growing cross-platform digital gaming and licensing revenue, exemplified by Wizards of the Coast (notably Magic: The Gathering's 23%+ YoY growth and MONOPOLY GO!), is expanding Hasbro's addressable market and recurring high-margin earnings streams. This is positioning the company to capitalize on the global rise of digital entertainment, which should drive outsized revenue and operating profit growth.
See why 29 investors see Hasbro as 4% overvalued.
Result: Fair Value of $112.62 (OVERVALUED)
Still, heavy dependence on Magic: The Gathering and exposure to tariff and supply chain costs could quickly challenge the current Hasbro optimism.
Find out about the key risks to this Hasbro narrative.
Another View: Hasbro Through The Earnings Multiple Lens
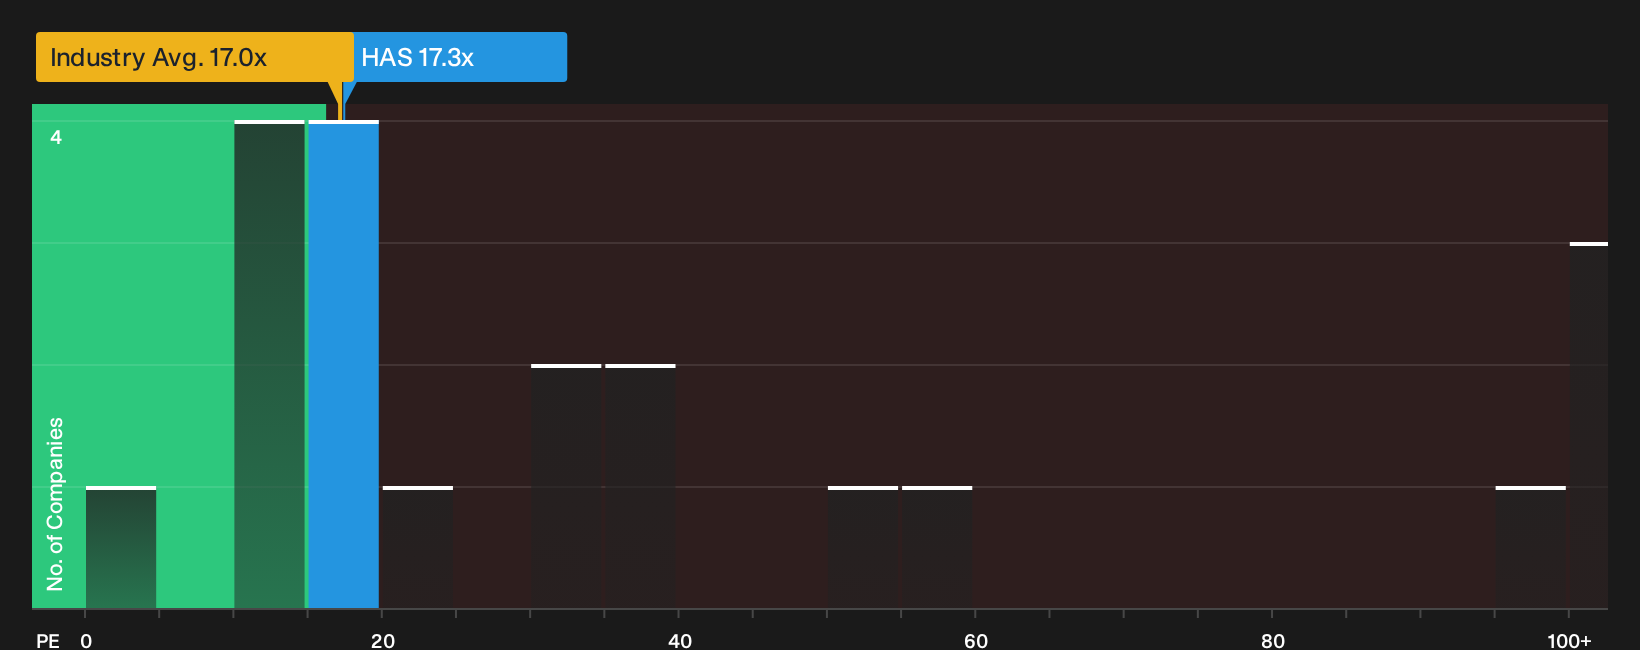
Analyst models paint Hasbro as slightly overvalued versus a US$112.62 fair value, yet the current P/E of 17.3x against a peer average of 21.8x sends a different signal. The ratio also sits a touch above the 16.8x fair ratio. Is that a cushion, or a warning that the multiple could compress toward that fair ratio?
See what the numbers say about this price in more detail with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Be confident that the recent Hasbro optimism really holds up. Act quickly, review both sides of the story, and weigh the 4 key rewards and 2 important warning signs.
Looking for more Hasbro-sized investment ideas?
If Hasbro's latest move has your attention, keep that momentum working for you by using the Simply Wall Street Screener to surface your next potential opportunity.
- Hunt for mispriced quality and let the 29 high quality undervalued stocks guide you toward companies where fundamentals and current pricing look out of sync.
- Prioritize resilience first and use the 30 resilient stocks with low risk scores to focus on businesses with calmer risk profiles when markets feel noisy.
- Target stronger balance sheets and fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) so you are not relying on hope alone.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com