


What Is Putting Baidu (BIDU) Back In The Spotlight?
Baidu (NasdaqGS:BIDU) recently filed a US$2.88b shelf registration for 34,169,519 American Depositary Shares tied to an employee stock ownership plan, giving investors fresh information on potential future equity issuance.
At around US$77.20, Baidu’s share price has fallen 11.6% over the past month and 48.6% year to date, while the 1 year total shareholder return is down 37.1%. This points to fading momentum as investors weigh fresh equity issuance and upcoming earnings against its longer term prospects.
Spot 29 high quality undervalued stocks that, like Baidu, are trading well below analyst targets and may be pricing in more pessimism than their recent business metrics suggest.After a slide like this and a fresh US$2.88b shelf on the table, the real tension is simple. Does it make more sense to lean into Baidu’s current discount, or wait for a cleaner entry on price and dilution risk before moving?
Most Popular Narrative: 61% Undervalued
Baidu’s most followed valuation story pegs fair value around $198.27 per share versus the recent $77.20 close, which frames a wide gap that only really holds if its AI engines deliver what believers expect.
The rapid scaling of Baidu's AI native marketing services, with RMB 2.8b of revenue in Q3 2025 and 262% year over year growth from agents and digital humans used daily by around 33,000 advertisers, points to a separate subscription and performance based engine that can lift Baidu Core revenue and support structurally higher gross margins as this mix grows.
See why 10 investors see Baidu as 61% undervalued.
Result: Fair Value of $198.27 (UNDERVALUED)
Still, recurring class action allegations around Baidu’s AI disclosures and the prior RMB 16.2b impairment on infrastructure both have the potential to reset sentiment quickly.
Find out about the key risks to this Baidu narrative.
Another View: What Baidu’s Sales Multiple Is Telling You
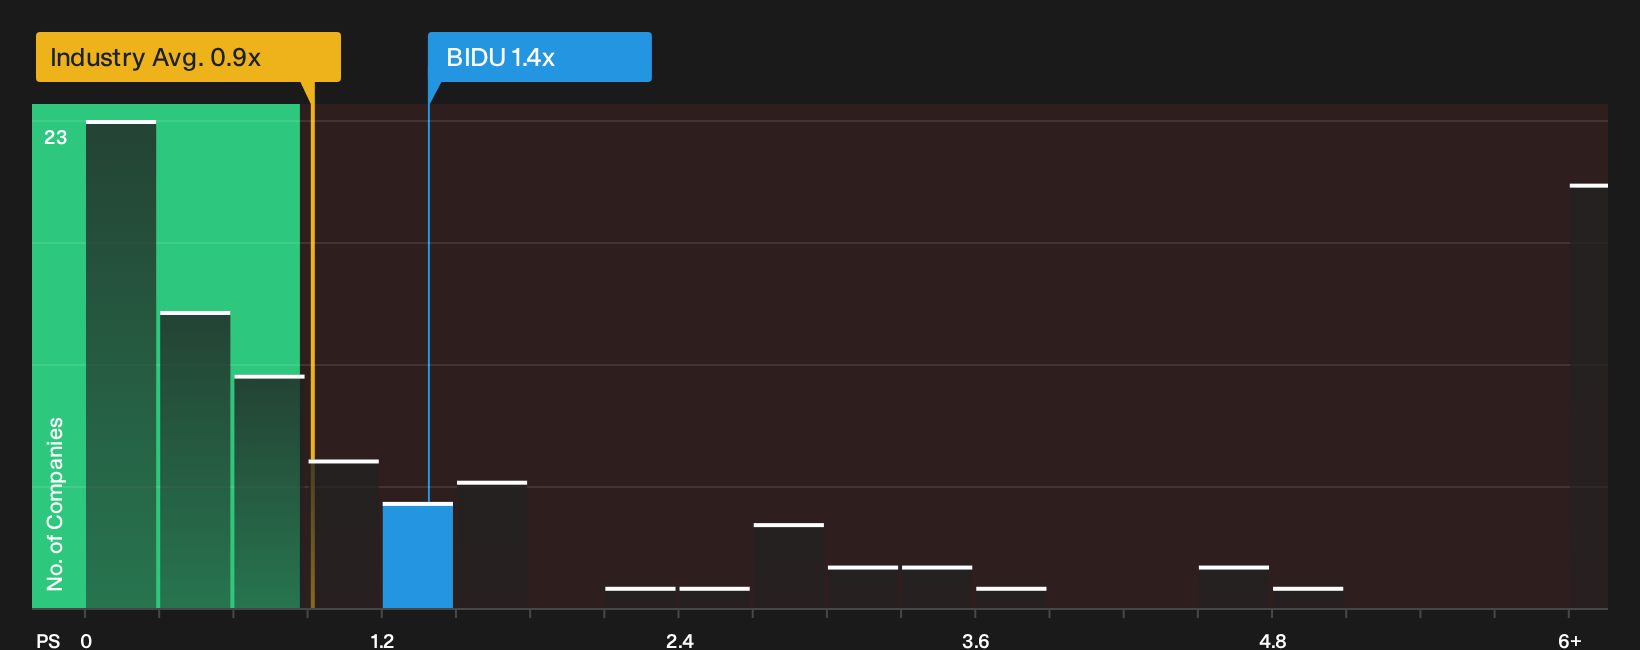
That bullish fair value of $198.27 relies heavily on optimistic earnings forecasts. The everyday trading multiple paints a different picture. Baidu changes hands at roughly 1.4x sales, which is higher than the US Interactive Media and Services group at 0.9x, yet below both peer levels at 4.4x and a fair ratio of 2.2x. For investors, that mix of richer pricing than the sector, cheaper terms than peers, and a gap to the fair ratio raises a simple question: Is this a value setup that needs patience, or a value trap that needs stricter quality filters?
See what the numbers say about this price gap before deciding how much weight to put on each method, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Seen enough debate around Baidu’s valuation for one sitting and feel the mixed sentiment? Act quickly by pulling up the hard numbers, weighing the upside risks alongside the red flags, and stress testing your own thesis against the 2 key rewards.
Want more ideas beyond Baidu?
If Baidu has you rethinking where value really sits, broaden your watchlist now with focused filters that surface opportunities you might otherwise miss.
- Target resilience by reviewing companies with strong finances and clean balance sheets through the list of solid balance sheet and fundamentals (24 results).
- Pursue mispriced potential by scanning for quality businesses trading well below fundamentals using the 21 high quality undiscovered gems.
- Prioritise capital protection by filtering for companies with steadier profiles through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com