


Restar (TSE:3156) Just Gave Investors Something To Think About
Restar (TSE:3156) has drawn attention after its shares closed at ¥5,980, with the semiconductor and electronics distributor showing a mix of shorter-term pullbacks and longer-term gains across recent performance periods.
Recent trading has cooled a little, with Restar’s 7-day share price return down 3.7% and the 30-day share price return down 2.61%. However, the 90-day share price return of 68.93% and 1-year total shareholder return of 135.66% point to momentum that has been strong rather than fading overall.
Scan for other Restar-like opportunities in electronics and semiconductors by checking the hand picked 55 AI infrastructure stocks that could benefit from similar momentum shifts.
Restar trades at what looks like a steep discount to estimated fair value after a powerful 1-year run. Is that gap a genuine opportunity, or is the market simply pricing in real business risk and cyclicality?
Most Popular Narrative: 131% Overvalued
Restar closed at ¥5,980, while the most followed narrative pegs fair value closer to ¥2,588, so the current quote sits well above that reference point and raises sharp questions about how much future strength is already being priced in.
Q1 FY3/27 results update. Trend to remain positive. Registering OP growth of 487% YoY, Q1 FY3/27 results were significantly ahead of expectations, with Restar strongly positioned to benefit from AI-driven data center investment demand and rising prices for key products. Taking these factors into account, the company has revised FY guidance and DPS upward. We believe the earnings outlook remains strong, with continued high order visibility, rather than scenarios where demand is driven by a temporary supply shock or customer pre-buying. We have raised our earnings estimates for FY3/27 and beyond. Setting a high water mark. Near-term visibility robust. Revised guidance for FY3/27 focuses on the Device business unit, which benefited from rising capex for AI-driven data centers, a tightening market, and cross-selling opportunities. Our view is that demand for AI-related semiconductors and associated equipment will continue to provide structural growth. We estimate FY3/27 ROE will reach 16.0%, the highest level achieved to date. Pace moderating but growth profile intact. Our revised estimates reflect flattening earnings into FY3/28 and FY3/29, although earnings should remain at historically elevated levels. Going forward, this will be impacted by measures the company undertakes to develop and scale higher-return activities, such as IT & SIer and Engineering, to improve the sales mix. Valuations. Based on our revised earnings estimates, the shares are trading at an estimated PER FY3/27 of 10.7x (on OP growth of 60.6% YoY), dividend yield of 2.9% (based on DOE of 3.4%), and current PBR of 1.6x. Full report here
See why 1 investors see Restar as 131% overvalued.
Result: Fair Value of ¥2,587.96 (OVERVALUED)
Still, Restar’s story could shift quickly if Device BU demand cools, or if planned M&A and sales mix changes take longer than investors expect.
Find out about the key risks to this Restar narrative.
Another View On Restar’s Valuation
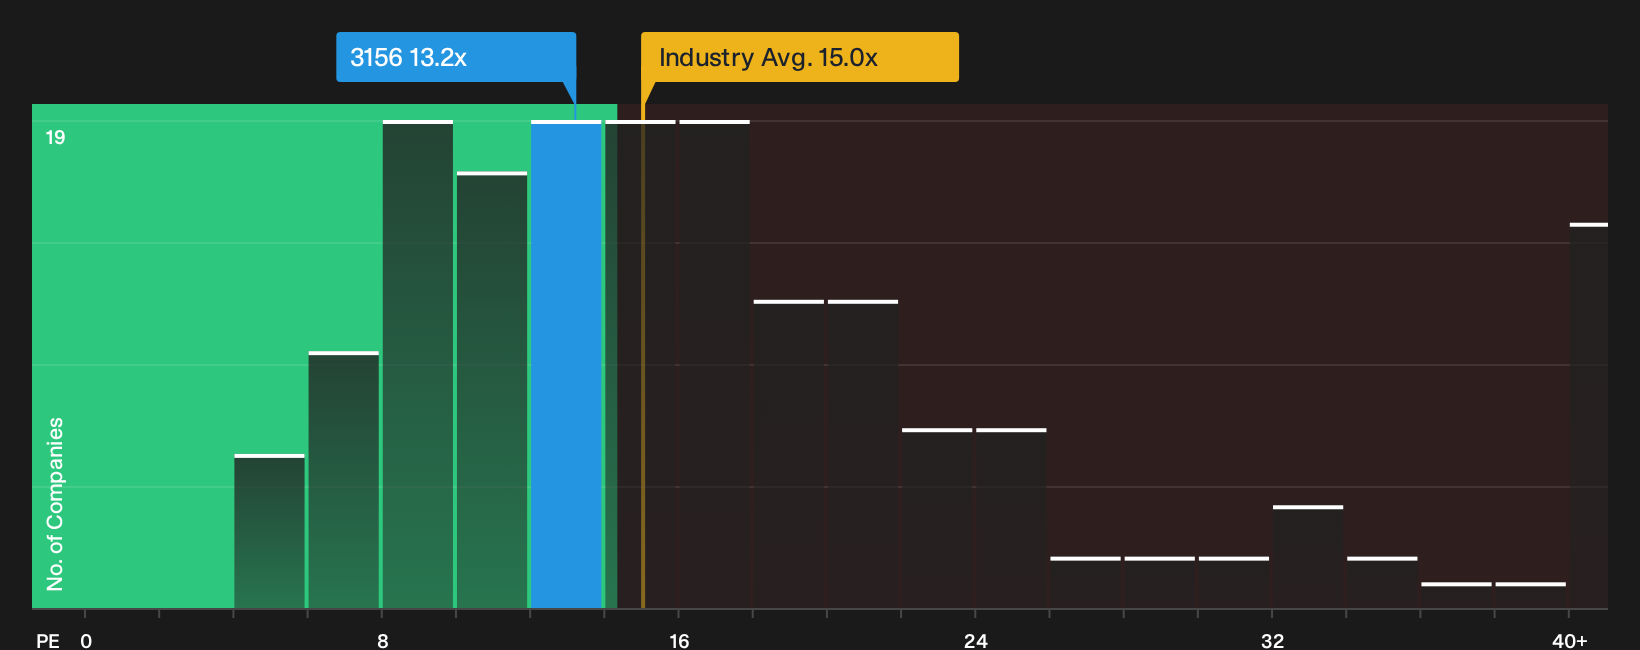
On simple earnings multiples, Restar looks restrained. A P/E of 13.2x sits below the 18.2x fair ratio our model suggests the market could move toward, only slightly above the 12.4x peer average and under the 15x sector level. Is that gap a margin of safety or a warning on quality?
Investors who want to see the numbers behind this valuation lens can go deeper with the See what the numbers say about this price — find out in our valuation breakdown.
For a visual sense of how Restar screens against its sector on this measure, review the
Next Steps
Mixed signals on Restar’s valuation story so far. If you want to move fast and base your view on the underlying data rather than the headlines, take a closer look at the 3 key rewards and 3 important warning signs.
Looking for more Restar-like investment ideas?
If you stop with Restar, you only see one angle. Broaden your watchlist with focused stock ideas that match different risk, income, and quality profiles.
- Target potential mispricing by scanning a 14 high quality undervalued stocks that combines strong fundamentals with prices that may not fully reflect those strengths.
- Strengthen your income stream by reviewing a curated set of 29 dividend fortresses designed for investors who want cash returns as well as capital growth.
- Dial down portfolio stress by filtering for 22 resilient stocks with low risk scores that aim for steadier balance sheets and fewer unpleasant financial surprises.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com