


How Q3 Earnings At Popular (BPOP) Has Changed Its Investment Story
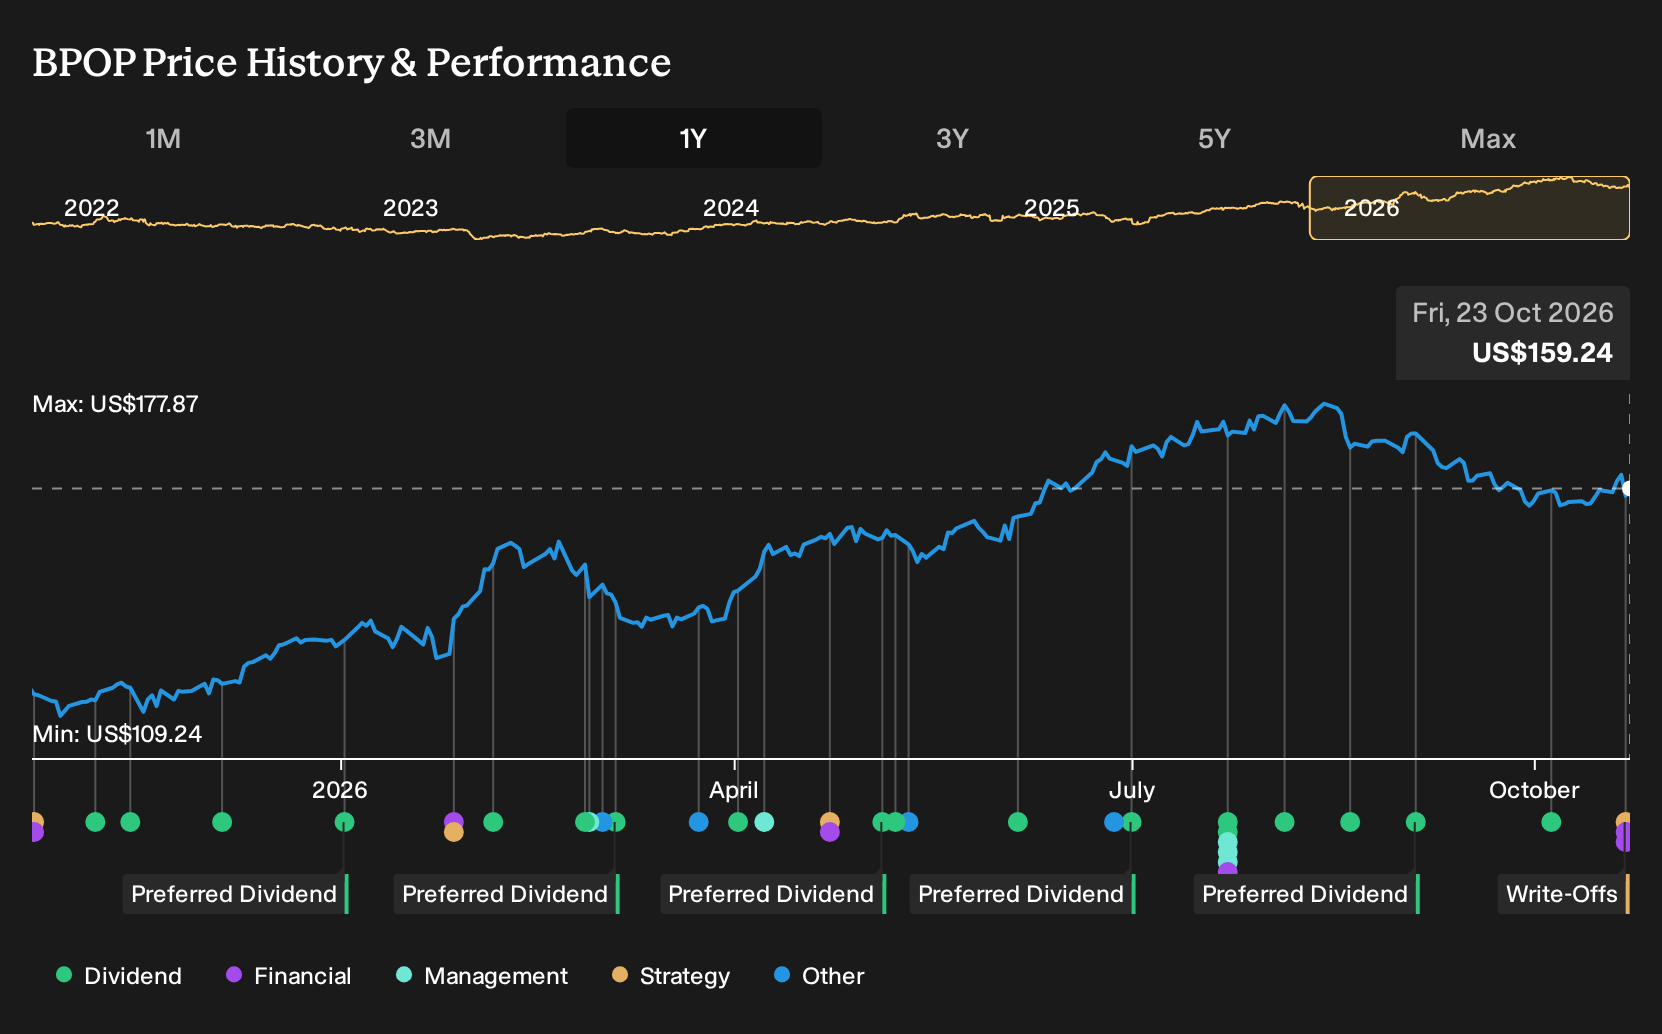
- Popular, Inc. reported Q3 2026 results with net interest income of US$698.93 million and net income of US$266.33 million, alongside a quarterly cash dividend of US$0.90 per share payable in January 2027.
- The bank paired higher earnings and an 8.5% full year 2026 net interest income outlook with higher net charge offs of US$72.94 million, highlighting a trade off between profitability and credit costs.
- Next, the focus shifts to how Popular’s higher earnings, dividend affirmation and credit costs could reshape the existing investment narrative.
Scan beyond Popular’s latest dividend and credit costs, and see how other banks with resilient payouts and balance sheets line up in our hand picked list of solid balance sheet and fundamentals (24 results).
Popular Investment Narrative Recap
To own Popular, you need to be comfortable with a bank that leans heavily on Puerto Rico but is working to grow earnings through higher net interest income, cost efficiency programs and more digital driven fees. The raised 2026 net interest income outlook and strong recent profitability keep that earnings capacity front and center.
The key near term swing factor is whether credit quality stays contained while Popular leans into that higher earning asset base. Net charge offs of US$72.94 million, up from US$57.79 million a year ago, keep credit costs as the biggest current risk. So far, the incremental impact from this update looks manageable, not thesis breaking.
The most relevant fresh data point for this story is the updated full year 2026 guidance that points to roughly 8.5% net interest income growth instead of the earlier 5% to 7% range. That matters more for the operational narrative than the headline dividend because it speaks directly to Popular’s ability to earn through a higher cost of risk.
Higher net interest income, together with ongoing efficiency and AI initiatives that target sizeable expense savings into 2027, gives Popular more room to absorb loan losses if Puerto Rico’s economy weakens or single name issues emerge. For readers tracking catalysts, execution on those technology and cost programs sits right beside credit trends as the main thing to watch.
What Popular’s Long Term Forecasts Are Pricing In
Popular's current analyst narrative points to revenues of US$3.9b and earnings of US$1.1b by 2029, built on an assumed 8.8% yearly revenue growth rate and an earnings increase of about US$132m from US$967.7m today.
Uncover how Popular's fair value indicates a 24% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
Fair value estimates for Popular from 2 Simply Wall St Community members range from about US$196.70 to roughly US$385.05, so private investors are assigning very different long term outcomes. Set that against higher net charge offs, a fresh dividend affirmation and active buybacks, and you can see why opinions diverge. Explore the full spread of views before considering how Popular may align with your own expectations and risk tolerance.
Explore another Popular fair value estimate, including one that suggests as much as 142% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Popular research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Popular. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Popular's overall financial health at a glance.
Looking For More Ideas Beyond Popular?
Once you have formed a view on Popular, it can help to compare it with other opportunities that match different income, value, or risk preferences. The Simply Wall St Screener is a quick way to line up alternatives that fit the kind of portfolio you want to build.
- If steady cash flow is a priority, scan for income opportunities through the 5 dividend fortresses.
- If value is the main focus, line up potential bargains using the 29 high quality undervalued stocks.
- If risk control matters most, filter for sturdier balance sheets and steadier profiles via the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com