


Is Genesis Energy (GEL) Undervalued As Its Unit Price Weakens?
Genesis Energy (GEL) trades near US$14.08 after recent weakness over the past 3 months and year to date, drawing attention to how its midstream operations and value profile currently line up for income focused investors.
Recent trading tells a mixed story for Genesis Energy. The 1 day share price return of 1.29% comes after weaker 7 day and 90 day share price performance, while longer term total shareholder returns over 3 and 5 years remain strongly positive. This points to cooling short term momentum against a still constructive multi year record.
Scan income focused midstream ideas alongside Genesis Energy by comparing it with 5 dividend fortresses that have already attracted investors looking for yields above 5%.
Genesis Energy now trades below recent levels after a weak year to date, so the real fork in the road is simple: Is today’s price good enough, or is waiting for a potentially better entry more appropriate as valuation gets unpacked next?
Discounted Cash Flow: What the SWS Model Implies for Genesis Energy
The SWS DCF model points to a fair value of about $51.18 per unit for Genesis Energy, compared with the recent $14.08 trading price, which implies a large valuation gap based on projected cash flows.
The DCF approach estimates all the partnership's expected future cash flows, then discounts them back into today’s dollars using a rate that reflects risk and the time value of money. That process produces a single fair value figure that can be compared directly with the current market price.
Genesis Energy operates midstream assets with long lived infrastructure, and the DCF framework is often used by investors who focus on cash generation over long periods rather than short term earnings metrics. Given recent profitability, revenue that declined 5.4% over the last year, and sector specific factors, the model result is one lens on what the underlying cash flows might be worth relative to where the units currently trade.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of $51.18 (UNDERVALUED)
Still, revenue that declined 5.4% and relatively modest net income of US$24.6m on US$1.83b of sales could challenge the bullish Genesis Energy valuation narrative.
Find out about the key risks to this Genesis Energy narrative.
Another View: What Genesis Energy’s Market Multiple Signals
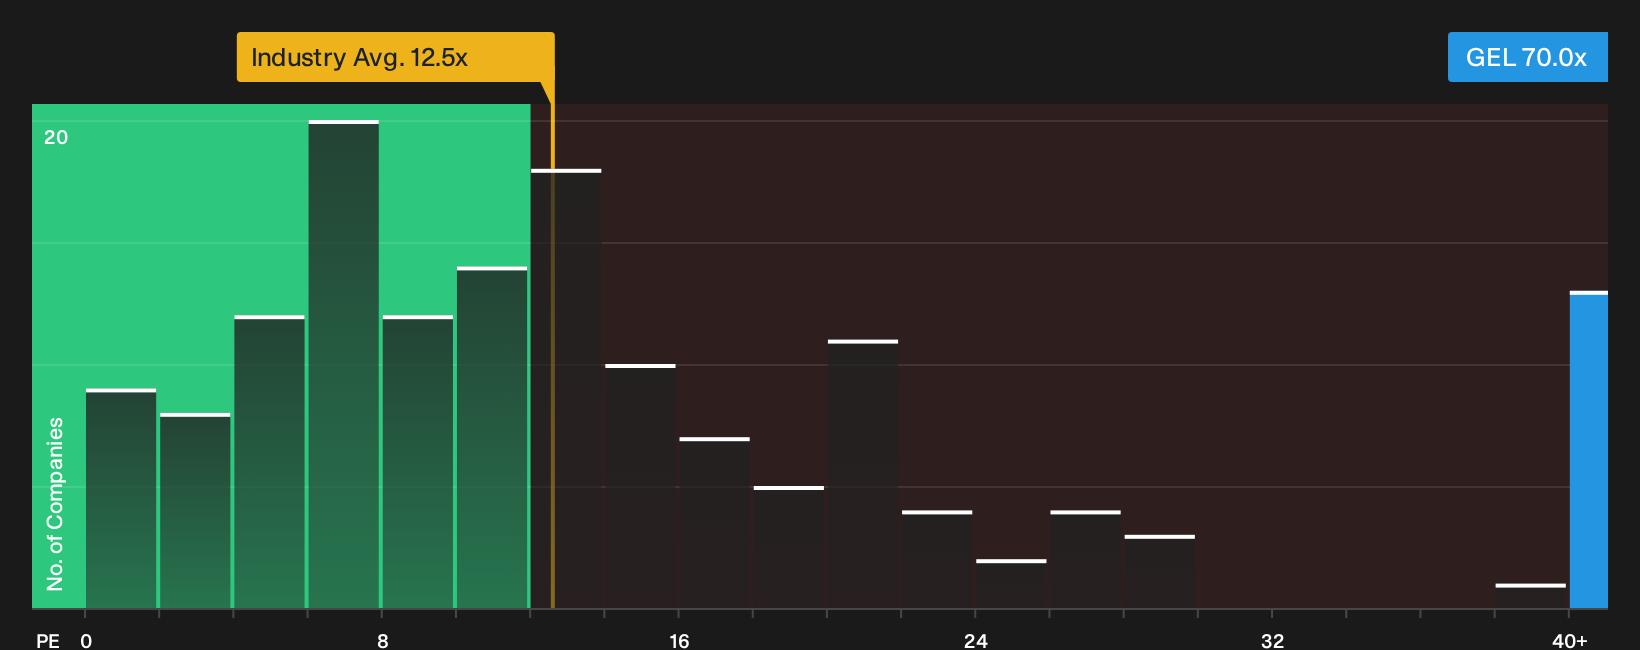
DCF paints a very optimistic picture for Genesis Energy, yet the current P/E ratio of about 70x tells a different story when set against peers on roughly 13x. That kind of premium implies valuation risk if cash flows or growth do not keep pace with expectations.
Investors comparing price tags rather than cash flow models may treat this wide gap as a reason to question which signal matters more for GEL right now: the rich earnings multiple or the discounted unit price relative to fair value estimates.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Genesis Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Genesis Energy is mixed, which is exactly when independent work matters most, so review the full picture of 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Genesis Energy?
Do not stop your research with Genesis Energy alone. Broaden your watchlist with fresh ideas that could fit different roles in your portfolio using the Simply Wall St Screener.
- Target resilience by focusing on businesses with strong financial footing and low risk profiles using the 30 resilient stocks with low risk scores.
- Hunt for mispriced opportunities where quality and valuation intersect by scanning the 29 high quality undervalued stocks.
- Spot potential up and comers with solid fundamentals that have yet to attract heavy attention through the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com