


How Investors May Respond To Interface (TILE) Carpet Tile Launch
- Interface, Inc. recently launched Twist & Texture, a carpet tile collection with seven textile inspired styles, QuickShip availability, and one price point targeted at a range of commercial interiors.
- The combination of modular design, carbon storing materials, and simple specification could influence how frequently Interface products are selected for time sensitive, sustainability focused projects.
- We will look at how Interface's investment narrative intersects with Twist & Texture's QuickShip, single price point model for designers.
Scan how Interface fits into a wider set of sustainability focused flooring and materials players by reviewing a curated group of list of solid balance sheet and fundamentals (24 results) that could support time sensitive, design led projects.
Interface Investment Narrative Recap
To stay on board with Interface, you need to believe the modular flooring model can keep converting design led demand into steady revenue and solid profitability, even as growth expectations rise. The Twist & Texture launch fits that narrative cleanly. It pushes deeper into QuickShip, sustainability focused specifications and mid market price points that tie directly to current project trends.
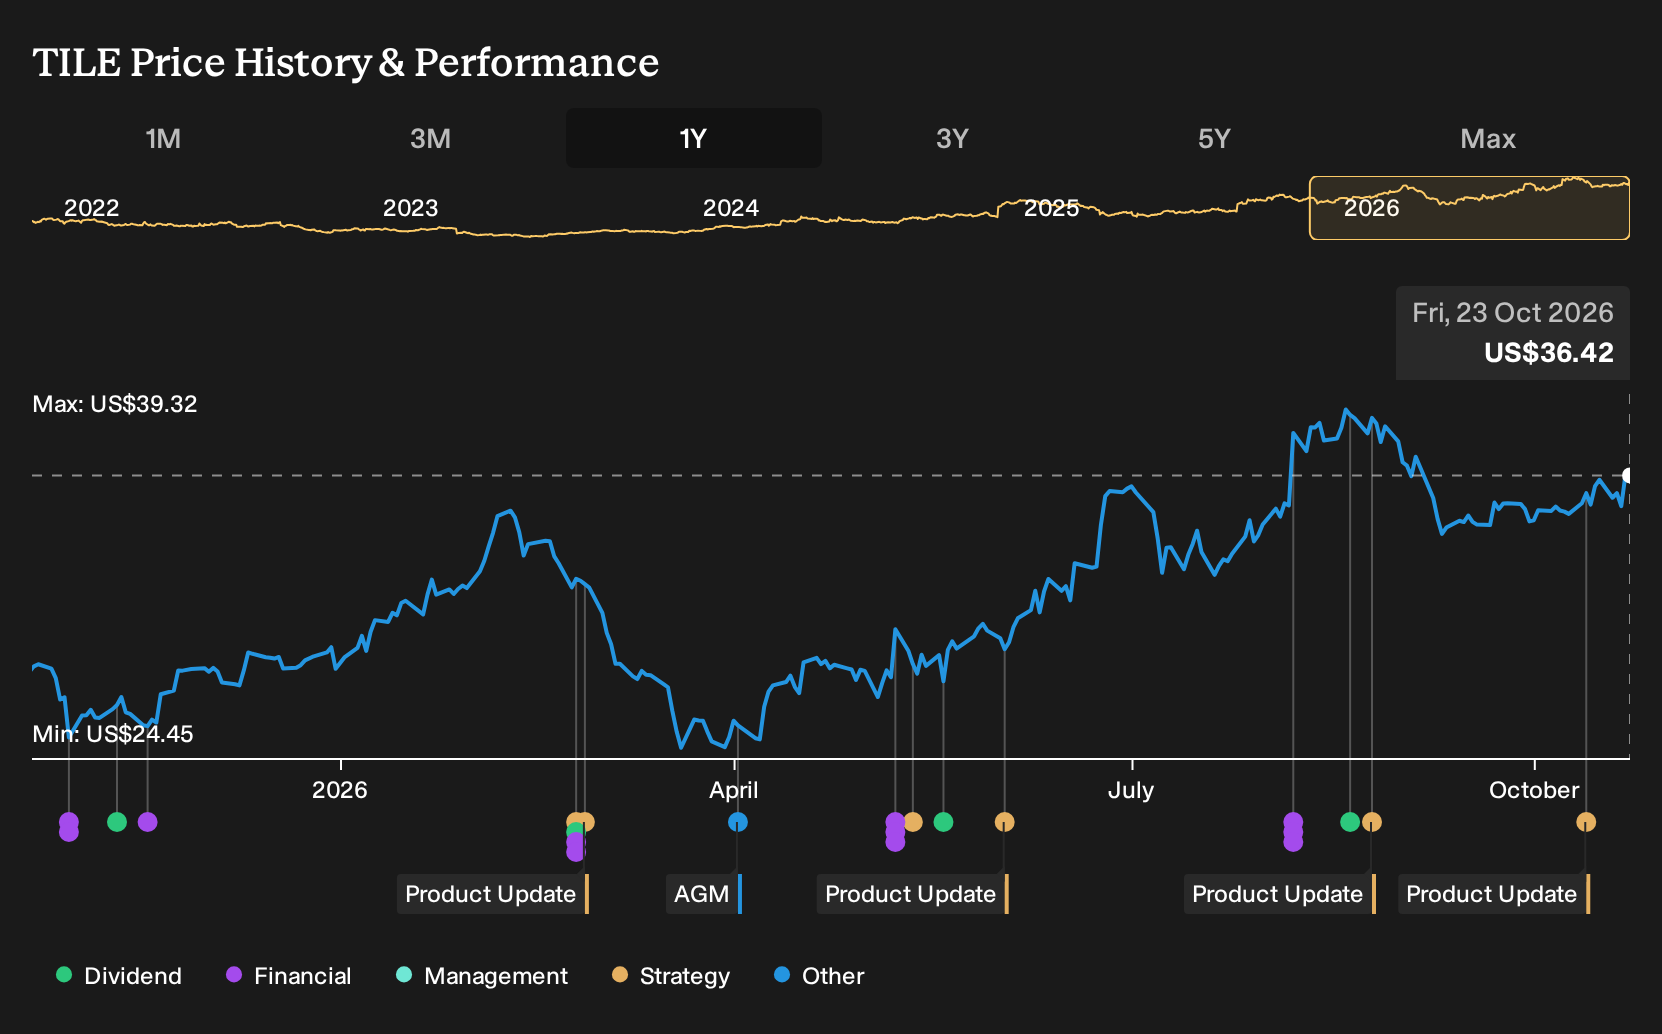
In the near term, the key catalyst is still execution of the One Interface platform and margin work from automation, not this single collection. Twist & Texture can support order flow and mix, but on its own it is unlikely to change the biggest risks, which remain tariff pressure on cost of goods and any reset in expectations after a strong share price run.
Among recent themes, the push into more approachable price points through offerings like Open Air carpet tile and thinner gauge LVT feels closest to the Twist & Texture story. That earlier expansion showed Interface was already working to reach budget sensitive projects without leaning only on premium design.
Twist & Texture sits alongside that effort by pairing a single price point with QuickShip and carbon storing materials. For you as an investor, the link is simple. The more Interface can standardize pricing, shorten lead times and keep sustainability at the center of its portfolio, the more it can test how resilient demand, margins and the One Interface model really are against tariff headwinds and higher expectations baked into the current valuation.
How Twist & Texture Ties Into The Interface Numbers
Interface's narrative projects revenues of US$1.7b and earnings of US$157.1 million by 2029. That path lines up with forecast annual revenue growth of 5.9% and an earnings increase of about US$11.5 million from current earnings of US$145.6 million.
The Twist & Texture rollout lands against that backdrop of analyst expectations. While the flooring launch focuses on QuickShip, a single price band and carbon storing materials, the equity story rests on whether Interface can turn those types of product moves into the 5.9% yearly top line growth analysts already have in their models.
On the profit side, that same forecast set assumes earnings climb from US$145.6 million today to US$157.1 million by 2029 even as margins are modeled to compress from 10.1% to 9.2%. That indicates the consensus is leaning on higher overall sales and share count reduction, not on margin expansion, to lift the bottom line.
Twist & Texture connects to that math through its simplicity pitch. A single price point, a tighter set of styles and QuickShip availability can make specifications easier for design firms that are pressed on both schedule and budget. If that convenience helps Interface win more standard repeat work, it can support the kind of steady volume that underpins the forecast revenue path.
Designers working to hit carbon goals on shorter project cycles may also treat Twist & Texture as a default palette. When a product feels pre approved on sustainability and timing, it often becomes the safe choice on multi site rollouts or program work. For Interface, that type of recurring selection can matter more to the earnings bridge than one off prestige projects.
Nothing in the current analyst framework assumes Twist & Texture alone changes the story. The P/E multiple uplift embedded in the US$45.25 consensus target still leans on broader themes around One Interface execution, automation projects and the full portfolio mix. Yet collections like this provide a practical lens on how those higher level assumptions might show up in actual order books over the next few years.
Uncover why Interface's fair value indicates a 24% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The most optimistic analysts already pictured Interface lifting revenue about 6.8% a year and taking earnings from US$126.7 million to US$163.0 million by 2029. That view leans on renovation heavy demand in offices, healthcare and education. Twist & Texture could reinforce that story or prompt you to rethink it entirely.
Explore 2 other Interface fair value estimates, including one that suggests as much as 32% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your Interface research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Interface. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Interface's overall financial health at a glance.
Looking For More Investment Ideas Beyond Interface?
If Twist & Texture has sharpened your view on Interface, it can be useful to compare that story with other businesses that fit different profiles on quality, income and risk. The Simply Wall St Screener gives you a structured way to scan for companies that match the type of balance sheet strength, valuation profile or dividend stream you want to focus on next.
- If resilience matters most, start with companies screened for financial robustness through a curated 30 resilient stocks with low risk scores that can help you focus on stability first.
- For investors who care about price paid versus fundamentals, filter for potential mispriced opportunities by running through a hand picked 29 high quality undervalued stocks that may warrant a closer look.
- Income focused readers can narrow the field to high yield candidates by reviewing a targeted 5 dividend fortresses that concentrates on stronger payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com