


Altra Fastigheter (OM:ALTRA) Earnings Jump Puts Its Valuation Back In Focus
Altra Fastigheter (OM:ALTRA) just paired a completed share repurchase with fresh third quarter results, combining a 6.2% reduction in share count with sharply higher net income and earnings per share.
Recent trading suggests investors are warming to the story again, with a 7 day share price return of 5.19% and a 30 day gain of 6.07% taking Altra Fastigheter to SEK76.0. However, the 1 year total shareholder return is still down 7.16% after a strong 3 year total shareholder return of 57.31%. This hints that the earnings jump and completed buyback are being viewed as potentially improving the risk and reward balance rather than marking the end of a longer upswing.
See how Altra Fastigheter’s buyback and earnings jump compare with other potential rebound candidates using our curated list of 193 high quality undervalued stocks.
Altra Fastigheter has rallied, yet the share price still sits below both analyst targets and some intrinsic value estimates. Where does fair value really land between SEK76 and those higher implied ranges?
Most Popular Narrative: 12% Undervalued
On the most followed view, Altra Fastigheter is worth SEK86.60 against a last close of SEK76.00, so the current price sits at about a 12% discount to that fair value and leans on a relatively modest 10.42% discount rate to bring future earnings back to today.
Ongoing portfolio rotation of about SEK 5b over 5 years, where lower yielding and resource intensive assets are sold in favour of higher running yields and denser clusters, points to a mix shift that could support cash flow margins and earnings quality. Systematic work to cut energy use and improve EPC ratings across 2026 to 2030 builds on an earlier 10% portfolio energy reduction and can lower operating costs, which may help protect net operating income and net margins.
See why 2 investors see Altra Fastigheter as 12% undervalued.
Result: Fair Value of SEK86.60 (UNDERVALUED)
Still, the story can break if occupancy stalls near 89.2% or if the weaker Finnish portfolio continues to drag on valuations and rental income.
Find out about the key risks to this Altra Fastigheter narrative.
Another View: DCF Puts Altra Fastigheter Closer To Fairly Priced
A second lens tells a cooler story. Our DCF model points to a future cash flow value of SEK71.02 per share, slightly below Altra Fastigheter’s SEK76.00 price today. This suggests the stock is trading a bit above that cash flow based estimate rather than at a clear discount.
If you want to see how this cash flow based view is built line by line, take a look at Look into how the SWS DCF model arrives at its fair value..
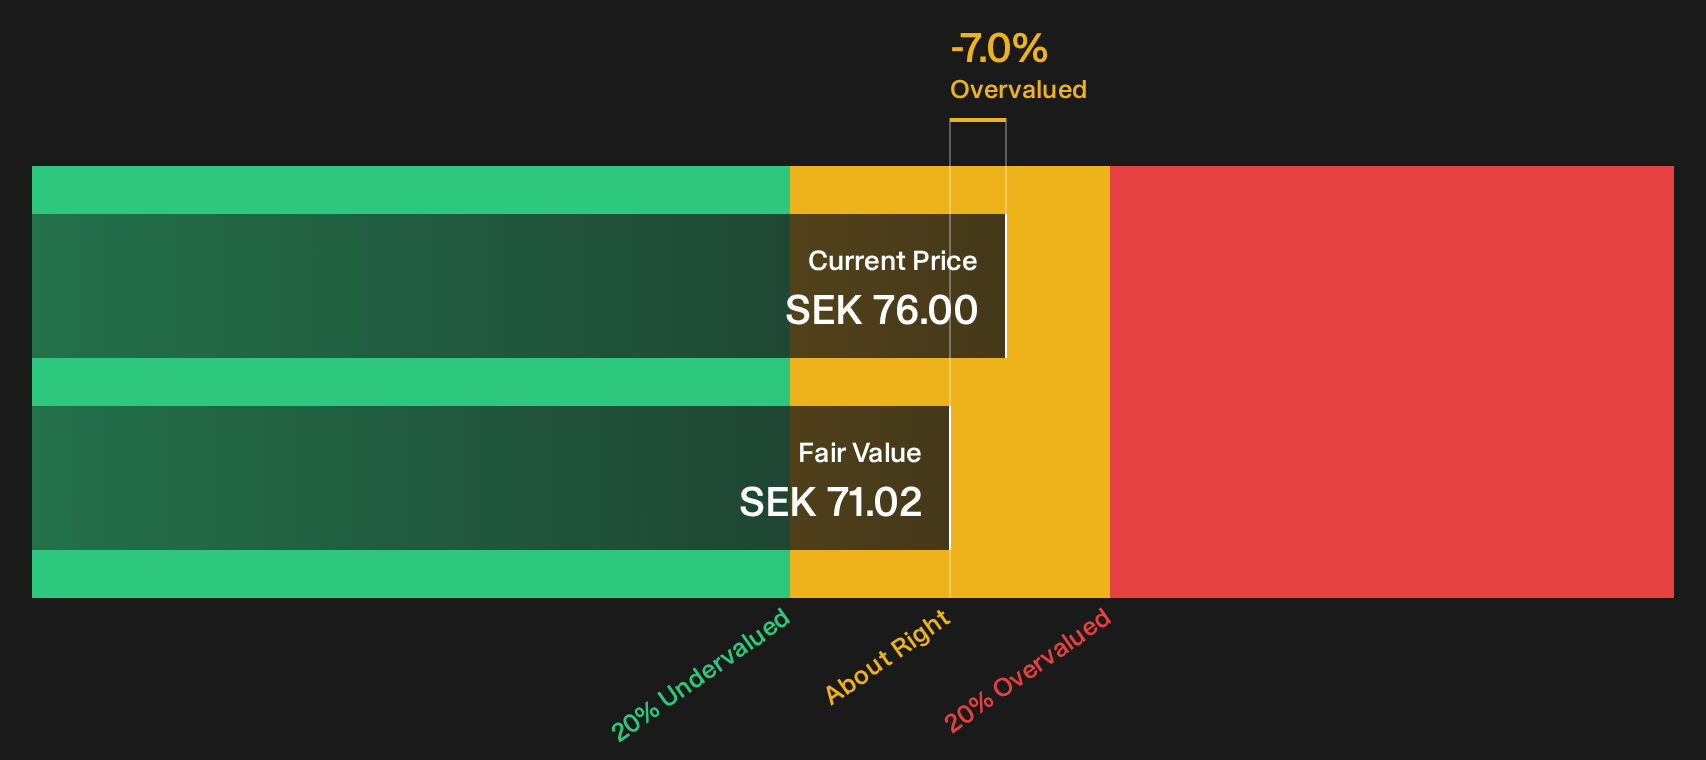
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Altra Fastigheter for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed opinions exist about whether Altra Fastigheter is positioned for a stronger run or simply experiencing a short-term bounce. Act while the information is fresh and weigh both sides of the story by reviewing the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Altra Fastigheter?
If Altra Fastigheter has sharpened your focus, now is the moment to widen your watchlist with a few targeted screeners built for different styles of opportunity.
- Spot potential mispricings early and compare rebound stories by scanning a focused set of 193 high quality undervalued stocks.
- Strengthen your downside protection by filtering for a list of solid balance sheet and fundamentals (205 results) that may better handle shocks and funding pressure.
- Hunt for fresh opportunities before the crowd by running through 613 high quality undiscovered gems that pair quality fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com