


Marqeta (MQ) Expands With Square And Coinbase, Is The Stock Still Undervalued?
Marqeta (MQ) just tied two big threads together in payments. Square is shifting its business credit card onto Marqeta, while Coinbase is teaming up with the issuer for stablecoin-backed spending cards.
Marqeta’s recent partnerships are landing at a time when momentum in the shares is picking up again. The stock’s 30-day share price return of 11.14% and 90-day gain of 7.10% contrast with a flatter year to date move of 1.56%. The 1-year total shareholder return is slightly down 0.16% and the 5-year total shareholder return has fallen 84.6%, which keeps expectations and risk perception in sharp focus around these new deals.
Surf 18 cryptocurrency and blockchain stocks, similar to Marqeta and Coinbase, that are pushing stablecoins and digital payments closer to everyday spending.Marqeta’s recent climb could be interpreting the Coinbase and Square news as evidence of a stronger engine, or it could simply reflect a fresh mood swing around the ticker. The valuation work starts by separating those two stories.
Most Popular Narrative: 9% Undervalued
On the narrative numbers, Marqeta’s fair value of $20.65 sits above the last close at $18.85. This puts pricing slightly behind the story and makes the new Square and Coinbase deals a useful stress test for that gap.
The build out of a unified money movement and digital asset stack that includes ACH, real time payments, wires, push to card, and stablecoin backed card payments positions Marqeta to participate in new payment flows beyond traditional cards and to generate incremental fee and value added services income that can support gross profit growth and operating margin expansion.
See why 13 investors see Marqeta as 9% undervalued.
Result: Fair Value of $20.65 (UNDERVALUED)
Still, the Marqeta story can break if Cash App transitions volumes away faster than expected or if lower margin enterprise deals push take rates down further.
Find out about the key risks to this Marqeta narrative.
Another View: What Marqeta’s Price Says On Sales
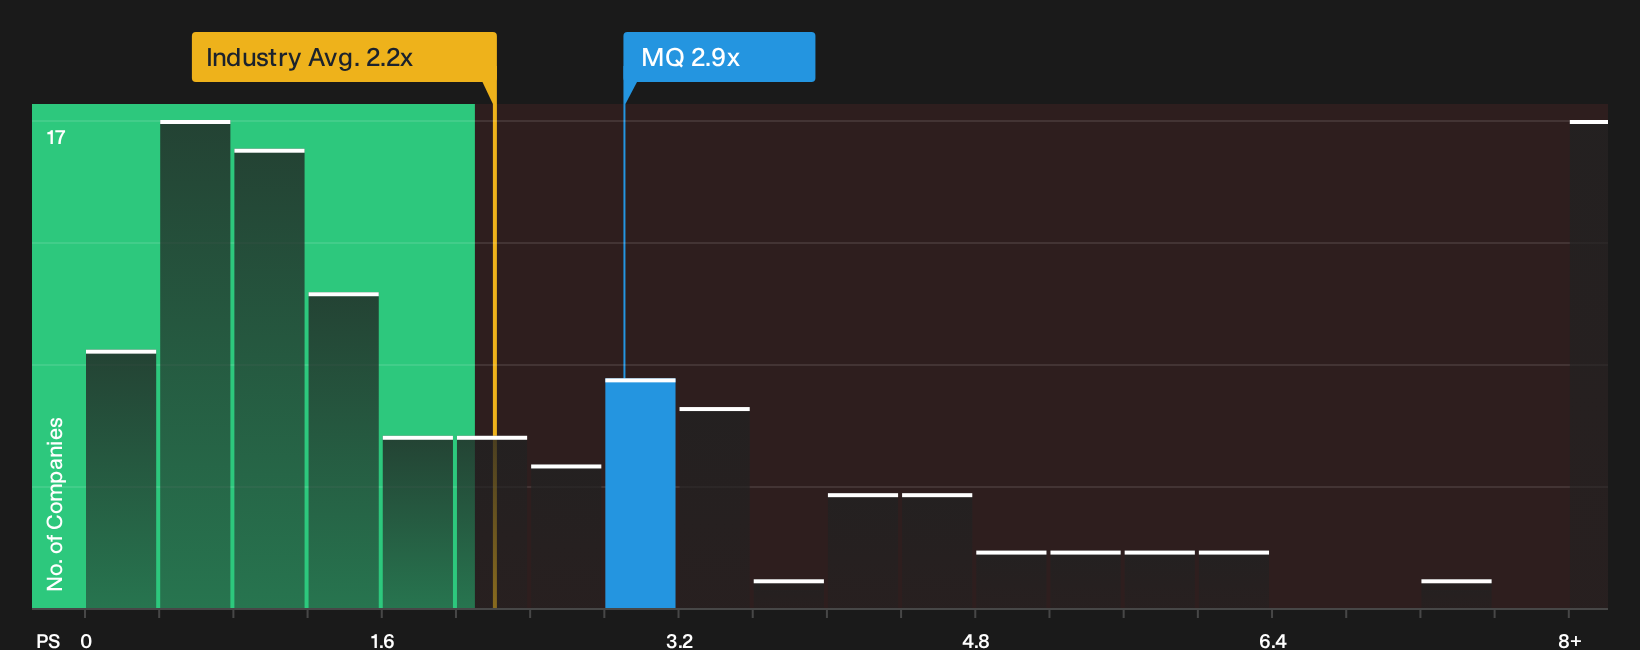
The analyst narrative focuses on future earnings and a fair value of $20.65. On current sales, though, Marqeta trades on a P/S of 2.9x. That is above the US Diversified Financial industry at 2.2x and the 2.1x fair ratio, which points to valuation risk if expectations cool.
For a closer read on what the current P/S gap implies for Marqeta’s upside or downside skew, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the cautious tone here matches your own read on Marqeta’s risk reward trade off? Pressure test the numbers yourself by reviewing the 2 key rewards.
Looking For More Ideas Beyond Marqeta?
Do not stop your research with Marqeta when a wider watchlist could sharpen your decisions across different types of opportunities and risk profiles.
- Chase potential mispricings by scanning a curated pool of quality stocks that screens for both value and financial strength through the 29 high quality undervalued stocks.
- Build a steadier income base by reviewing companies that combine higher yields with robust fundamentals using the 5 dividend fortresses.
- Dial down portfolio stress by focusing on businesses that carry sturdier balance sheets and lower risk scores through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com