


Cactus (WHD) Stock Looks Stretched Against Its Current Earnings
Cactus has delivered a strong share price over the past year, which naturally puts the focus on what investors are paying for its earnings today. With the stock recently closing at US$63.15, the question is how well that market tag lines up with the profits the business is currently generating.
- The share price has climbed 64.0% over the past year. Anyone looking at Cactus now is effectively asking how much of that move is already reflected in its earnings power.
- The business model is closely tied to its ability to convert energy sector activity into consistent profit margins and cash generation. That in turn can support a higher or lower earnings multiple depending on how durable those economics appear.
- The analysts covering Cactus have run their own numbers. See what analysts think Cactus's shares could be worth.
The issue now is whether Cactus's current share price is adequately explained by the level and quality of its earnings.
If you want to test the same earnings question you are asking of Cactus across a wider field, run those filters through the 29 high quality undervalued stocks.
Has Cactus Run Too Far on Earnings?
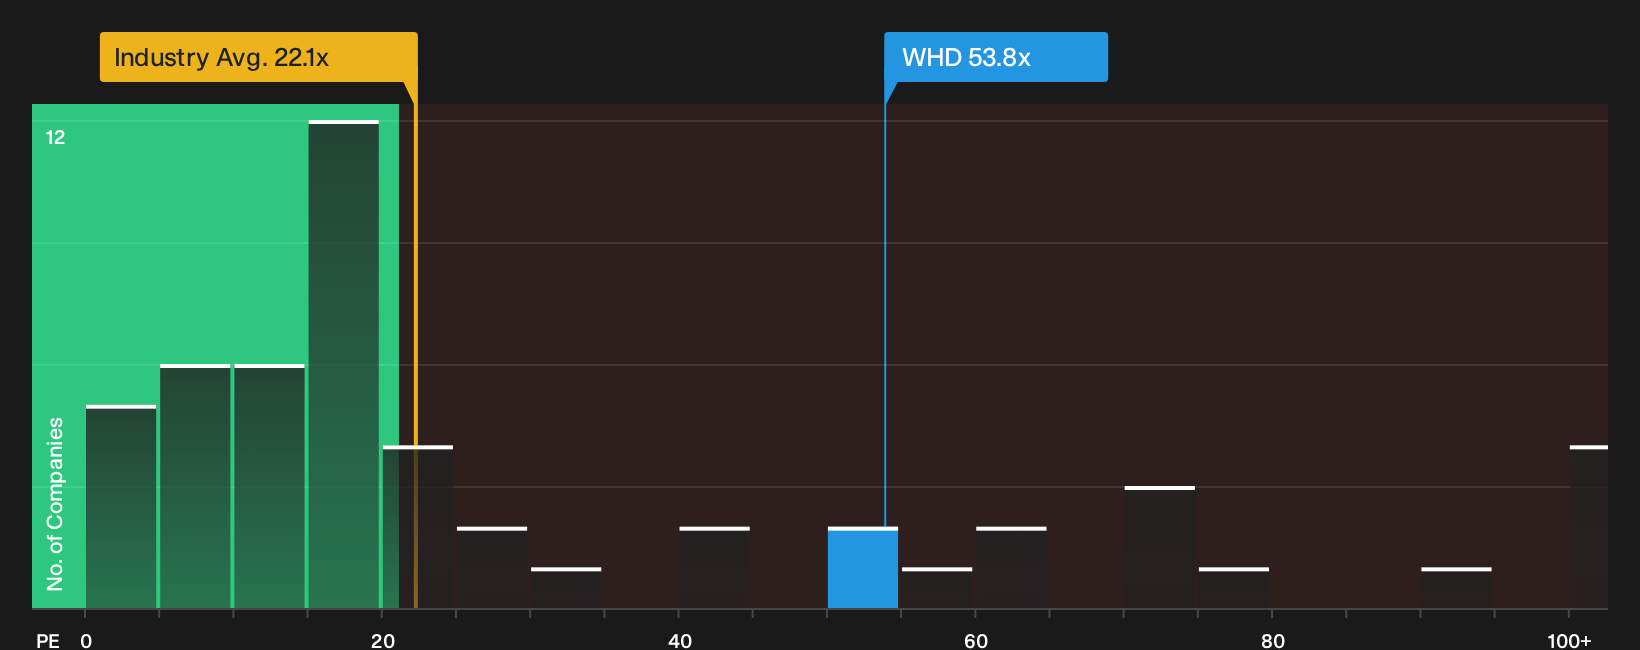
The P/E ratio suits Cactus because investors often anchor on how many dollars they pay for each dollar of current earnings. At roughly 53.8x earnings, the stock trades well above the Energy Services industry average of about 22.1x and also above the peer group level near 29.3x. That kind of gap indicates the market is placing a premium on the business, rather than treating it as another cyclical equipment provider.
The fair multiple implied by Cactus's own profile of margins, growth expectations, size and risk sits below the current 53.8x level, so the shares screen as overvalued on this framework. For anyone assessing the price, the key question is whether the strength of the earnings stream and its resilience within the energy cycle justify paying this much more than both the sector and the tailored benchmark. Explore the numbers behind Cactus's P/E valuation.
The Cactus Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E debate on Cactus' valuation leaves off by spelling out which assumptions on its future growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price. Each narrative treats fair value as a thesis about how Cactus' business might play out that you can track over time, rather than a static one-off number.
Views on Cactus split around how much value to place on its international build out and spoolable pipe push compared with the execution and tariff risks tied to that same expansion.
Bull case: 12% undervalued
"The earlier FlexSteel acquisition has evolved into the current Spoolable Technologies segment, where Cactus is adding about 20% Baytown capacity and evaluating an Eastern Hemisphere plant…"
Discover why this Narrative puts Cactus at 12% undervalued.
Bear case: 11% overvalued
"Growing exposure to international and sour service spoolable pipe, including new orders in the Middle East and Africa, ties a larger portion of revenue to long lead, project based markets…"
Explore why this Narrative puts Cactus at 11% overvalued.
One more part of Cactus that could change the picture
Valuation focuses on the numbers, but the people steering Cactus and how they are rewarded can tilt decisions in subtle but powerful ways, so it is worth understanding that setup. See who runs Cactus and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com