


Intel (INTC) Could Be 83% Undervalued After AI GPU And Foundry Progress
Intel (INTC) is back in focus after unveiling its GPU D-series for AI inference and new Xeon rack designs, pairing product detail with rising expectations ahead of an earnings update and foundry progress.
Intel’s recent GPU and rack announcements land after a sharp pullback, with the 30-day share price return down 29.3% even as the stock remains up 120.8% year to date and has delivered a 127.2% total shareholder return over the past year. This signals strong longer term momentum despite short term profit taking and shifting expectations around AI and foundry execution.
Scan the AI hardware space beyond Intel and shortlist 55 AI infrastructure stocks that could also be positioned for swings in sentiment around inference demand and data center build outs.
The share price now sits well below the average analyst target, while Intel’s own intrinsic value estimate points in the opposite direction. Which side of that spread aligns with the current fundamentals?
Most Popular Narrative: 82.6% Undervalued
Intel’s last close at $86.96 sits far below the fair value of $500.93 used in the most followed narrative, which frames today’s pullback as a valuation gap rather than the end of the story.
Reasons I bought Intel:
• x86 software. a lot of existing software has been created for the x86 architecture and additionally has likely been optimized to run on intel cpus due to them having been the consistent market leader for so long giving them an advantage over AMD.
• This is most noticed when comparing applications using IBOT or Intel Compiler
See why 91 investors see Intel as 83% undervalued.
According to Suen, the narrative that underpins this $500.93 fair value uses a discount rate of 11.31% and leans on Intel’s role as a large US based foundry plus its x86 software base as key supports for that higher figure.
The same storyline also highlights the comparison between Intel and TSMC as a proxy for US versus Taiwan manufacturing, pointing to supply chain depth, engineering talent and equipment in the US against lower labor costs and geopolitical risk in Taiwan.
For investors weighing this against the SWS DCF view, Intel’s share price of $86.96 is trading above an estimated future cash flow value of $78.69, while Suen’s approach suggests the market price is far below where long term assumptions might land.
Result: Fair Value of $500.93 (UNDERVALUED)
Still, Intel’s foundry ambitions and x86 lead both face pressure if AI customers shift workloads more quickly toward alternative architectures, or if execution setbacks keep profitability under strain.
Find out about the key risks to this Intel narrative.
Another View On Intel’s Valuation
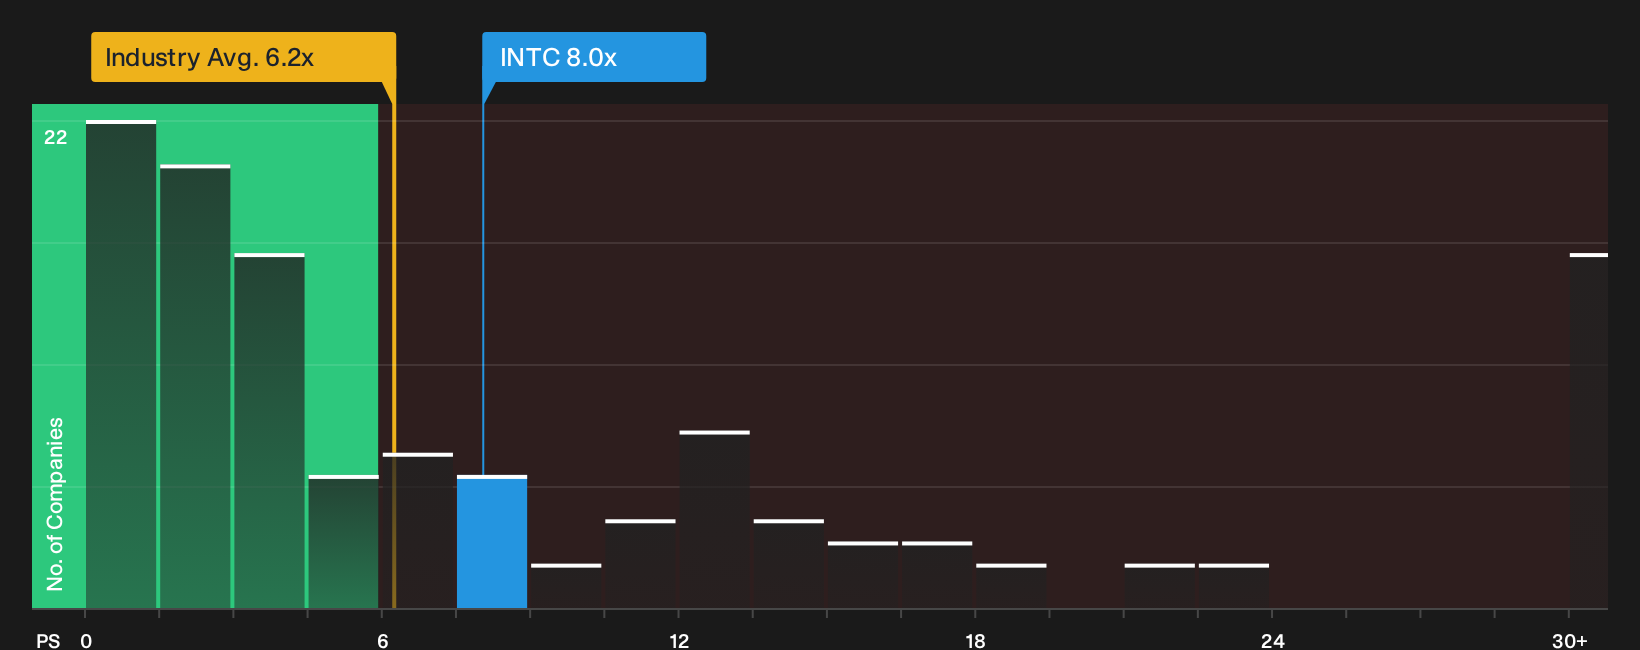
That $500.93 fair value from Suen’s narrative sits far away from what the market is currently paying. On a P/S of 8x, Intel trades richer than the US Semiconductor average at 6.2x, yet still below a fair ratio of 11.9x and below peers at 12.7x. It is unclear whether this represents a margin of safety or a premium that still requires further evidence.
To see how this pricing gap shows up in a simple multiple framework, including where the P/S ratio could drift toward the fair ratio as sentiment changes, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Curious whether the bullish tone around Intel matches your own instincts? Act quickly, stress test the assumptions, and see what supports 1 key reward.
Looking for more investment ideas beyond Intel?
If Intel’s story has you thinking bigger, use this moment to broaden your watchlist and line up the next set of potential opportunities.
- Target resilient balance sheets and steady fundamentals by screening a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without constant drama.
- Hunt for potential bargains by scanning a 29 high quality undervalued stocks where quality, cash generation, and pricing do not seem to fully match up.
- Prioritize consistency and income stability by checking out a 5 dividend fortresses that focus on higher yields with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com