


Will UGG Retail Revival Change Urban Outfitters (URBN) Narrative
- Urban Outfitters announced that it has reunited with UGG for Fall 2026, reviving the On Rotation experiential retail platform across five major U.S. stores with curated footwear, apparel, and immersive try on environments, supported by a broad marketing push.
- The collaboration gives Urban Outfitters another way to monetize its Gen Z reach by testing whether experience led merchandising and UGG focused storytelling can deepen engagement without relying solely on discounting or heavy product churn.
- Attention now turns to how this renewed UGG On Rotation experience might influence Urban Outfitters' broader investment narrative around brand portfolio execution.
Urban Outfitters Investment Narrative Recap
To own Urban Outfitters, you need to be comfortable with a retailer leaning into a multi brand, experience led model while still carrying meaningful cost and margin swings. The UGG On Rotation reset fits that story, but it is not the primary near term driver. The key shorter term swing factor remains how Nuuly, FP Group and core banners offset cost inflation.
The biggest risk today is operating leverage cutting the wrong way if sales slow against higher marketing, logistics and store investment, especially with fuel surcharges already guided as a gross margin headwind. The UGG partnership looks incremental rather than transformative for those cost and margin debates.
The most relevant development is the renewed On Rotation partnership with UGG across five major stores and online marketing. It gives Urban Outfitters another real world test of whether experiential formats and brand storytelling can support full price sell through and reduce reliance on markdown heavy merchandising, a pressure point already visible at Anthropologie.
For you as an investor, the read through sits squarely in the catalyst bucket around AI and data driven merchandising, portfolio balancing and potential gross margin improvement. If concepts like UGG On Rotation help refine store formats, inventory bets and marketing efficiency, they could matter to how well Urban Outfitters manages SG&A leverage and fuel related headwinds over the next few quarters.
Urban Outfitters' current analyst narrative points to revenues of US$7.9b and earnings of US$587.0m by 2029, built on 7.1% yearly revenue growth and an earnings increase of about US$17.9m from US$569.1m today.
Uncover why Urban Outfitters' fair value indicates a 3% potential upside to its current price that could narrow quickly.
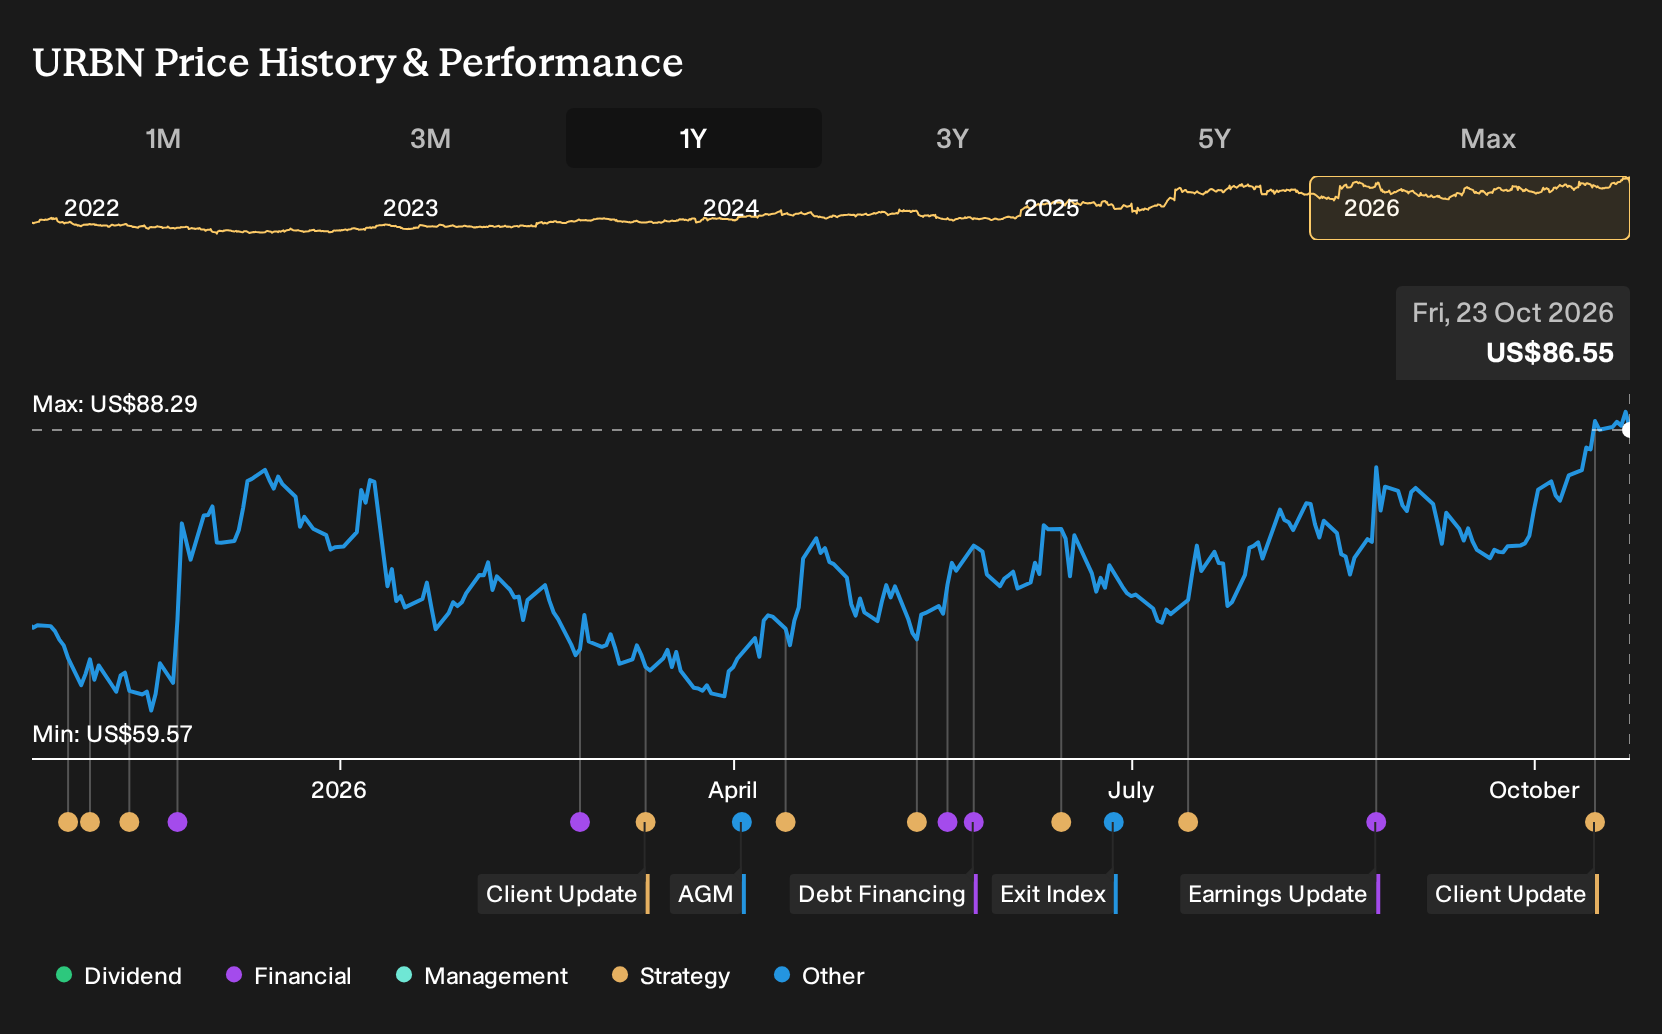
Exploring Other Perspectives
One alternate view treats Urban Outfitters’ experience led retail as a side show next to Nuuly and FP Movement. The most optimistic analysts were already modelling revenue of about US$8.2b and earnings of US$681.7m by 2029. You can now ask whether this UGG On Rotation news nudges those upbeat assumptions even higher or challenges them.
Explore 2 other Urban Outfitters fair value estimates, including one that suggests potential upside of up to 38% from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Urban Outfitters research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Urban Outfitters. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Urban Outfitters' overall financial health at a glance.
Looking for more Urban Outfitters style ideas?
If the Urban Outfitters story has you thinking about what else could fit alongside it in your portfolio, the Simply Wall St Screener can help you quickly sift through other listed businesses that share similar traits or fill very different roles.
- If you want potential value with quality backing it up, scan through 29 high quality undervalued stocks that combine fundamentals with a margin of safety angle.
- If capital preservation matters just as much as upside, consider the 30 resilient stocks with low risk scores that score well on resilience and balance sheet stability.
- If you prefer steady income over headline grabbing stories, review the 5 dividend fortresses that focus on higher yielding payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com