


Aritzia And 2 Canadian Insider Growth Stocks To Watch
With the US Federal Reserve widely expected to hold interest rates steady again, investors are getting more time to reassess growth stories without fresh rate shocks. That pause keeps attention on companies that can grow from their own engines rather than cheaper borrowing. This article looks at three fast growing Canadian stocks where insiders own a lot of the shares, so management’s fortunes move closely with yours.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where leadership is heavily invested alongside shareholders. However, if you want the pick of this theme, these 9 high growth high conviction stocks are the best of the best.
Aritzia (TSX:ATZ)
Overview: Aritzia is a Vancouver based womenswear retailer that designs and sells its own apparel brands through boutiques and online channels across Canada and the United States, aligning tightly with the screener’s focus on fast growing, insider led direct to consumer businesses.
Operations: Aritzia generates about CA$4.3b in apparel revenue, with roughly CA$1.6b from Canada and CA$2.8b from the United States, highlighting its cross border footprint and growth focus.
Market Cap: CA$17.6b
For this screener, Aritzia matters because its own labels, tight founder influenced culture, and expanding boutique and digital footprint give management meaningful control over both growth pace and brand direction.
"Aritzia's ongoing U.S. boutique rollout, with new locations reportedly paying back in under one year and management indicating room to expand from roughly 76 to 82 to at least 180 to 200 boutiques, points to a continued store-led uplift to net revenue."
What really moves the needle from here is how one less visible pressure ultimately feeds through into both profitability and investor confidence.
That pressure point is exactly what the full narrative for Aritzia unpacks in detail, showing where Aritzia’s growth engine could be accelerating or quietly stalling next.

Total Energy Services (TSX:TOT)
Overview: Total Energy Services is a Calgary based oilfield services group that supports drilling and well activity with rigs, compression equipment, rentals, and related services across Canada, the United States, Australia, and other international markets.
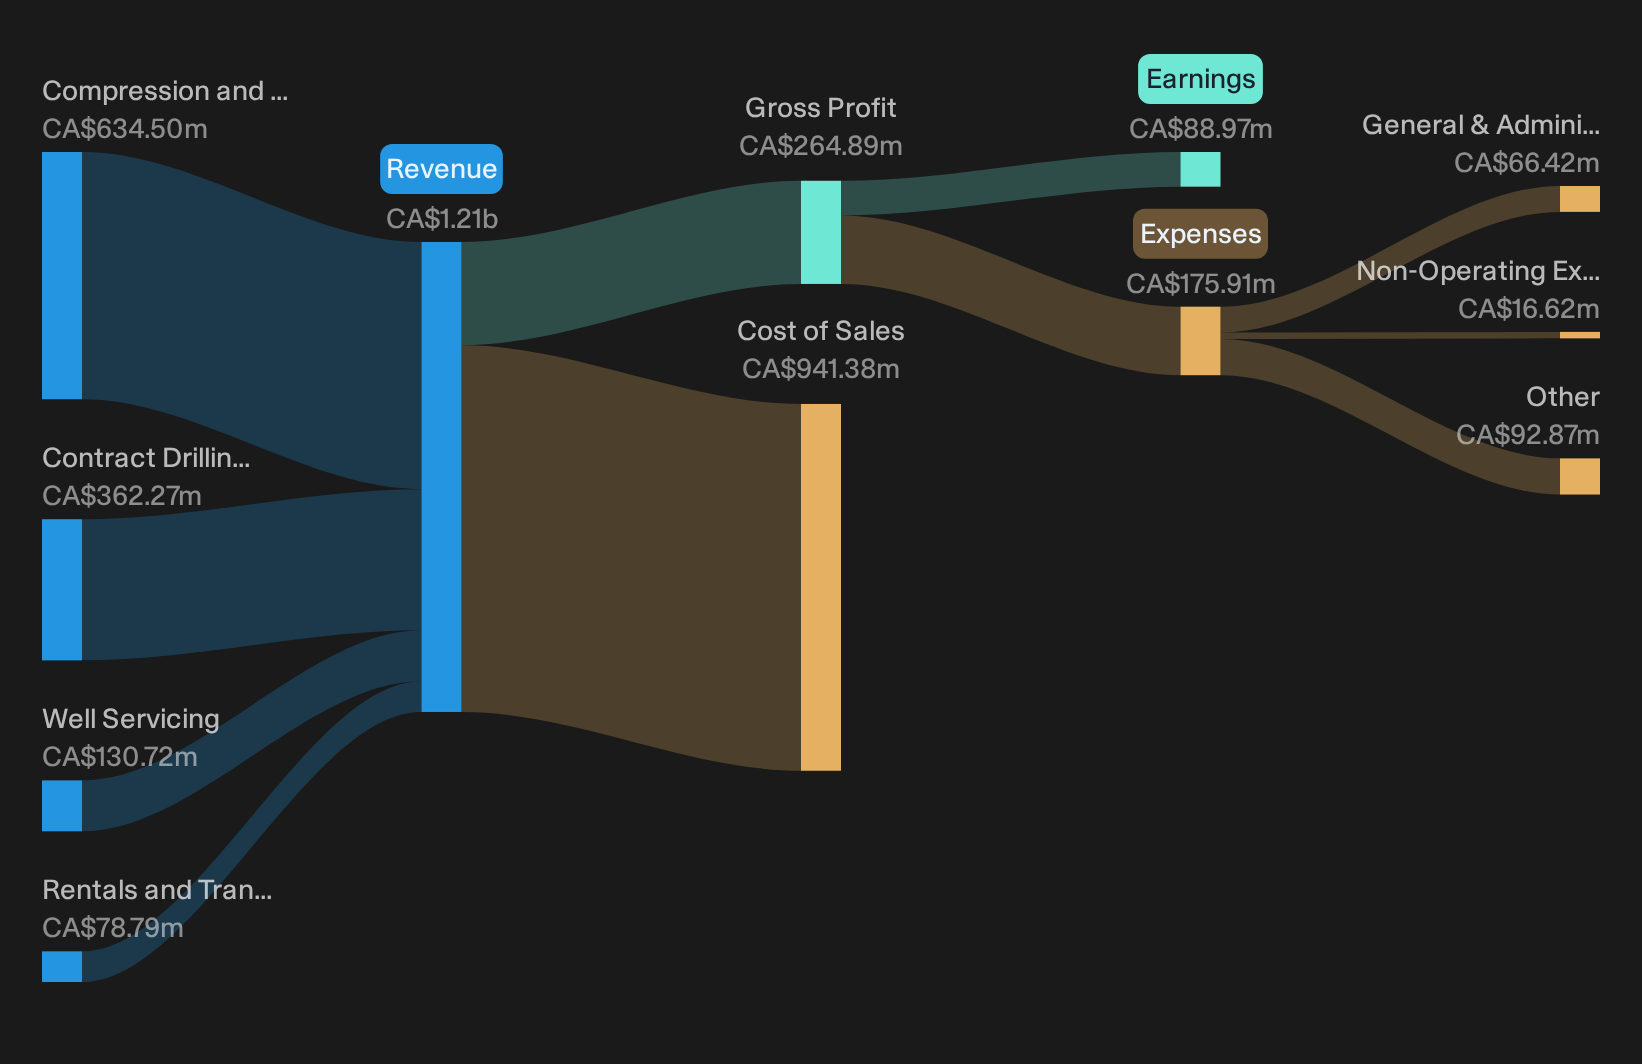
Operations: Total Energy Services generates roughly CA$362 million from Contract Drilling, CA$131 million from Well Servicing, CA$634 million from Compression and Process Services, and CA$79 million from Rentals and Transportation, with revenue mainly from Canada, the United States, and Australia.
Market Cap: CA$1.4b
Total Energy Services is relevant for this insider backed theme because its drilling and well servicing capacity can scale when producers increase spending on new wells and infrastructure projects.
"The company is experiencing strong and growing demand for large-horsepower compression equipment, driven by the expansion of North American LNG export capacity and increased use of natural gas for power generation."
The key variable now is how one capital heavy bet on future activity ultimately affects margins and pricing power.
That capital swing is exactly what the full narrative for Total Energy Services breaks down, separating temporary capital drag from areas where Total Energy Services’ operating leverage could quietly be accelerating.
Ivanhoe Mines (TSX:IVN)
Overview: Ivanhoe Mines is a Vancouver based miner developing and operating copper, zinc, and PGM projects in Africa, with Kamoa-Kakula driving its growth focus.
Operations: The business records about $575 million from Kipushi Properties, with Hong Kong and Singapore contributing roughly $198 million and $219 million respectively.
Market Cap: CA$13.1b
Ivanhoe Mines fits this high growth, high insider ownership theme because Kamoa-Kakula is already delivering scale while a second and third leg of expansion are lining up behind it.
"Catalysts stacked (Phase 3/4 Kamoa ramp to >550 ktpa medium term, Platreef Phase 2, Kipushi de-bottlenecking, smelter online, Project 95 recoveries, exploration)."
What really matters now is how one less visible funding and cost pressure shapes the payoff from all that volume growth.
Those funding choices and cost curves are exactly what the full narrative for Ivanhoe Mines unpacks, highlighting where Ivanhoe Mines’ expansion could be quietly accelerating or where risks might still be masking upside.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. Breakout stories can gain momentum while many investors stay caught reacting late to dropping headlines. Scan these under the radar lists before the crowd and consider them early.
- Target dependable cash generators with the list of solid balance sheet and fundamentals (7 results) to focus on businesses where financial strength may help support the story when sentiment shifts.
- Zero in on future facing infrastructure by running the 55 AI infrastructure stocks and track companies positioned around the build out of data centers and AI capacity while it still matters.
- Track potential income workhorses through the 3 dividend fortresses and look for yields that may compensate you while prices move, rather than chasing payouts after they are crowded.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com