


Entra (OB:ENTRA) Back In Focus On Q3 Loss And New Leases As Valuation Debate Returns
Why Entra stock is back in focus
Entra (OB:ENTRA) has moved back into the spotlight after third quarter figures showed higher sales alongside a sizeable net loss, while fresh long-term leases with public and union tenants reshaped expectations around future rental income.
Recent moves in Entra's share price hint at pressure building rather than easing. The stock is down 12.26% on a 90 day share price basis and the 1 year total shareholder return has fallen 18.85%, despite a positive 12.25% total shareholder return over three years.
Scan beyond Entra and compare it with a hand-picked 221 resilient stocks with low risk scores that has shown steadier share price performance and more resilient risk profiles.
Entra now trades after a steep slide, with fresh long leases set against recent losses. Is most of the repricing already done, or is meaningful upside still ahead?
Most Popular Narrative: 11% Undervalued
Entra last closed at NOK93, while the most followed narrative sets fair value at NOK104.40. This frames the recent price slump as potentially overdone based on those assumptions.
Strong demand for prime office locations in Oslo and other major Norwegian cities, combined with limited new supply in the near term, is likely to support higher occupancy and above-inflation rental growth in Entra's portfolio, positively impacting future revenue and earnings. Continued central government and technology sector employment in Norway provides Entra with a stable, creditworthy tenant base, reducing vacancy risk and supporting sustained rental income visibility for long-term revenue growth.
See why 2 investors see Entra as 11% undervalued.
Result: Fair Value of NOK104.40 (UNDERVALUED)
Still, the narrative around Entra could shift quickly if vacancies continue to rise in its Norwegian offices, or if high leverage collides with tougher refinancing conditions.
Find out about the key risks to this Entra narrative.
Another take on Entra’s valuation
The most followed narrative for Entra leans on earnings forecasts and a fair value of NOK104.40. A very different message comes from our DCF model, which estimates future cash flow value at NOK22.27 per share, implying the stock is trading well above that level. Which yardstick do you trust more when the gap is this wide?
Our DCF model outcome is highly sensitive to the long term cash flow and discount rate assumptions that sit under the surface, so it is worth understanding how that framework works before leaning on it too heavily for Entra. Look into how the SWS DCF model arrives at its fair value.
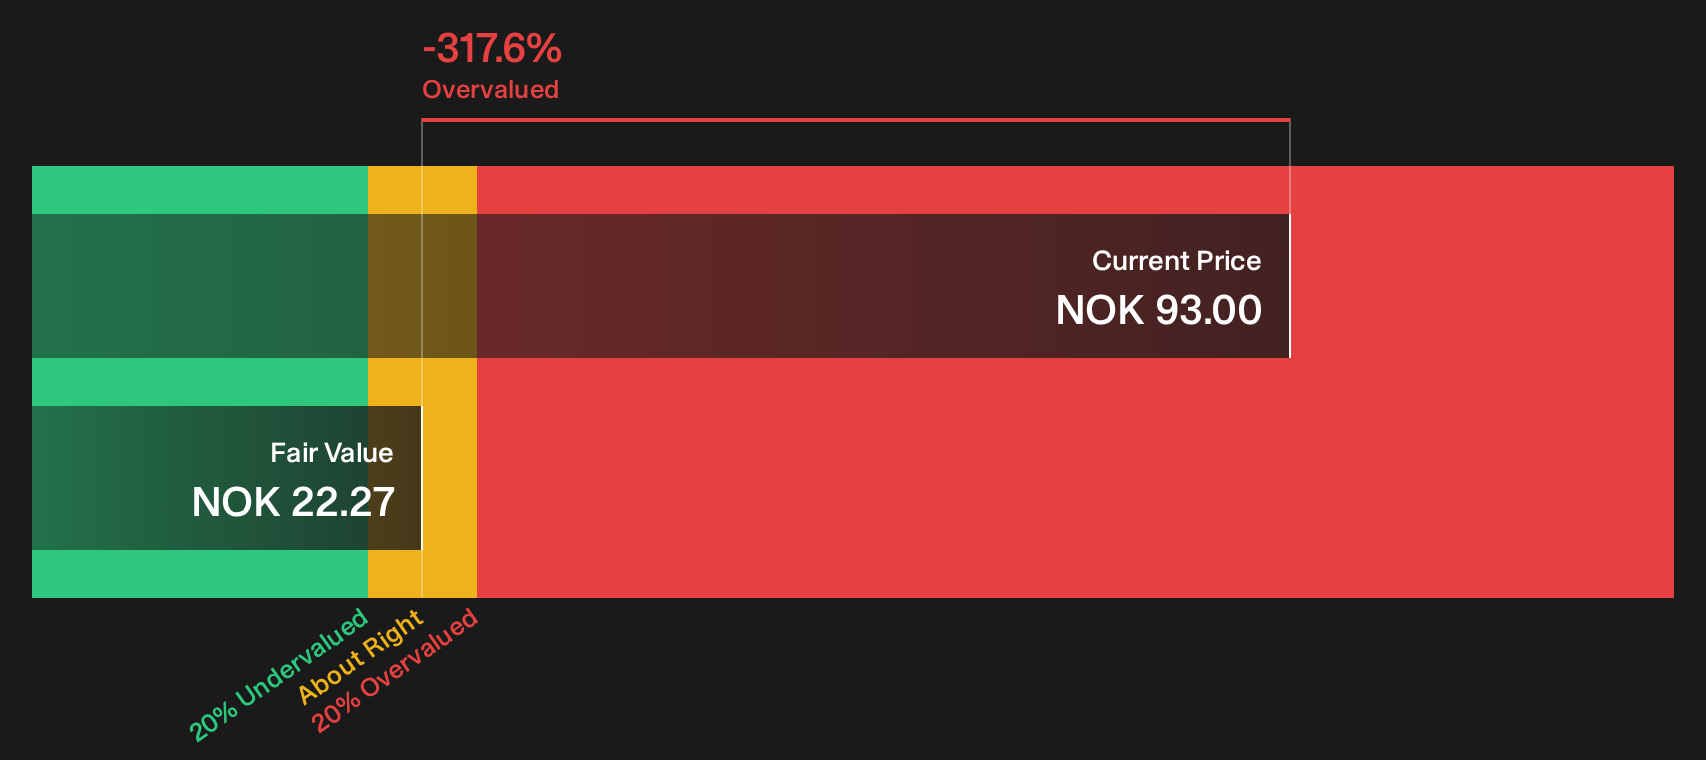
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Entra for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Entra can easily pull you in two directions, so move quickly, test the numbers yourself and decide where you stand. Start with 1 key reward and 1 important warning sign.
Looking for more Entra investment ideas beyond this story?
Do not stop with a single ticker. Broaden your watchlist with a few focused stock ideas that match how you like to balance risk, income, and value.
- Target potential mispricings by scanning a 193 high quality undervalued stocks that blends quality fundamentals with appealing valuations before other investors pay attention.
- Strengthen portfolio resilience by filtering for companies on a list of solid balance sheet and fundamentals (205 results) that prioritise robust finances over fragile capital structures.
- Lock in reliable income candidates by reviewing a curated 225 dividend fortresses where higher yields meet stricter quality filters instead of chasing payout headlines blindly.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com