


Cui Dongshu: In September, China's total production of power and other batteries was 237 GWh, up 57% year on year
The Zhitong Finance App learned that in September, China's combined power and other battery production was 237 GWh, up 57% year on year; in January-September, China's total power and other battery production was 1,833 GWh, up 63% year on year. The battery growth rate gradually declined from more than 60% this year. Due to sluggish demand for power batteries and export tax rebate adjustments, battery demand gradually decelerated.
In September 2026, 87 GWh of lithium batteries were loaded, an increase of 15% over the previous year. From January to September 2026, 576 GWh of lithium batteries were loaded, an increase of 17% over the previous year. In 2025, the proportion of power battery production loaded vehicles dropped to 44%. In September 2026, the proportion of power battery production loaded was 37%, of which the ternary battery loading rate was 35% and lithium iron phosphate loading rate was 37%. In September 2026, the domestic market for lithium battery vehicles loaded 1.26 million units, down 12% year on year, including 810,000 pure electric passenger cars, down 6% year on year; 350,000 plug-in passenger cars, down 29% year on year; and 82,000 pure electric trucks increased 22%. This production data is seriously fragmented.
The proportion of models with a battery energy density above 160 in the 3rd quarter of 2026 was 9%. Compared with 7% in the same period in 2025, there was a clear recovery. This is mainly due to a recovery in high-end demand for three yuan. Meanwhile, products with an energy density below 125 will drop to 0% in 2026.
The competitive pattern of battery companies formed the relatively strong characteristics of the Ningde era (03750) and BYD (01211). In the Ningde era, the share of domestic battery demand rose to 45.1% in July-September 2026, and BYD's share of domestic battery demand rose from 15% in 2020 to 26.9% in 2023. The share of other battery companies also showed a clear trend of differentiation. The top two companies, Ningde and BYD, will maintain a ratio of 63% from 72% in 2022 to 2026, while other companies have room for more than 36%. Innovation Aviation (03931), Sunwoda (300207.SZ), and Zhengli New Energy (03677) performed well this year.
1. Analysis of overall production characteristics of power batteries
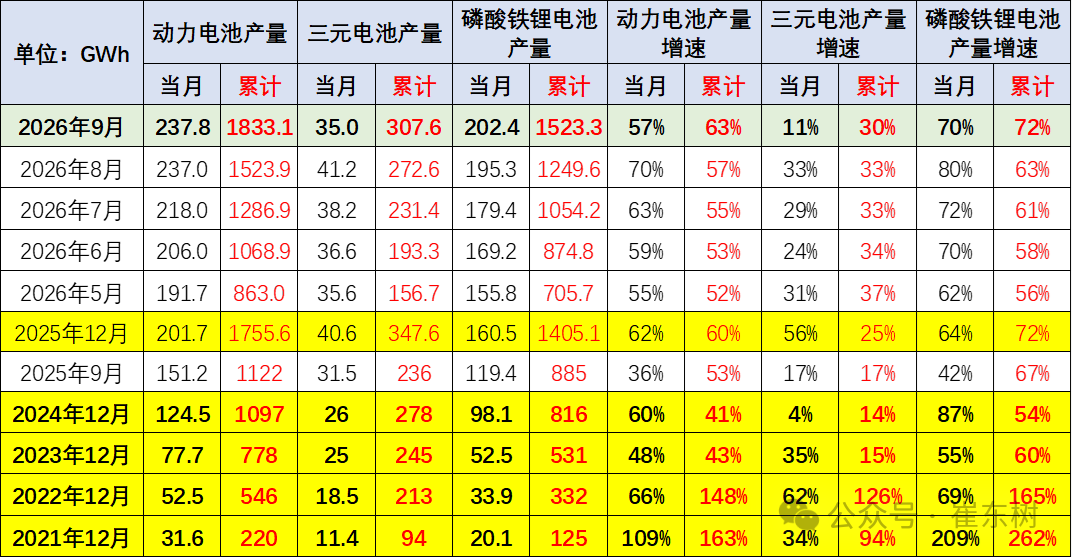
In September, China's total output of power and other batteries was 237 GWh, up 57% year on year; in January-September, China's total output of power and other batteries was 1,833 GWh, up 63% year on year. The battery growth rate gradually declined from more than 60% this year. Due to sluggish demand for power batteries and export tax rebate adjustments, battery demand gradually decelerated.
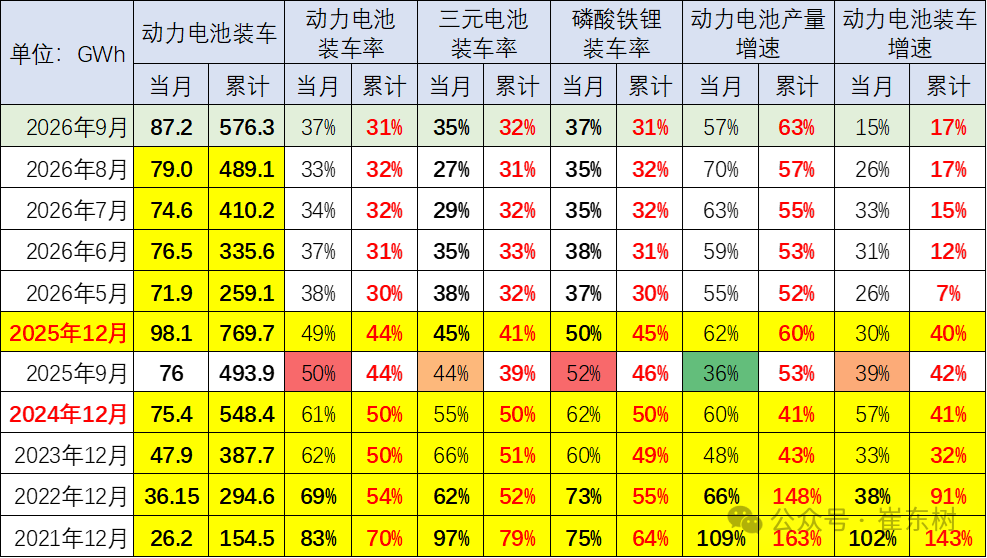
Currently, the proportion of batteries loaded in power battery production is constantly decreasing. In 2021, the battery loading rate reached 70%; 54% in 2022; 50% in 2023; 50% in 2024; 50% in 2024; the proportion of loading in power battery production remained at 50%; in 2025, the proportion of loading in power battery production dropped to 44%. In September 2026, the proportion of loading in power battery production was 37%, with a loading rate of 35% for ternary batteries and 37% for lithium iron phosphate.
The boom in power battery loading has fluctuated this year. With the introduction of truck subsidies, demand for energy storage has declined, and the share of loading has gradually increased recently.
With the development of energy storage and other industries, especially the world energy crisis brought about by the Russian-Ukrainian crisis, demand for batteries in energy storage and other industries grew rapidly, causing the share of batteries loaded to drop significantly, but the market decline at the beginning of the year led to a decline in the share. Both power batteries and energy storage batteries are overproduced and inventories are under high relative performance pressure. The growth rate of power batteries in 2021 and 2022 is lower than the overall vehicle growth rate. In 2023 and 2024, power battery loading was low, and battery production remained the same as the loading growth rate. Battery production was high in 2026, and the start of loading was low. The loading rate in early 2026 fell to a recent low level, and recovered well in September.
2. Domestic models have a low share of three yuan in certified batteries
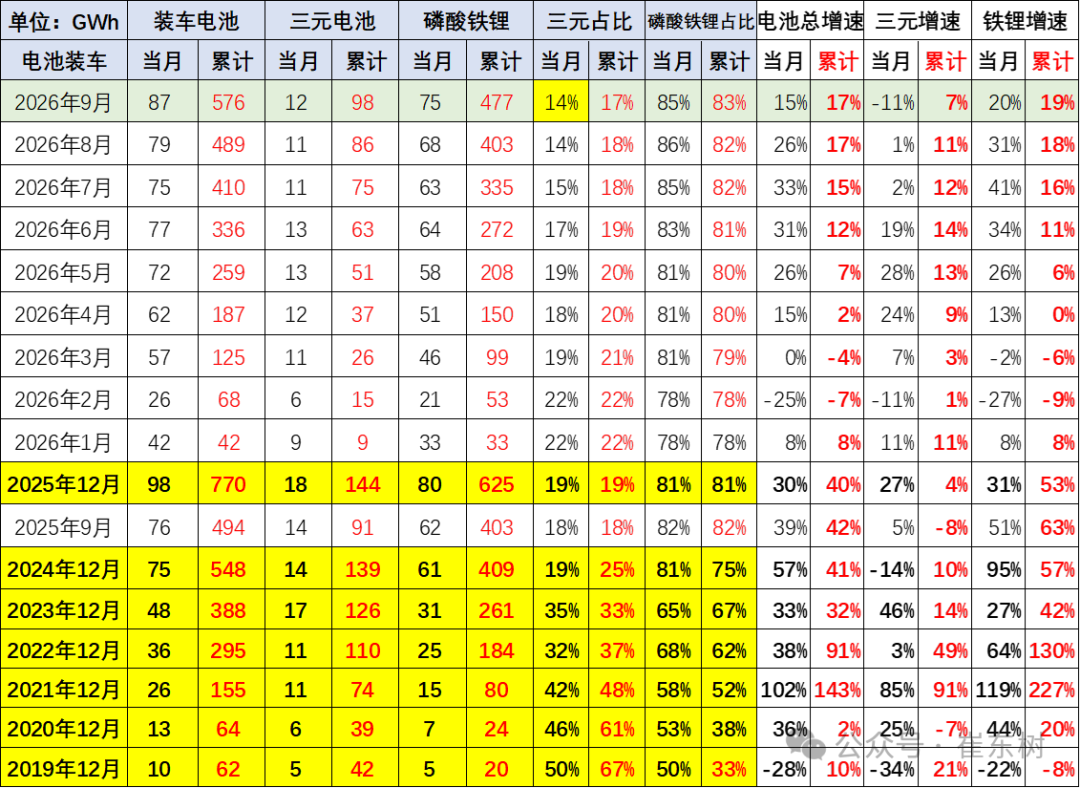
Demand for power battery loading is growing at a very high rate. Demand increased 10% in 2019; power battery loading for domestic models was 64GWH in 2020, demand increased by 2%; power batteries were loaded in 2021, demand increased by 143%; 295GWh was loaded in 2022, demand increased by 91%; 388GWh was loaded in 2023, demand increased 32%; in 2024, 548 GWh of lithium batteries were loaded, up 41% year on year; in 2025, 770 Wh, up 40% year on year; in September 2026, lithium batteries were loaded at 87GWh, up 15% year on year, 2026 In January-September, 576 GWh of lithium batteries were loaded, an increase of 17% over the previous year.
3. Demand growth for automotive batteries is slowing down
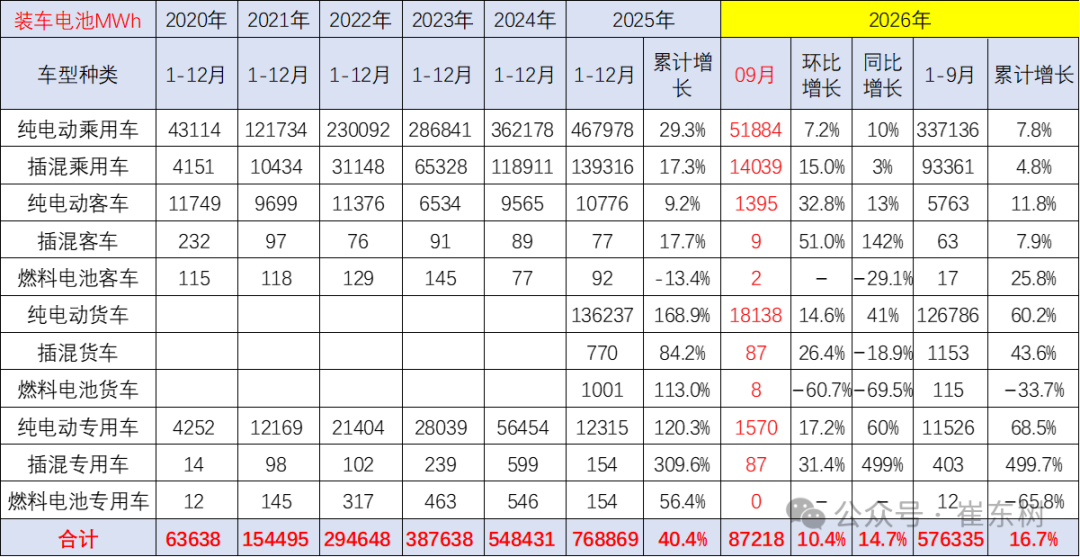
Demand for passenger car batteries continues to grow strongly. Battery demand for pure electric passenger cars increased by 29% in 2025, while battery demand for plug-in hybrid passenger cars increased 17%, continuing to grow strongly. Demand for batteries for electric vans has also increased dramatically, reaching 169%.
Battery loading increased 17% from January to September 2026. Among them, commercial vehicles grew strongly. In particular, pure electric trucks soared by 41% in September, while battery usage for pure electric passenger vehicles increased by only 10%.
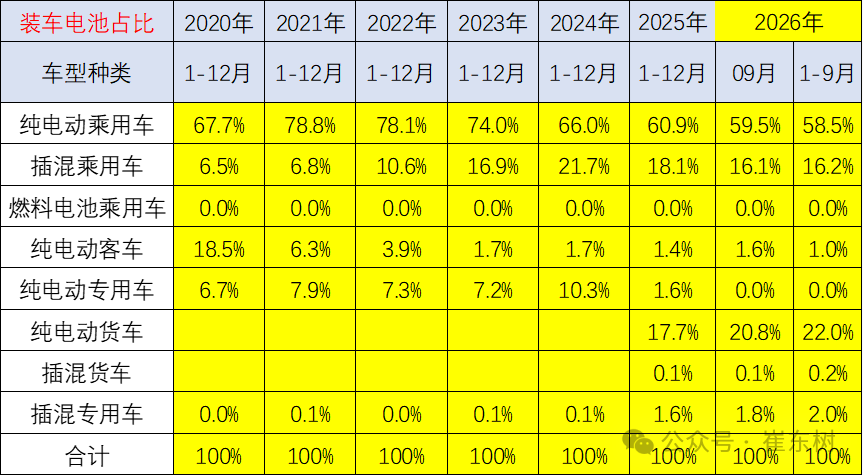
Judging from the proportion of batteries loaded, the demand structure for power batteries has changed rapidly in recent years. 2020 is still the pattern of pure electric passenger cars first, pure electric buses second, and pure electric special vehicles third, while plug-in hybrid passenger cars are only in fourth place. By 2026, pure electric passenger cars will remain in first place, while plug-in hybrid passenger cars will drop to third place, pure electric trucks will rise to second place, plug-in hybrid special vehicles will maintain fourth place, and pure electric buses will drop to fifth place.
In recent years, the market for pure electric buses has declined sharply, while the amount of batteries used in pure electric special vehicles has continued to rise rapidly. At present, the battery usage of pure electric passenger cars and plug-in hybrid passenger cars has dropped dramatically, while the battery usage of heavy trucks has increased dramatically. The advantages of high subsidies for heavy trucks brought about by new energy subsidies have led to a trend of battery differentiation.
4. Vehicle certification production
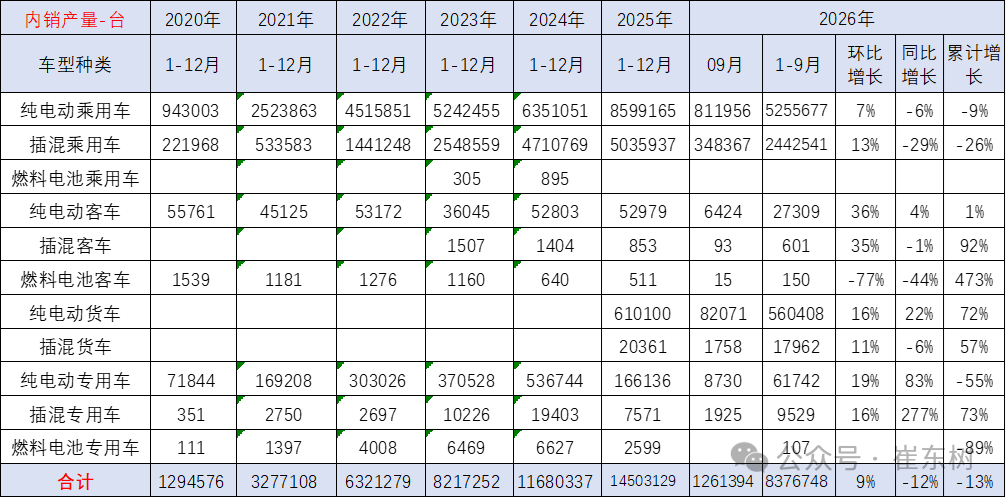
According to certified battery capacity estimates, in 2025, there were 14.5 million domestic certification certificates for new energy vehicles, an increase of 24% over the previous year, including 8.6 million pure electric passenger vehicles, an increase of 35% over the previous year; 5.03 million plug-in passenger cars, an increase of 7% over the previous year; and 780,000 pure electric special vehicles and trucks. This production data is very strong.
In September 2026, the domestic market for lithium battery vehicles loaded 1.26 million units, down 12% year on year, including 810,000 pure electric passenger cars, down 6% year on year; 350,000 plug-in passenger cars, down 29% year on year; and 82,000 pure electric trucks increased 22%. This production data is seriously fragmented.
5. Supporting battery companies are far from fully competitive
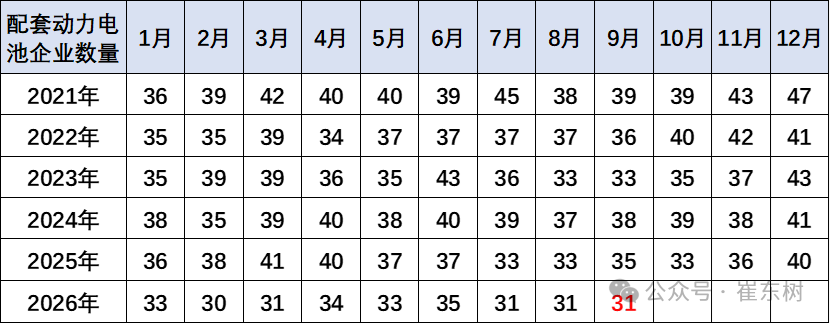
The competitive landscape of the battery market has not changed significantly in the past few years. In September 2026, the number of supporting battery companies reached a low level of 31 companies during the year. Due to price differences in the power battery market, and the characteristics of scale growth are relatively obvious. Coupled with the development of demand in new industries such as energy storage, battery companies have obtained strong characteristics of increased production and loading volume.
6. Differentiation of battery charge for various models
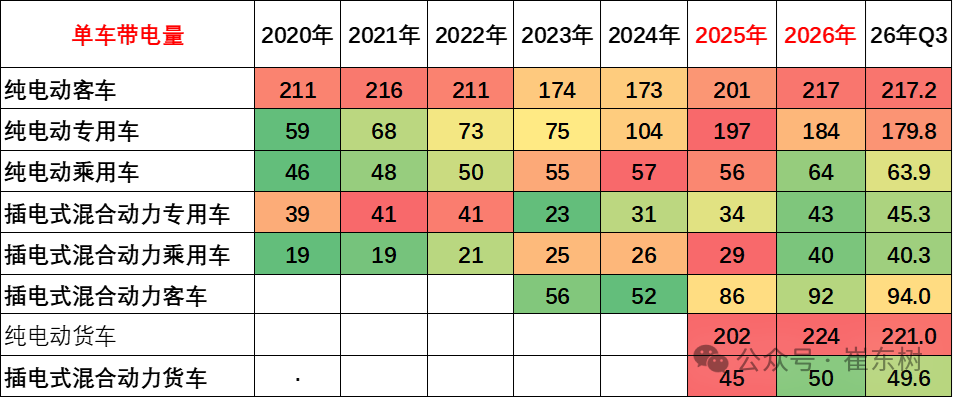
As battery prices fall, the range of electric vehicles continues to increase. Currently, there is a strong demand for high-end electric vehicles in the electric vehicle market. Instead, it is similar to “old man music” upgrading to small mini cars, and policy pressure is high, leading to obvious high-end technology. In the second half of 2024, with the promotion of trade-in and other policies, the car market picked up, and mini electric vehicles became popular, leading to a decline in installed batteries. As the cost advantages of electric vehicles were reflected, the structure of pure electric special vehicles developed towards heavy trucks, driving a sharp increase in charged capacity.
As far as supply chain issues are concerned, automakers will become more and more powerful in the future, their ability to control battery companies and the upstream industry chain will be further strengthened, and at the same time, their control over downstream brand marketing capabilities will also be further strengthened. Under the new energy system, the characteristics of “the whole vehicle is king” will continue to be further reflected.
7. Batteries with high energy density need to recover
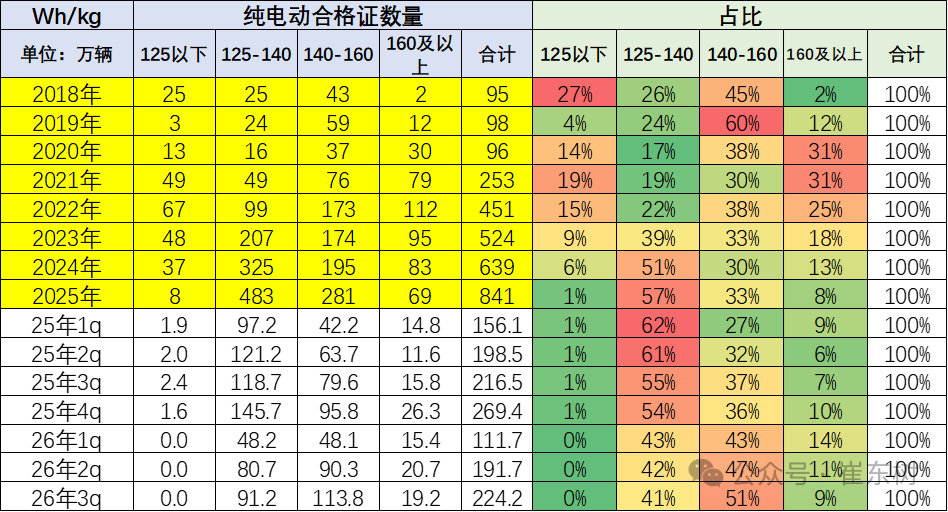
Currently, the main battery energy density range for pure electric vehicles is between 125 and 160. In particular, the outstanding performance in the 3rd quarter of 2026 was that 140 to 160 batteries accounted for 51%, an increase of 14 percentage points over the previous year.
The proportion of models with a battery energy density above 160 in the 3rd quarter of 2026 was 9%. Compared with 7% in the same period in 2025, there was a clear recovery. This is mainly due to a recovery in high-end demand for three yuan. Meanwhile, products with an energy density below 125 will drop to 0% in 2026.
8. Battery enterprise pattern
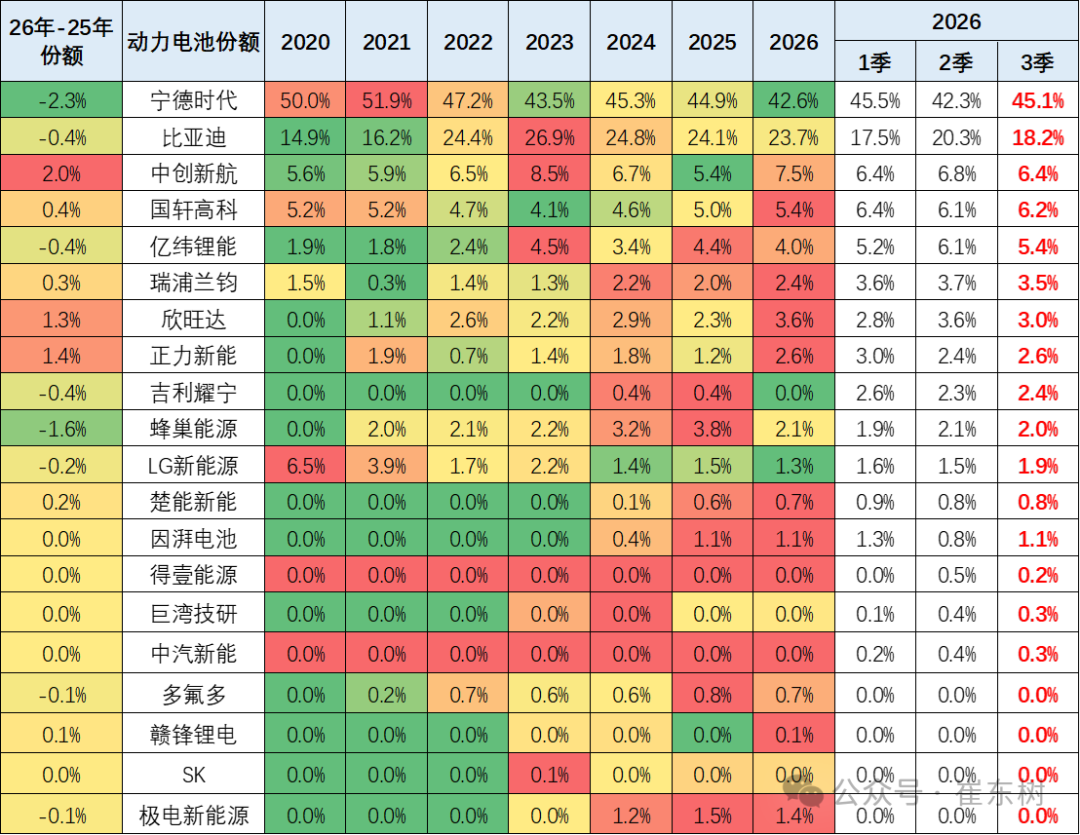
The competitive pattern of battery companies forms relatively strong characteristics of the Ningde era and BYD. In the Ningde era, the share of domestic battery demand rose to 45.1% in July-September 2026, and BYD's share of domestic battery demand rose from 15% in 2020 to 26.9% in 2023. The share of other battery companies also showed a clear trend of differentiation. Battery companies have formed a characteristic of slowing down the agglomeration effect of leading companies. The top two companies, Ningde and BYD, will maintain a ratio of 63% from 72% in 2022 to 2026, and other companies have room for more than 36%. Innovation Aviation, Sunwoda, and Zhengli Xinneng performed well this year.
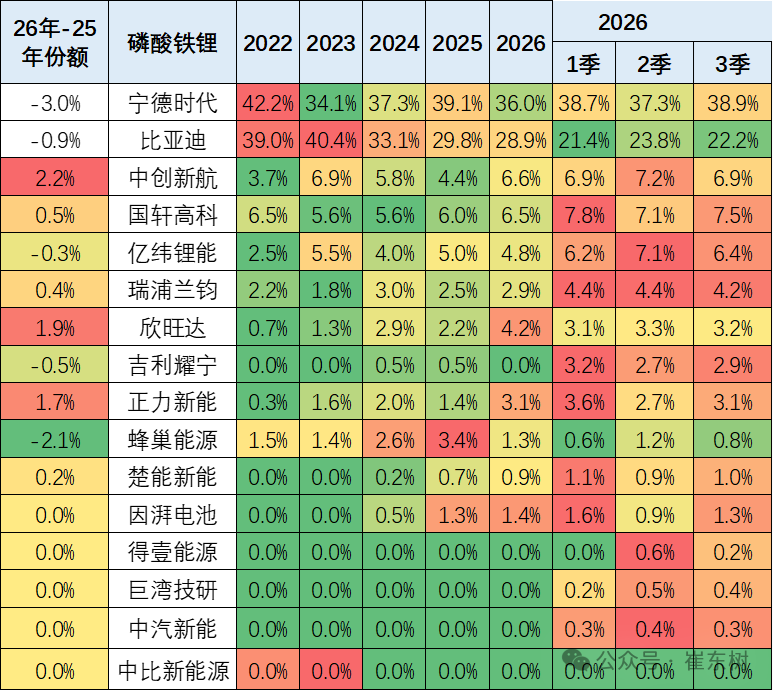
The product differences and advantages of lithium iron phosphate batteries are obvious. BYD is still relatively good, but at the beginning of this year, it was in a period of domestic adjustment, and its export performance was very strong, but there are no statistics. Everweft Lithium Energy and Guoxuan Hi-Tech performed well. Sunwoda, Ruipu Lanjun, and Geely Yaoning have improved markedly.
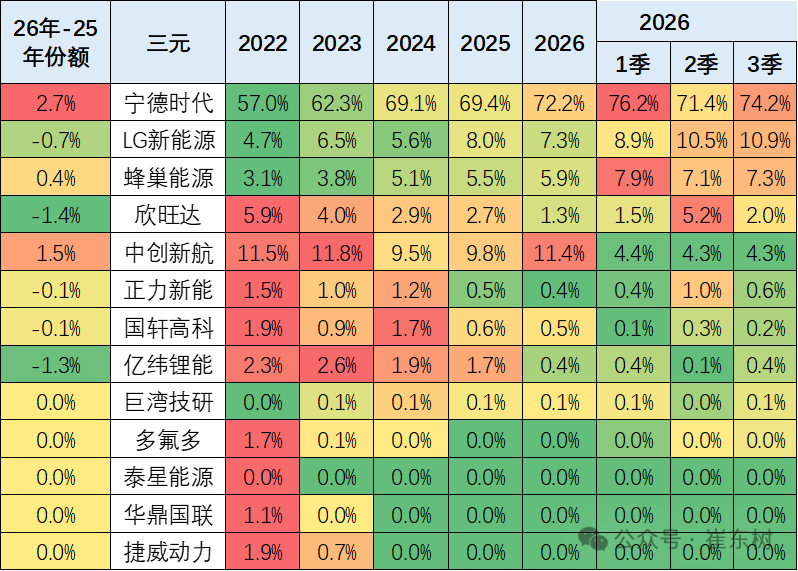
Due to BYD's complete transformation of lithium iron phosphate batteries, the advantages of ternary batteries from the top four companies, including Ningde Era, Honeycomb, Sunwoda, and LG, are even more obvious. Recently, Great Wall Motor's honeycomb energy performance has been relatively good. LG New Energy's statistical performance is poor due to the decline in Tesla's domestic sales ratio.