


Is Rapid7 (RPD) Fully Valued As AI Security Hopes Lift The Stock?
Recent attention on securing enterprise AI agents has pushed Rapid7 (RPD) to sharpen its tools for AI related vulnerabilities, and that shift is now feeding directly into the stock’s valuation debate.
Momentum around Rapid7 has accelerated, with a 7 day share price return of 18.24% and a 90 day share price return of 54.99%. This has lifted the stock to US$14.91, even though the 1 year total shareholder return is still down 22.26% and the 5 year total shareholder return has fallen 88.42%.
Scan how Rapid7’s AI security story compares with other potential breakout plays across our hand picked 39 profitable AI stocks that aren't just burning cash that already pair real earnings with exposure to the same theme.
Rapid7 now trades above the analyst target yet sits at a sizeable discount to one intrinsic value estimate. Where does fair value really land after this latest surge in the share price?
Most Popular Narrative: 27% Overvalued
Rapid7 closed at $14.91 while the most followed narrative pegs fair value at $11.71. The recent AI driven enthusiasm is being weighed directly against a higher discount rate and softer revenue assumptions.
Rapid7's unified Command platform and MDR-led solutions are increasingly winning larger, strategic consolidation deals as enterprises seek to reduce fragmentation and simplify compliance in complex, highly regulated environments. This points to an expanding addressable market, higher average revenue per customer, and a sustained revenue growth opportunity.
See why 14 investors see Rapid7 as 27% overvalued.
Result: Fair Value of $11.71 (OVERVALUED)
Still, pressure on annual recurring revenue and ongoing weakness in legacy vulnerability management mean Rapid7’s AI story can quickly crack if those trends worsen.
Find out about the key risks to this Rapid7 narrative.
Another View: DCF Points to Undervaluation
The analyst narrative puts Rapid7 at $11.71 fair value, which frames the stock as about 27% overvalued versus the current $14.91 price. A different lens tells a very different story. The SWS DCF model estimates future cash flows at $29.84 per share, implying Rapid7 trades at roughly a 50% discount instead.
If those cash flow inputs hold up, the gap between an $11.71 analyst target and a $29.84 DCF fair value becomes the key question. Is the market overpaying for near term AI enthusiasm, or underpricing the longer term earnings forecast that underpins that cash flow view?
Look into how the SWS DCF model arrives at its fair value.
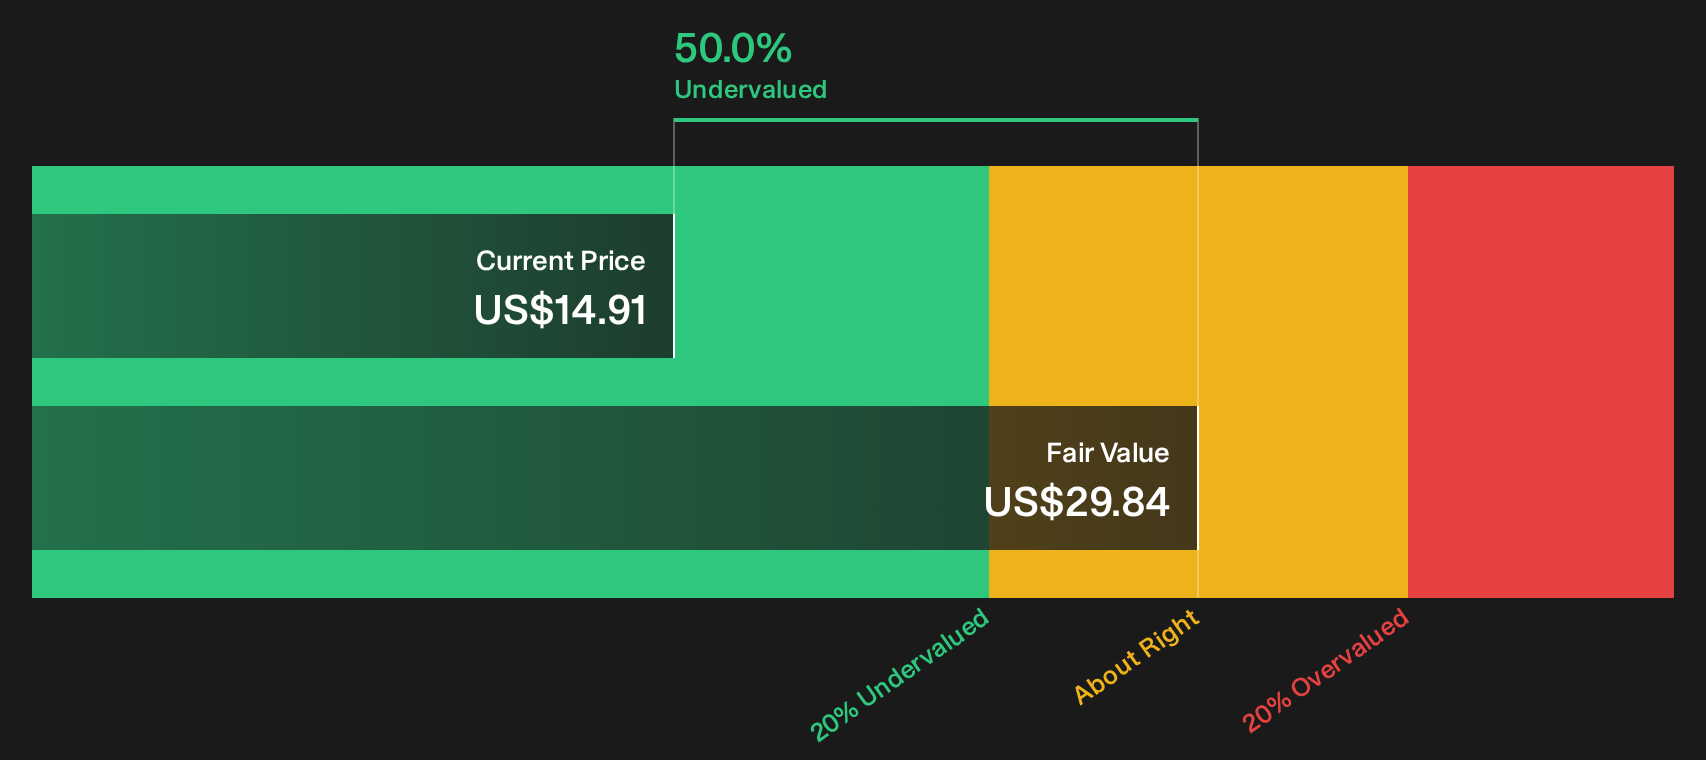
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Rapid7 for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed about the Rapid7 story after all that. Act while the data is still fresh in the market’s mind and weigh both sides through 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Rapid7?
If Rapid7 has sharpened your focus on quality opportunities, do not stop here. Cast the net wider now so you are not chasing prices later.
- Zero in on quality at a discount by reviewing our 29 high quality undervalued stocks that already screen for strength and pricing discipline.
- Strengthen your portfolio’s foundations by checking the list of solid balance sheet and fundamentals (24 results) that are built on sturdier financial footing.
- Spot tomorrow’s potential standouts early by scanning the 21 high quality undiscovered gems before wider attention catches up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com