


Does New Oil Production Change The Bull Case For Murphy Oil Stock (MUR)?
- Murphy Oil reported a successful appraisal at Bubale West-1X offshore Côte d’Ivoire, new oil discoveries offshore Vietnam, first oil from the Lac Da Vang field and fresh production from the Chinook #8 well in the Gulf of America, all confirmed in October 2026.
- These overseas and Gulf of America wells highlight how Murphy Oil is trying to turn recent capital spending into tangible barrels and flowing production across several basins at once.
- We will now look at how Murphy Oil's investment narrative could shift as first oil at Lac Da Vang starts feeding production.
Scan for other oil and gas explorers turning fresh wells into new production by checking out our handpicked 16 top copper producer stocks alongside Murphy Oil's latest offshore results.
Murphy Oil Investment Narrative Recap
To own Murphy Oil, you need to believe its higher 2026 capital spending can turn Bubale, Vietnam and Gulf of America work into durable production while keeping the balance sheet and dividend intact. The fresh wells help that narrative, but the short term swing factor is still whether new volumes arrive close to plan and budget.
The biggest risk has not changed. Bubale appraisal and wider offshore activity remain expensive, and any cost overruns or weaker than expected recoveries could pressure free cash flow. The recent updates are positive operationally, but do not yet remove the uncertainty around full cycle project returns.
The most relevant update for you is first oil at Lac Da Vang in Vietnam. This moves the project from promise to producing asset and starts the clock on how quickly Murphy Oil can bring those barrels up to meaningful rates and manage operating uptime, which matters for offsetting the heavier capital bill elsewhere.
Lac Da Vang now links directly to the broader catalyst list. Execution here, together with the Lac Da Trang North discovery on the same block, can influence how much production mix shifts toward offshore volumes. Any delays, reservoir surprises or higher unit costs would feed into the same central question, whether recent spending earns its keep.
Murphy Oil's narrative projects US$3.3b revenue and US$679.5 million earnings by 2029. This assumes 3.6% yearly revenue growth and an earnings increase of about US$384 million from US$295.2 million today.
Uncover why Murphy Oil's fair value indicates a 5% potential downside to its current price, which leaves little room for error.
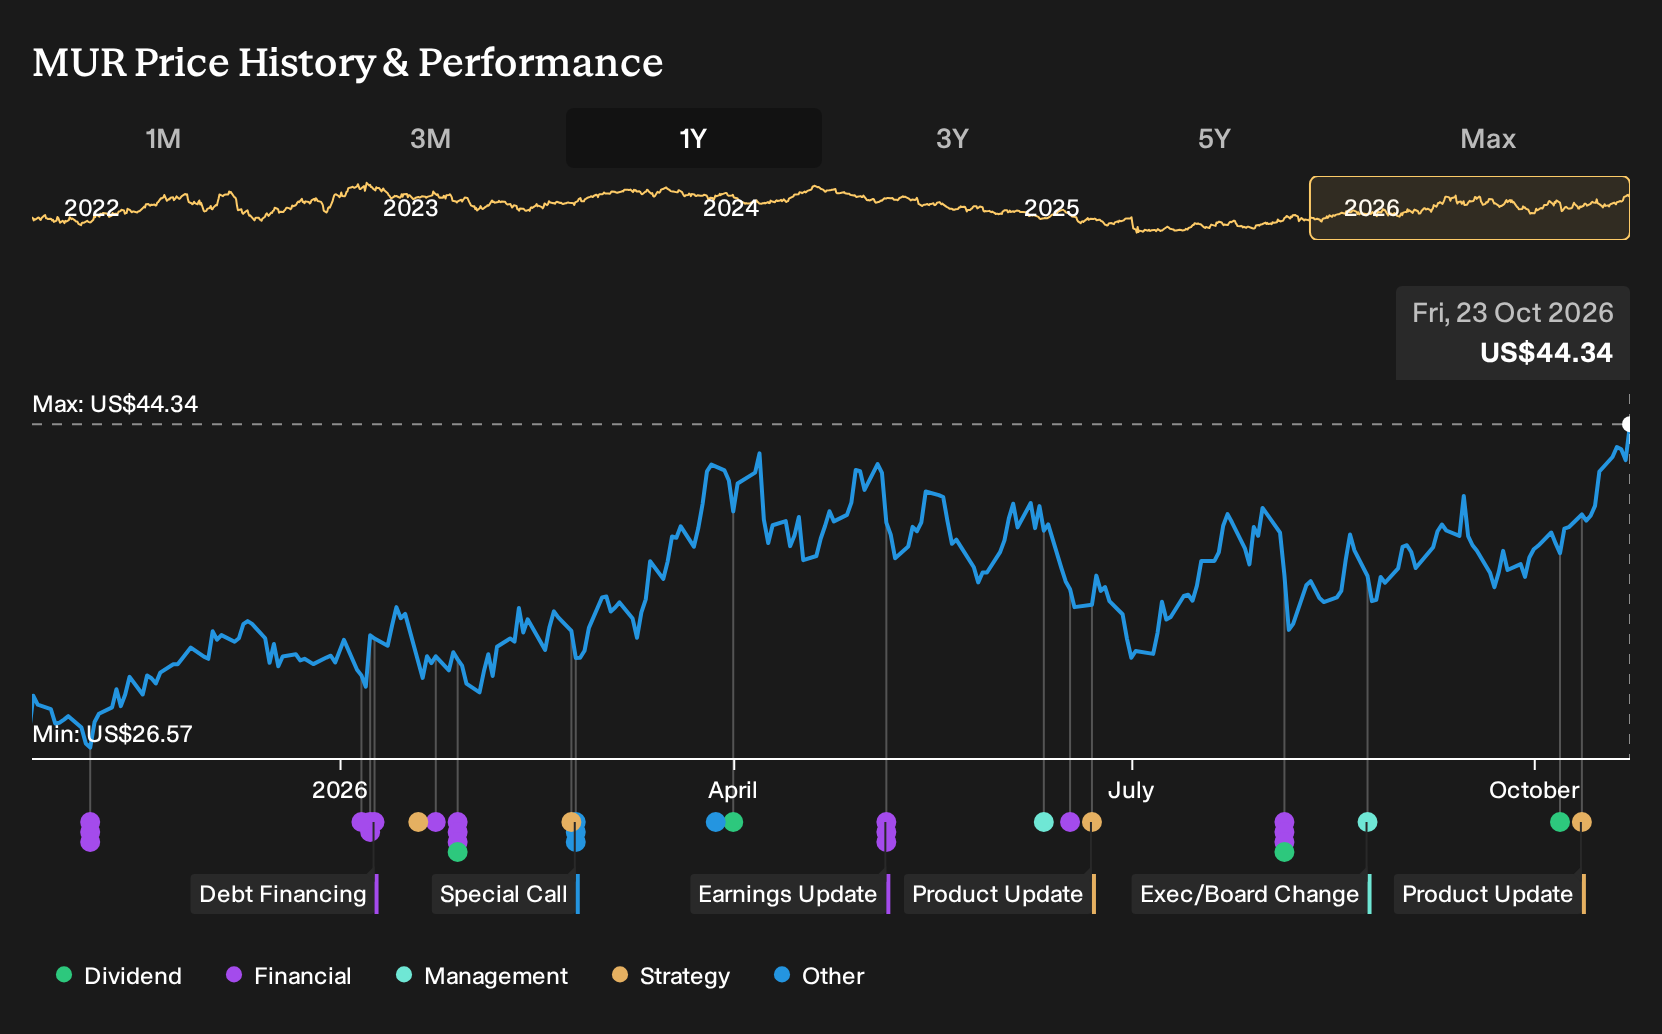
Exploring Other Perspectives
One alternate view focuses on capital risk rather than new barrels. The most cautious Murphy Oil analysts saw only 2.3% yearly revenue growth and about US$418.1 million in 2029 earnings before this news. That is far below the US$679.5 million consensus. Use this spread as your cue to explore how opinions might shift after these wells.
Explore 2 other Murphy Oil fair value estimates, including one that suggests as much as 5% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Murphy Oil research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Murphy Oil. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Murphy Oil's overall financial health at a glance.
Looking for more Murphy Oil style ideas?
If the Murphy Oil story has sharpened your thinking about capital allocation and production risk, use that same lens to hunt for other opportunities with the Simply Wall St Screener.
- For investors who want potential mispricing with solid fundamentals doing the heavy lifting, scan our curated set of 29 high quality undervalued stocks that fit tight quality and value criteria.
- If your priority is resilience through different cycles, focus on companies with cleaner finances by filtering through the list of solid balance sheet and fundamentals (24 results) and see which ones line up with your risk profile.
- For those hunting for underfollowed stories that the market may not be paying much attention to yet, widen your net with the 21 high quality undiscovered gems and compare their setups to what you see at Murphy Oil.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com