


How Strong Q3 Earnings Will Impact Tomra Systems Stock Investors
- Tomra Systems reported Q3 2026 sales of €366 million and net income of €24 million, with earnings per share from continuing operations at €0.08. The company also signed a letter of intent to supply around 2,000 reverse vending machines to a major UK retailer starting in 2027.
- The combination of higher reported profit in Collection and the prospective UK rollout provides a clearer view of how near-term execution, contract quality, and service intensity may influence Tomra Systems' ability to convert regulatory tailwinds into steadier earnings.
- The next step is to examine how Tomra Systems' improved profit mix, supported by UK contract momentum, could reshape its broader investment narrative.
Tomra Systems Investment Narrative Recap
To own Tomra Systems, investors need to believe that deposit return schemes and automation in recycling and food sorting can translate into steadier earnings over time, not just bursts of equipment demand. Q3 2026 showed healthier profit from Collection and stable earnings per share for the nine month period, which supports that view but does not fully settle it.
The key near term catalyst is the conversion of UK, Poland and other scheme rollouts into recurring service income at acceptable margins. The main risk remains softness in Recycling orders and pressure on Collection equipment margins, particularly given higher debt levels and more limited room for error if cash generation proves weaker than expected.
The letter of intent in the UK is the announcement that currently stands out as most important for this catalyst narrative. Tomra Systems is now positioned as preferred supplier for roughly 2,000 reverse vending installations with a large retailer, scheduled to start in 2027 and covering equipment sales, leases and servicing.
This prospective contract ties directly to the idea that new deposit schemes can support the Collection segment, even while Recycling orders and Food activity are more uneven. Execution will depend on profitable rollout, high service uptime and disciplined capital use, as the company already has higher gearing and relies entirely on external borrowing for funding.
Tomra Systems' current analyst narrative points to forecast revenue of €1.9b and projected earnings of €229.7 million by 2029, implying about 9.9% yearly revenue growth and an earnings increase of roughly €146.7 million from earnings today of €83.0 million.
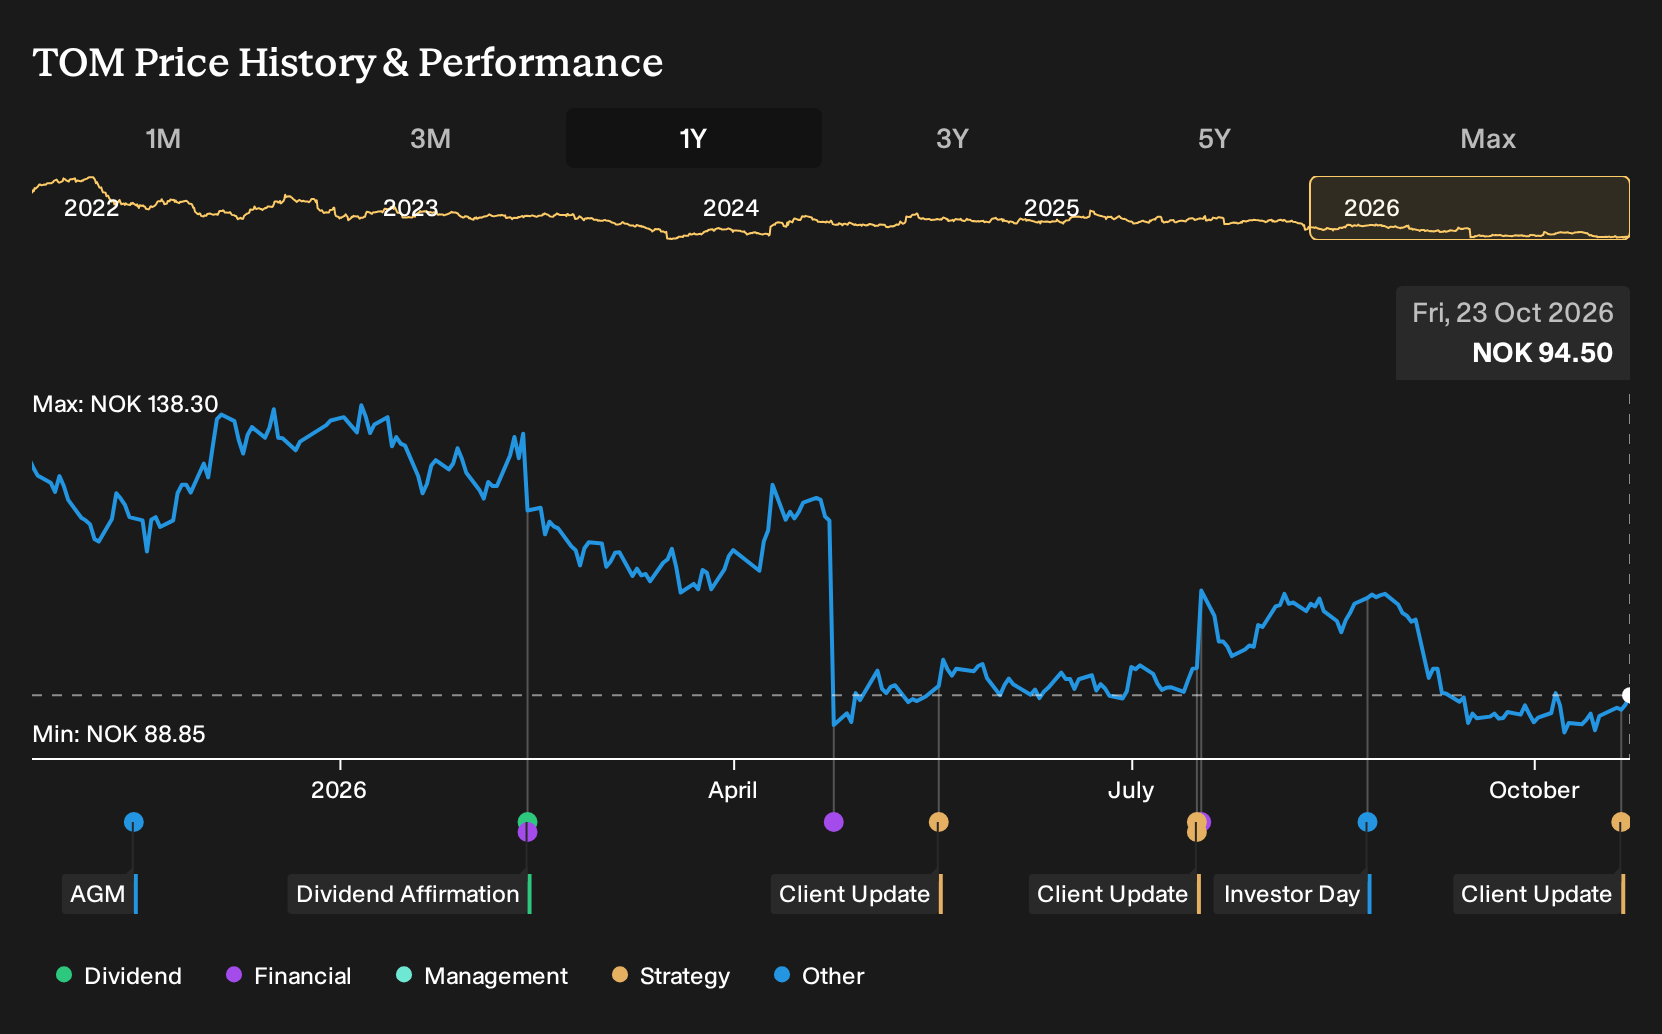
Uncover why Tomra Systems' fair value indicates a 30% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Tomra Systems, the most optimistic analysts focus on the potential earnings power of high margin service and software contracts rather than the current order wobbles. Before this Q3 news, that group was already pencilling in revenue of about €2.1b and earnings near €277.1 million by 2029. You can compare that with the more cautious consensus and decide which narrative feels closer to your own expectations, knowing both were set before the latest UK letter of intent and profit mix shift.
Explore 5 other Tomra Systems fair value estimates, including one that suggests as much as 228% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own research and going with your instincts.
- A great starting point for your Tomra Systems research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Tomra Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tomra Systems' overall financial health at a glance.
Looking for more Tomra Systems investment ideas?
If the Tomra Systems story has sharpened your view on recycling, regulation and automation, it can help to compare it with other opportunities that share some of the same qualities. The Simply Wall St Screener filters the wider market so you can focus on businesses that match your risk tolerance, income needs and return goals.
- For investors who care most about resilient earnings and fewer surprises, scan a curated set of resilient stocks with low risk scores using the 221 resilient stocks with low risk scores.
- If capital strength and clean balance sheets matter to you, narrow the field to companies with solid finances through the list of solid balance sheet and fundamentals (205 results).
- When you want quality but prefer situations that may be flying under the radar, broaden your watchlist with a hand picked pool of 613 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com