


Demant (CPSE:DEMANT) Gains Ground In US Veterans Channel On A Fully Valued Narrative
Demant (CPSE:DEMANT) just logged a sixth straight month of market share gains in the US veterans hearing aid channel, edging up to 24% in September and reinforcing its position in this specialised market.
That market share momentum has been mirrored in the trading data, with Demant’s share price up 16.86% over the past month and 28.58% over 90 days. The 1-year total shareholder return of 53.16% indicates that longer term momentum is building behind the story.
Scan how Demant’s momentum compares with a curated set of peers on the 613 high quality undiscovered gems quietly building strength in their niches.
After a run like Demant’s, the temptation is to wait for a pullback rather than step in at DKK 359. The real question is whether the current valuation already reflects that momentum.
Most Popular Narrative: 7% Overvalued
Demant’s most followed valuation storyline places fair value at DKK 336.75, which sits below the latest close at DKK 359. This gap puts the share price slightly ahead of that narrative, so any new buyer needs to judge whether the premium fits the medium term expectations baked into the model.
Persistent macroeconomic uncertainty and consumer cautiousness have led to lower-than-expected market growth, causing both delays in new purchases and upgrades of hearing aids. This reduces overall demand and impacts revenue and profitability.
Shift in sales toward lower ASP (average selling price) geographies and product mixes (for example, growth mainly outside the US and in free-to-client categories in key markets like France) has led to declining global ASP and unfavorable geographic mix. This erodes group gross margins and reduces EBIT.
See why 6 investors see Demant as 7% overvalued.
Result: Fair Value of DKK336.75 (OVERVALUED)
Still, the narrative can unravel if hearing aid demand in key markets remains weak, or if sales keep skewing toward lower priced regions and products, keeping margins under pressure.
Find out about the key risks to this Demant narrative.
Another View: SWS DCF Flags Upside For Demant
The first storyline presents Demant as roughly 7% overvalued at DKK 359 relative to a DKK 336.75 fair value. A different lens tells another story. The SWS DCF model puts estimated value closer to DKK 573.25, which is about 37% above the current price. Which narrative appears more reasonable to you?
Before leaning too hard on either conclusion, it helps to see exactly how those future cash flows are modeled and discounted in practice. Look into how the SWS DCF model arrives at its fair value.
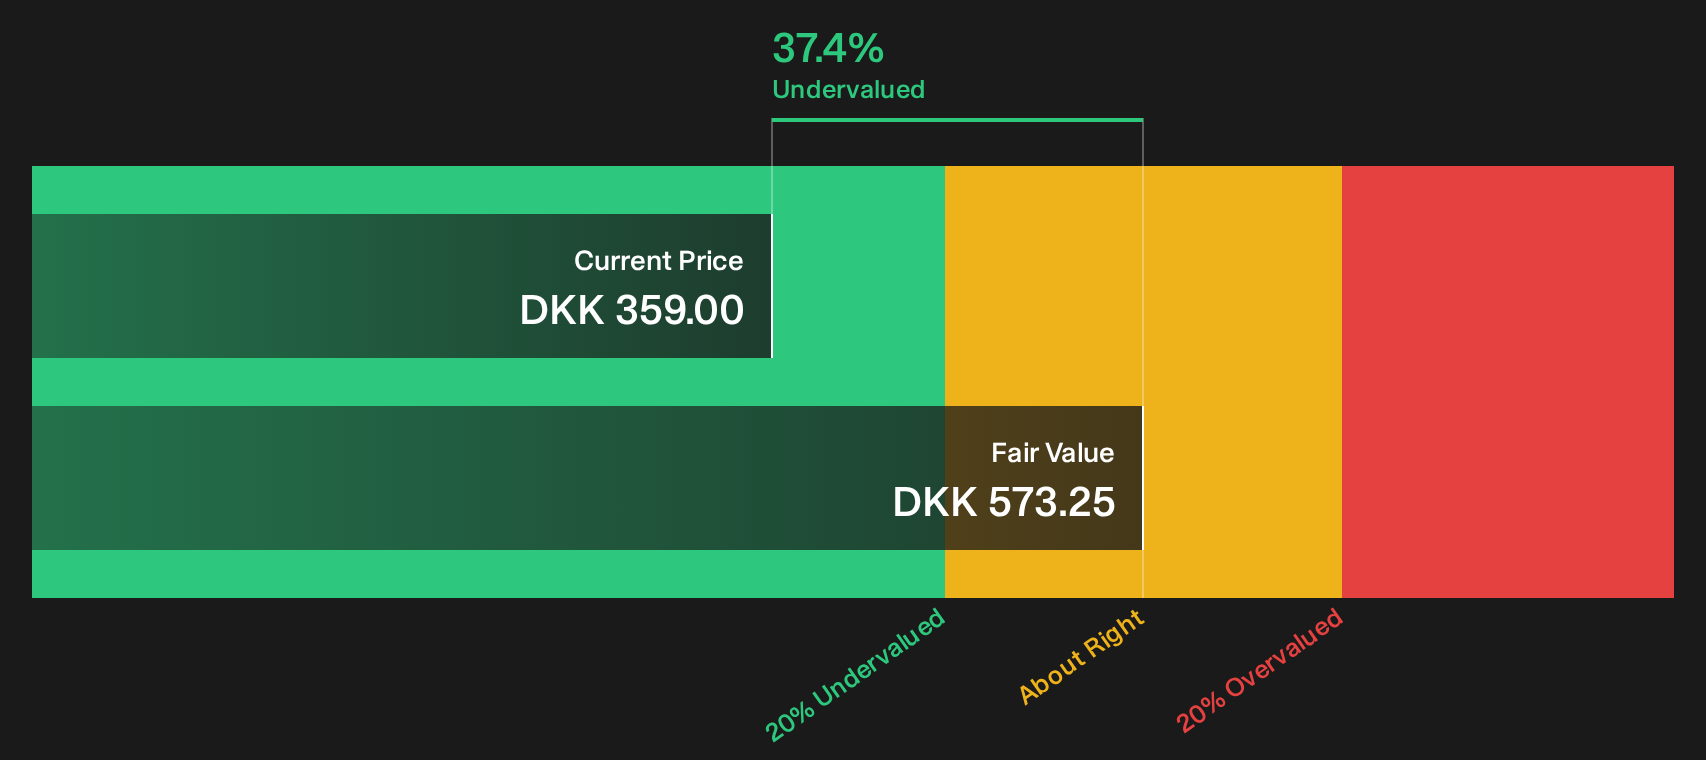
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Demant for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Momentum, valuation tension and mixed signals on risks and rewards make Demant a live debate right now. Move quickly, review the data, and weigh the balance of 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Demant?
If Demant has put momentum and valuation on your radar, do not stop here. Broaden your watchlist with other focused ideas that match different styles of investing.
- Target resilient compounding potential by reviewing companies on the 193 high quality undervalued stocks that pair quality fundamentals with prices below estimated worth.
- Strengthen income potential by scanning the 225 dividend fortresses that offer higher yields while still keeping an eye on balance sheet support.
- Dial down portfolio stress by shortlisting candidates from the 221 resilient stocks with low risk scores that score well on financial robustness and volatility measures.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com