


Stewart Information Services (STC) Dropped, What Is Behind The Latest Attention?
Stewart Information Services (STC) just posted its third quarter 2026 results, reporting a mix of higher sales and softer earnings that pushed the stock lower as investors weighed ongoing housing market pressure.
The latest move in Stewart Information Services shares fits a wider downtrend, with the 1-day share price return falling 10.5% after the Q3 release and the 30-day share price return down 25.5% as investors reassess housing-linked risk and earnings resilience. That near term pressure contrasts with a 3-year total shareholder return of 12.8%, although the 1-year total shareholder return has declined 39.1% as mortgage rate concerns and softer residential activity weigh on sentiment.
Spot potential rebounds or steadier housing plays by scanning our hand picked 30 resilient stocks with low risk scores that have held up better against rising mortgage rate pressure.Stewart Information Services now trades at a steep 41% discount to analyst targets after the post earnings drop. Is that a mispriced housing cycle squeeze, or a fair warning signal on risk?
Most Popular Narrative: 42% Undervalued
On the narrative view, Stewart Information Services screens as materially cheaper than its implied fair value of $76.25, given the last close at $44.07 and the described long term earnings path that analysts are using in their models.
Expansion of the Real Estate Solutions segment, which recently recorded revenue growth of 56% in Q1 2026 and 75% in Q2 2026 along with adjusted pretax margins progressing into the roughly 12.5% to 14% range, positions this lender-focused business to contribute more to consolidated revenue and to support ongoing adjusted margin improvement.
See why 2 investors see Stewart Information Services as 42% undervalued.
Result: Fair Value of $76.25 (UNDERVALUED)
Still, this hinges on Stewart Information Services managing higher operating costs and avoiding a prolonged drag from weak existing home sales, which could restrain margins.
Find out about the key risks to this Stewart Information Services narrative.
Another View: Stewart Information Services Through A Cash Flow Lens
While the analyst narrative points to Stewart Information Services trading 42% below a fair value of $76.25, the SWS DCF model tells a cooler story. On that cash flow view, the shares at $44.07 sit above an estimated value of $36.37, which frames the stock as overvalued instead of cheap.
The gap between a DCF value below the current price and a higher analyst fair value puts the spotlight on your assumptions. Are long term earnings paths and housing volume recovery strong enough in your view to lean more on the analyst model, or does the cautious cash flow output carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
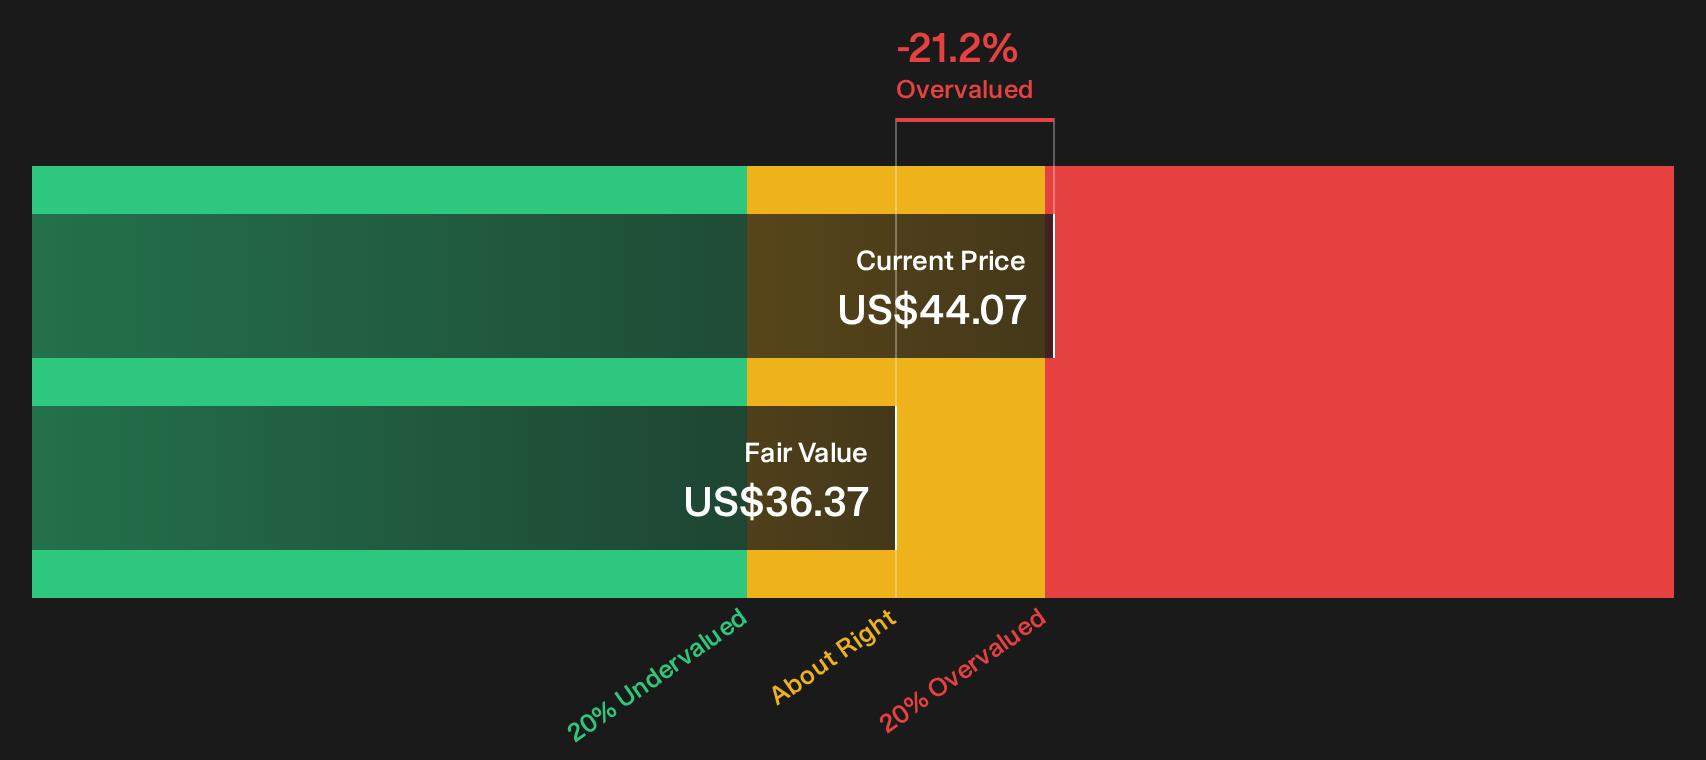
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Stewart Information Services for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of signals on Stewart Information Services feels split, treat it as your cue to move quickly and evaluate the potential upside yourself. Start by weighing the 4 key rewards.
Looking For More Investment Ideas Beyond Stewart Information Services?
Do not stop your research with Stewart Information Services when a broader watchlist could surface opportunities that match your risk level, income goals, and growth expectations.
- Target dependable balance sheets by scanning the list of solid balance sheet and fundamentals (24 results) to find companies with finances and fundamentals you can more clearly evaluate.
- Look for pricing gaps using the 29 high quality undervalued stocks to identify companies trading below what their underlying business performance might indicate.
- Strengthen your income focus by reviewing the 5 dividend fortresses to explore higher-yielding payers with more robust profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com