


Should Earnings Growth Require Action From Colgate Palmolive Stock Investors?
- Colgate-Palmolive India has already confirmed that marketing veteran Akash Parekh will become executive vice president, marketing, on 1 December 2026, following the departure of long-serving leader Gunjit Jain after more than 18 years with the business.
- The incoming EVP has nearly 17 years inside Colgate-Palmolive across India, North America and Asia Pacific. This supports continuity in brand strategy, commercial execution and consumer insight work as the group focuses on premium oral care and emerging markets.
- We will look at how Colgate-Palmolive's investment narrative is shaped by expectations for higher earnings alongside this India marketing leadership change.
Colgate-Palmolive Investment Narrative Recap
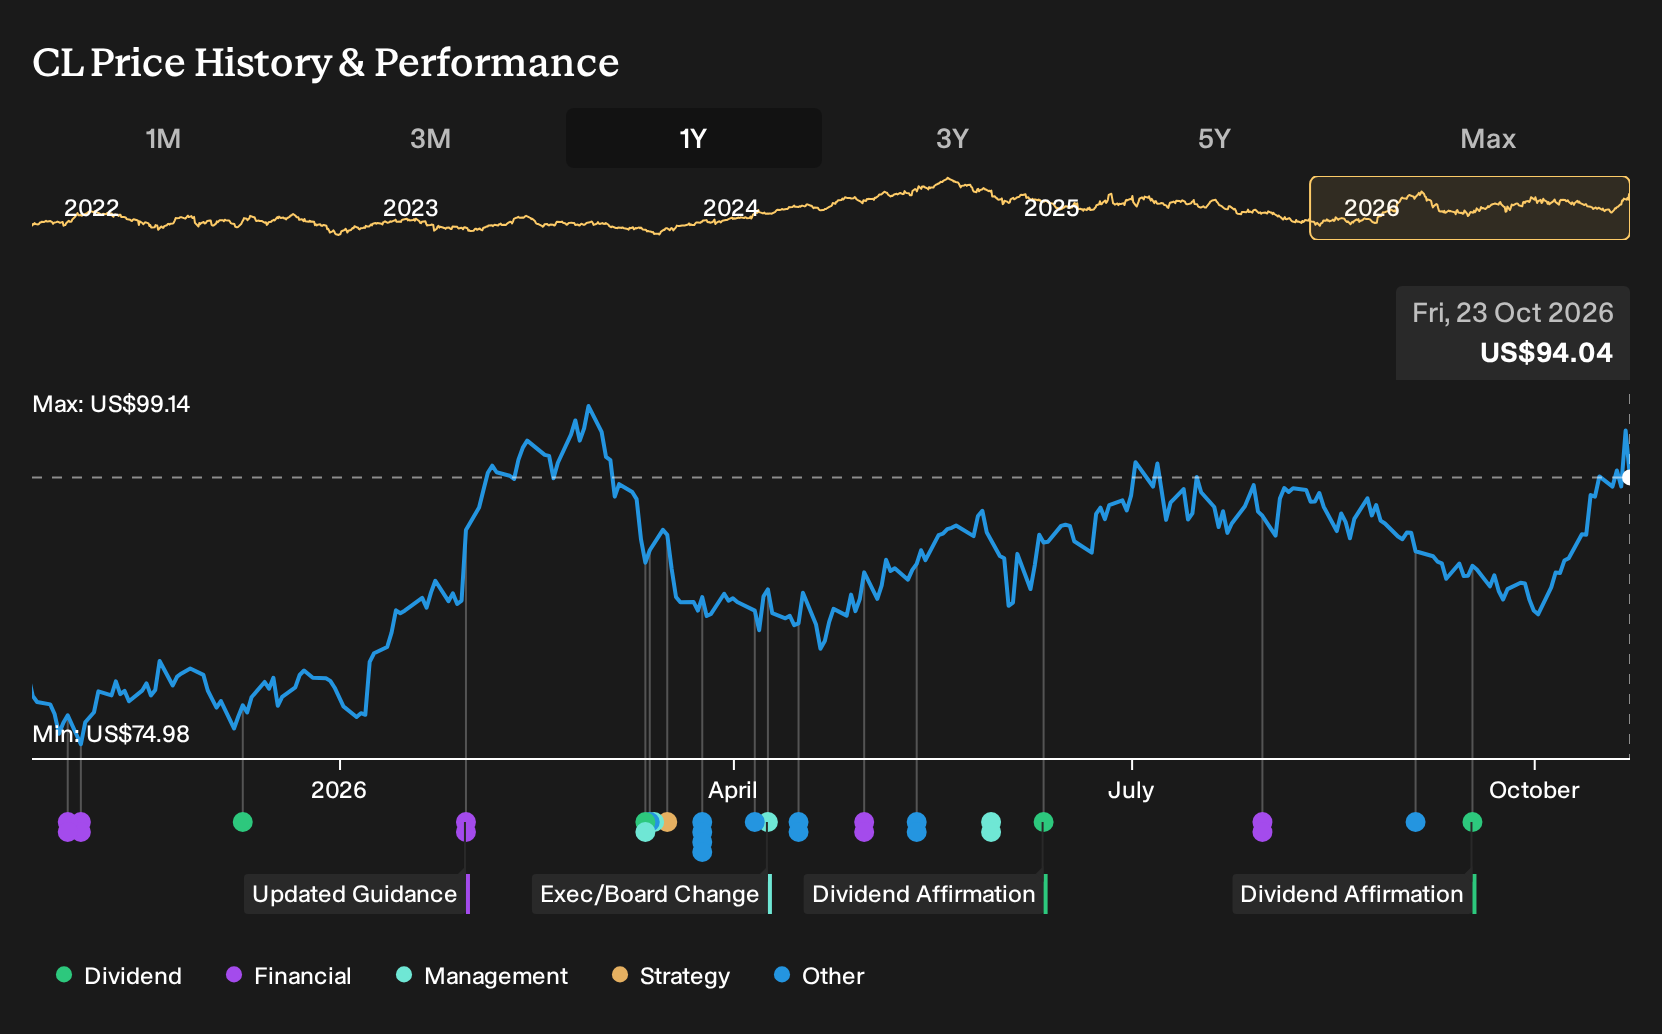
To own Colgate-Palmolive, you need to be comfortable with a steady branded consumer products story that leans on premium oral care, pet nutrition and strong positions in emerging markets. The short term focus sits on earnings delivery against expectations for the September 2026 quarter, especially after a recent earnings surprise that topped consensus.
The biggest operational risk right now is pressure on categories that already look soft in places like North America, Brazil and India, combined with margin sensitivity from legal and competitive costs. The Akash Parekh appointment is well telegraphed and internally sourced, so it does not materially change the near term earnings catalyst.
The most relevant data point tied to this marketing leadership news is the expectation for higher earnings on stronger revenue in the upcoming September quarter release on 30 October 2026. In the short term, the key question is whether Colgate-Palmolive can keep translating premium oral care and Hill’s Pet Nutrition into resilient profit despite softer category trends.
Analysts recently turned more optimistic on earnings, with the Most Accurate Estimate sitting above the broader consensus, but that remains a secondary input. The core operational test is execution. That means how well the business manages pricing, mix and advertising support in markets where competitive intensity is rising and category growth looks muted.
Colgate-Palmolive's narrative points to revenues of US$23.1b and earnings of US$3.4b by 2029, based on assumed 3.2% yearly top line growth and an earnings increase of about US$1.4b from US$2.0b today.
Uncover why Colgate-Palmolive's fair value indicates a 5% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$86 to US$128 per share, so some retail investors see Colgate-Palmolive as close to the low bucket while others price in much richer expectations. Set that beside category softness, legal overhangs, and premium oral care and pet food catalysts, then explore the full range of opinions.
Explore 3 other Colgate-Palmolive fair value estimates, including one that suggests as much as 8% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Colgate-Palmolive research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Colgate-Palmolive. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Colgate-Palmolive's overall financial health at a glance.
Looking For More Colgate-Palmolive Investment Ideas?
If you want to put Colgate-Palmolive in context, compare it with other opportunities that line up with your risk tolerance, income needs and time horizon. The Simply Wall St Screener can help you quickly narrow a huge universe of businesses down to a shortlist that fits how you actually invest.
- For investors who want income plus resilience, start with companies that appear built to keep paying, using a curated set of 5 dividend fortresses with strong yield profiles and durable operations.
- If capital preservation sits near the top of your priorities, focus on a hand picked group of 30 resilient stocks with low risk scores that score well on earnings quality and financial stability.
- To widen your opportunity set beyond well known giants like Colgate-Palmolive, scan a targeted pool of 21 high quality undiscovered gems that pair solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com