


How Investors May Respond To ABM Industries (ABM) Public Sector Contract Wins
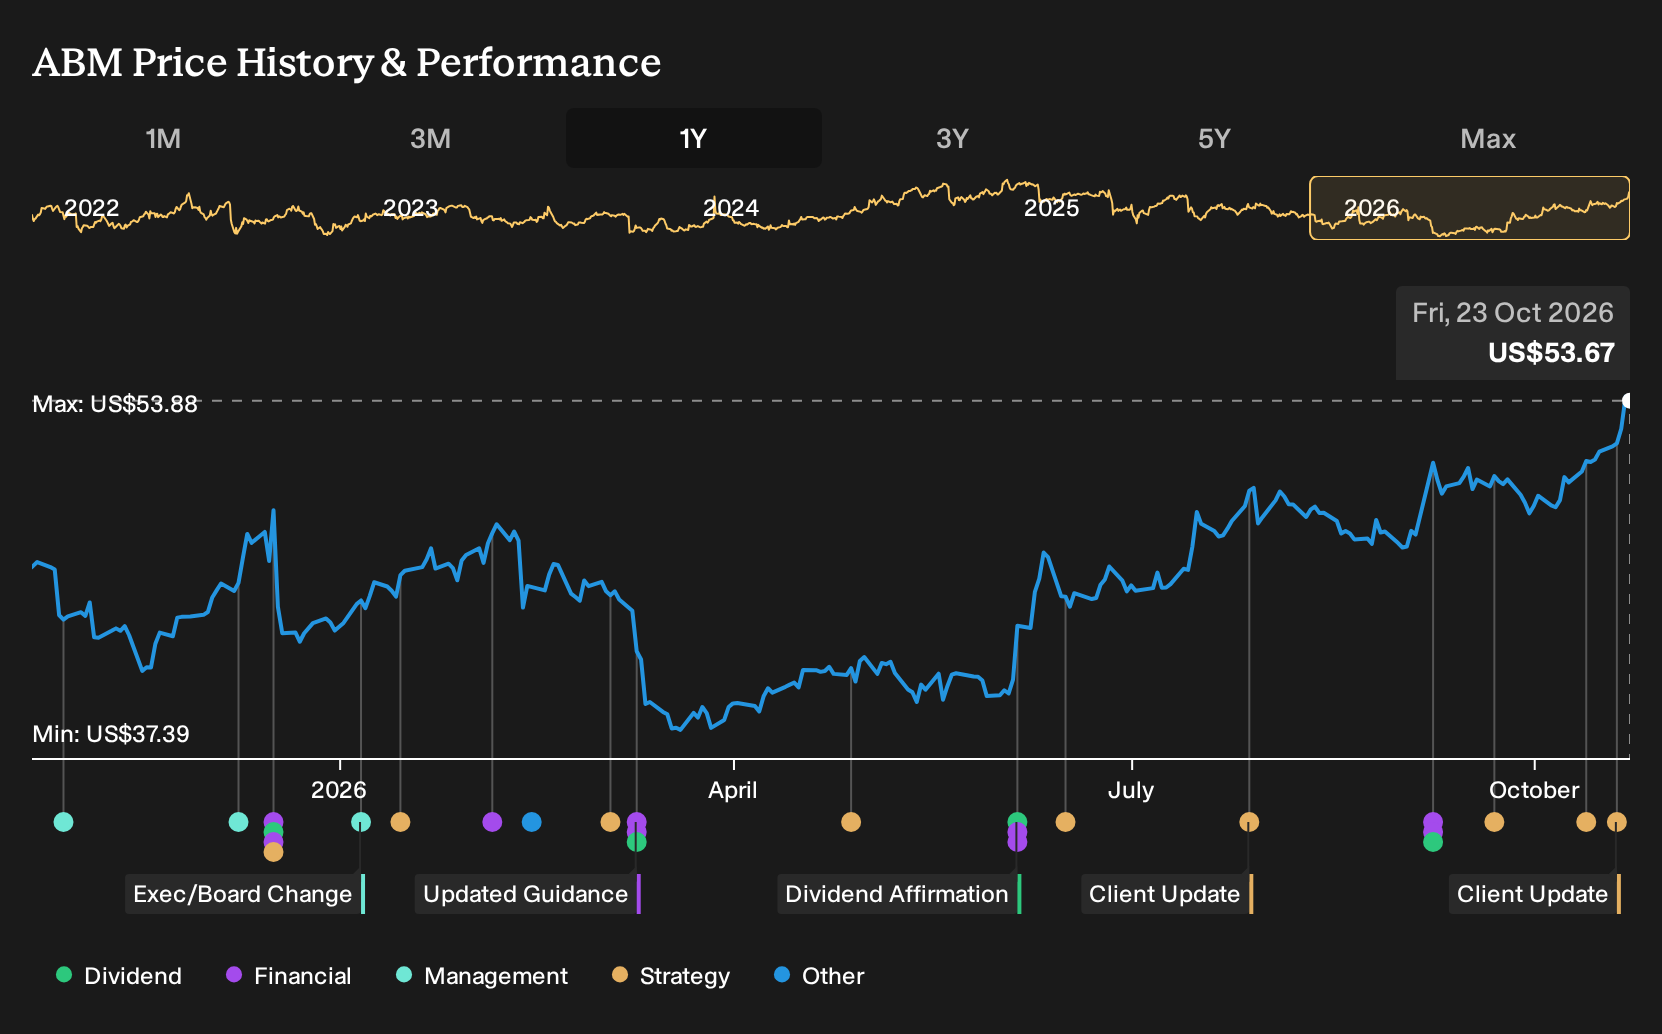
- ABM Industries recently extended its facilities services at SoFi Stadium and YouTube Theater and deepened its role supporting the Buffalo Bills’ new Highmark Stadium, while also securing appointments on the UK Government Commercial Agency’s Facilities Management and Security Services framework.
- These venue renewals and UK framework slots point to ABM Industries leaning further into long duration, operations heavy contracts that can support utilization of its engineering, janitorial, and security teams across both sports arenas and public sector estates.
- The focus now turns to how ABM Industries' push into public sector frameworks could influence the investment narrative around contract quality.
Scan how ABM Industries fits into the wider facilities and infrastructure story by lining it up against our curated 42 power grid technology and infrastructure stocks shaping the backbone of modern venues and public assets.
ABM Industries Investment Narrative Recap
For ABM Industries to make sense in a portfolio, you need to believe in a shift toward higher margin, technical infrastructure work while keeping large venue and janitorial contracts steady. The key short term swing factor is how efficiently that growing backlog in semiconductors, microgrids, and data centers converts into revenue at the margins already visible.
The biggest risk sits in contract quality and cash conversion. Record bookings in FY25 and FY26, plus ERP driven working capital gains, still need to show up as durable free cash flow once one off benefits fade. Recent stadium wins look positive for utilization, but do not materially change that core equation yet.
The UK Government Commercial Agency framework award looks most relevant here. It plugs ABM Industries directly into longer duration facilities management and security tenders for government departments, NHS bodies, schools, and emergency services. These customers often value continuity and operational resilience over rapid cost cutting.
For you as an investor, this matters because the framework can support a more predictable pipeline alongside the higher margin Technical Solutions work. Execution risk does not disappear. ABM still has to price contracts sensibly, staff complex estates, and protect margins while carrying a higher debt load. The announcement aligns with the existing contract quality catalyst rather than redefining it.
ABM Industries’ current consensus narrative points to revenues of US$10.1b and earnings of US$272.9m by 2029. That path assumes revenue growth of 3.3% a year and an earnings increase of roughly US$106.5m from US$166.4m today.
Discover how ABM Industries' fair value indicates a 4% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the lowest analysts focus less on stadium momentum and more on project volatility in Technical Solutions. They model slower top line progress, with ABM Industries reaching about US$9.9b of revenue and US$281.9m of earnings by 2029, yet on a softer 11.8x P/E. These views pre date the SoFi and Highmark wins, so your own take may shift as you weigh this fresh contract news.
Explore another ABM Industries fair value estimate, including one that suggests it could be worth just $55.93.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your ABM Industries research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ABM Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ABM Industries' overall financial health at a glance.
Looking For More Ideas Beyond ABM Industries?
Once you have a view on ABM Industries, it often helps to set that against alternatives. Use the Simply Wall St screener to line up different types of opportunities side by side and pressure test where ABM really earns a place in your portfolio.
- For investors hunting for strong returns with tighter risk controls, scan a curated group of 30 resilient stocks with low risk scores that may appeal if capital preservation sits high on your list.
- If steadier income matters more than excitement, compare ABM Industries with a set of 5 dividend fortresses that aim to balance yield with business resilience.
- For those who like to get in early on underfollowed stories, widen your research universe with 21 high quality undiscovered gems that might not yet be widely owned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com