


Welltower (WELL) Heads Into Earnings As Senior Housing Strength Shapes Its Valuation
Welltower (WELL) heads into its third quarter 2026 earnings report on October 26, with expectations for year over year gains in revenue and funds from operations, supported by firm demand in senior housing.
Recent trading tells a story of optimism building around Welltower. The share price has risen 2.6% over the past month and is up 27% year to date, while the 1 year total shareholder return sits at 35.3% and the 3 year total shareholder return is a little more than triple. This suggests investors have been steadily repricing the REIT as demand for senior housing and expectations for higher funds from operations reshape perceived risk and opportunity ahead of the upcoming earnings release.
Scan Welltower alongside other aging demographic plays by reviewing our hand picked 30 resilient stocks with low risk scores that pair resilient balance sheets with income focused real estate exposure.
Welltower now carries the profile of a strong senior housing platform and a stock that has already rewarded holders. The real question is whether today’s valuation fairly reflects that momentum or whether it stretches beyond it.
Most Popular Narrative: 9% Undervalued
Welltower last closed at $237.32, while the most followed narrative pegs fair value at about $262.05, using a 7.25% discount rate to weigh future cash flows and risk. That gap rests heavily on how effectively the senior housing platform converts strong demand and capital recycling into durable earnings power.
The main thing that has to go right is that Welltower continues to translate strong needs based senior housing demand and disciplined capital recycling into sustained high same store NOI growth from its senior housing operating portfolio without letting expense growth or governance concerns erode that progress.
See why 30 investors see Welltower as 9% undervalued.
Result: Fair Value of $262.05 (UNDERVALUED)
Still, the bullish Welltower narrative depends on smooth asset recycling and governance stability. Setbacks on either front could quickly challenge the current undervaluation case.
Find out about the key risks to this Welltower narrative.
Another View: What Multiples Say About Welltower
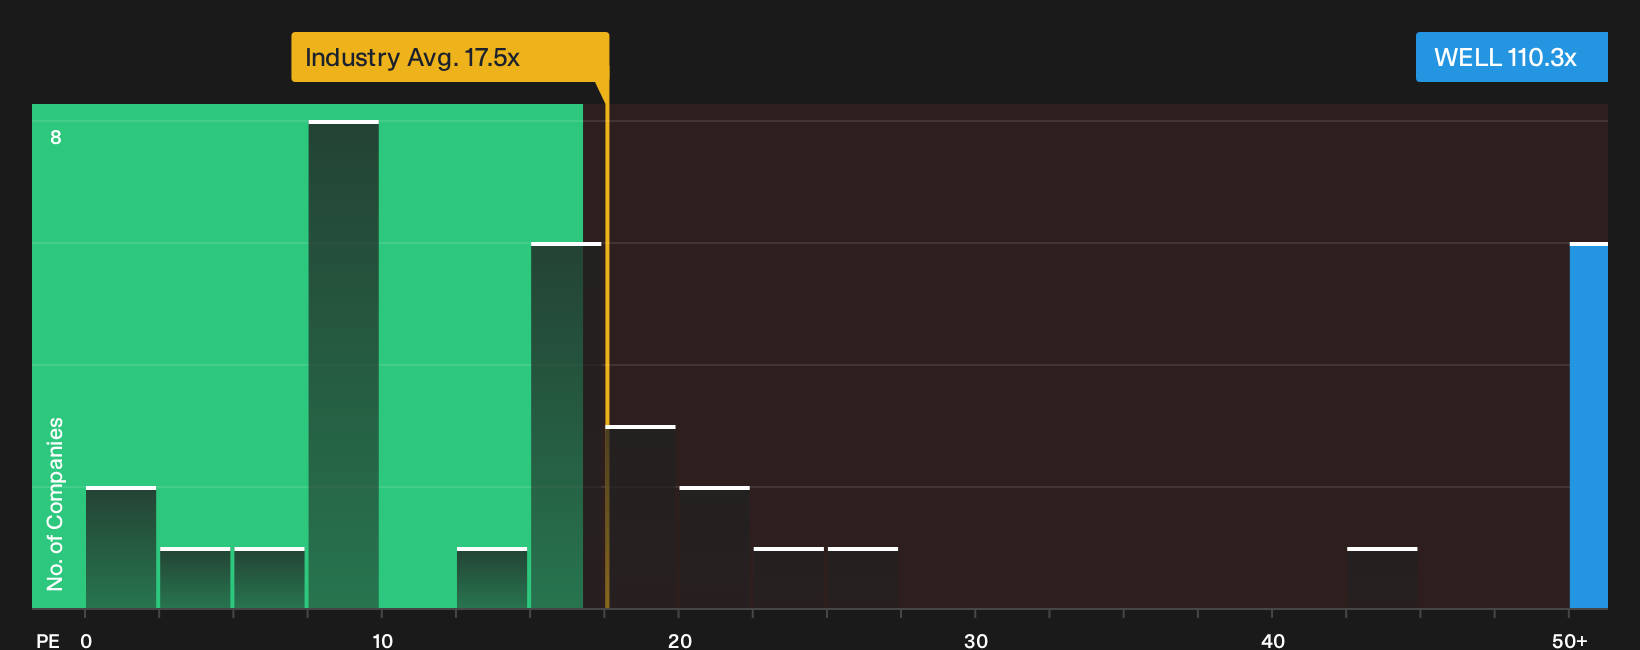
Look past the narrative fair value and the picture changes. Welltower trades on a P/E of 110.3x, compared with a fair ratio of 39.8x, the Global Health Care REITs average of 17.5x, and a peer average of 85.5x. That gap points to rich expectations that investors need to consciously accept or walk away from. Where do you land on paying up for this story?
See what the numbers say about this price in more detail in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Welltower is clearly split, with real strengths drawing interest and flagged issues keeping some investors cautious, so move quickly and test the data against your own risk tolerance. To weigh both sides in one place, start with 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Welltower?
If Welltower has sharpened your thinking, keep that momentum going by lining up a few fresh watchlist candidates before the next wave of headlines hits.
- Target resilient income by reviewing a hand picked pool of high yield opportunities in our 5 dividend fortresses so you are not relying on one landlord for cash flow.
- Hunt for mispriced strength and let the data surface 29 high quality undervalued stocks that pair solid fundamentals with valuations that still leave room for your own thesis.
- Protect your downside first and scan a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions while you focus on upside potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com