


East West Bancorp (EWBC) Could Be 13% Undervalued Following Raised NII Guidance
East West Bancorp (EWBC) drew investor attention after reporting higher net interest income and earnings for the third quarter of 2026, and lifting full year NII growth guidance to 9% to 10%.
Despite the guidance upgrade and higher earnings, East West Bancorp’s share price slipped 1.1% on the day to US$131.19, although the 7 day and 30 day share price returns of 3.4% and 3.1% suggest momentum has been rebuilding. Over a longer horizon, total shareholder return of 31.3% over 1 year and 170.1% over 3 years indicates that investors have been steadily re-rating the business over time.
Scan banks with similar momentum and balance sheet strength to East West Bancorp by focusing on our curated list of list of solid balance sheet and fundamentals (24 results).
After that muted share price reaction, East West Bancorp now trades at a clear discount to both analyst targets and certain intrinsic value estimates. The question for investors is where fair value actually sits within that range.
Most Popular Narrative: 12.5% Undervalued
On the most followed valuation view, East West Bancorp’s fair value of $150 sits meaningfully above the recent $131.19 close. This puts the focus squarely on what needs to keep working in the underlying business to support that gap.
The main thing that has to go right is that East West Bancorp continues to grow its relationship-driven, small-business-focused noninterest-bearing deposits while holding credit quality and capital at current strong levels.
Very strong capital levels and efficiency, with East West Bancorp generating mid to high teens return on tangible common equity on a tangible common equity ratio above 10% and maintaining a sub 40% efficiency ratio, give it room to keep funding organic growth initiatives and product expansion that can support future earnings.
See why 25 investors see East West Bancorp as 13% undervalued.
Result: Fair Value of $150 (UNDERVALUED)
Still, two pressure points could unsettle that 12.5% undervalued narrative for East West Bancorp: rising deposit competition and choppy fee income quarter to quarter.
Find out about the key risks to this East West Bancorp narrative.
Another View: What East West Bancorp’s P/E Is Telling You
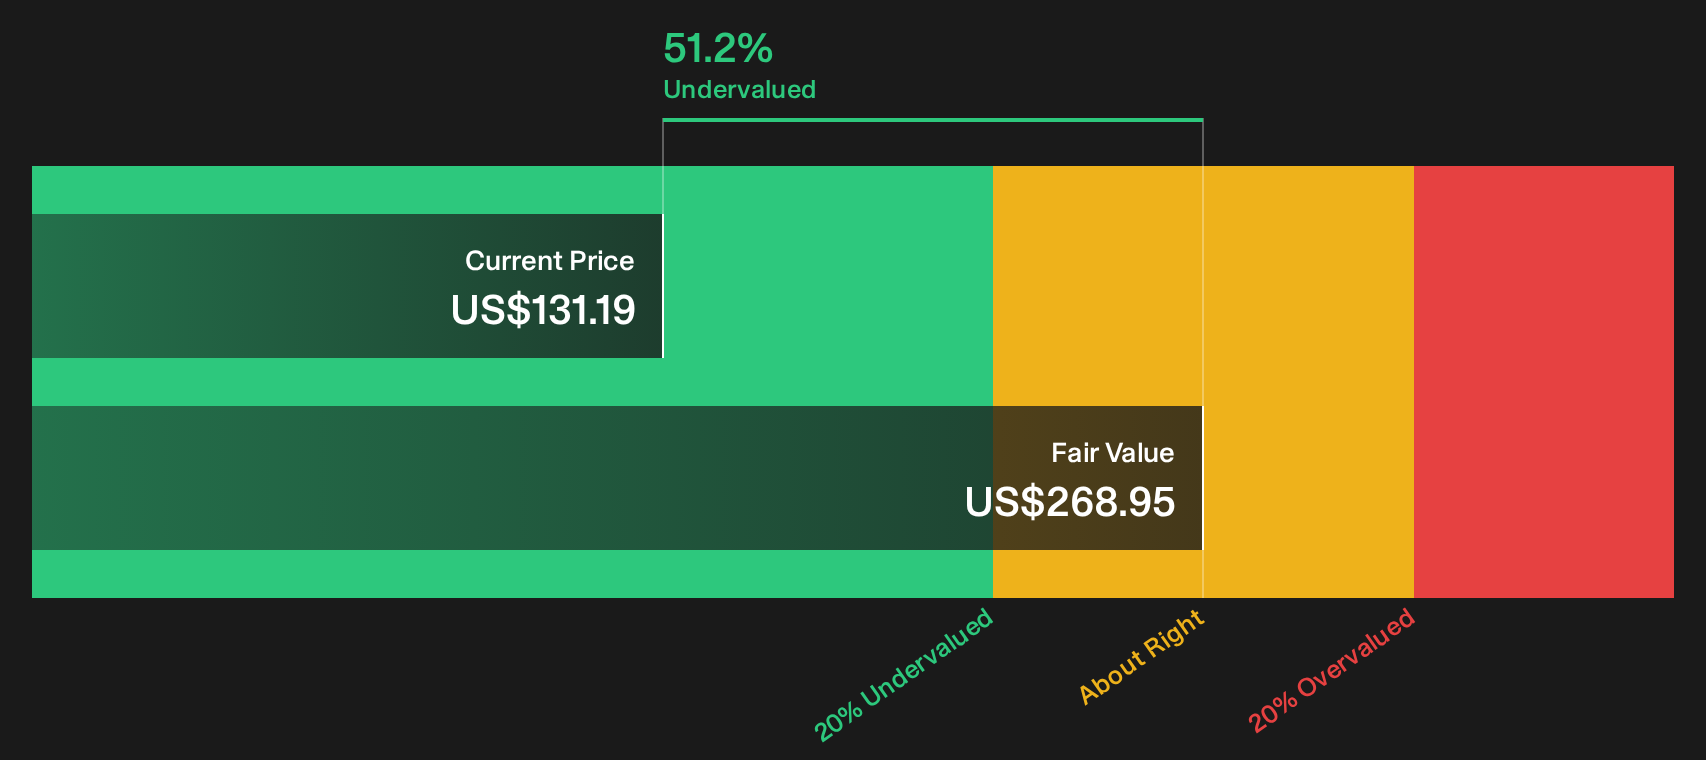
The SWS DCF model points to East West Bancorp trading 51.2% below an estimated future cash flow value of $268.95, which implies a wide margin between price and intrinsic worth. That sits beside a current P/E of 12.3x, only slightly below the fair ratio of 12.6x and above the US Banks industry at 11.6x. How much weight do you put on the cash flow signal when the earnings multiple already prices in a lot of good news?
For a closer look at how this cash flow view is built and where the sensitivities lie, take a moment to review the Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around East West Bancorp can either sharpen conviction or create second thoughts. Look through the full picture yourself and weigh both sides by checking the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond East West Bancorp?
If East West Bancorp has sharpened your thinking, do not stop here. Use Simply Wall Street’s screener to uncover fresh ideas that match your style.
- Target potential value opportunities before the crowd by running through the 29 high quality undervalued stocks that filters for quality at attractive prices.
- Prioritize resilience and capital preservation by reviewing the 30 resilient stocks with low risk scores focused on businesses with more robust risk profiles.
- Hunt for future leaders that are still under the radar by scanning the 21 high quality undiscovered gems with stronger fundamentals than their attention suggests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com