


Is Vertex Pharmaceuticals (VRTX) A Bargain After Its Phase 3 Kidney Trial Win?
Vertex Pharmaceuticals (VRTX) just put its kidney program in the spotlight after reporting Phase 3 RAINIER data for povetacicept in IgA nephropathy, with strong proteinuria reduction and a New England Journal of Medicine publication.
Vertex Pharmaceuticals shares trade at US$523.93, with the 7-day share price return up 4.84% and the 90-day share price return up 9.38%. The 1-year total shareholder return of 24.33% and 5-year total shareholder return of 183.31% point to momentum that has built over time rather than faded.
Scan the kidney and rare disease space for more potential movers by checking out 21 high quality undiscovered gems in addition to Vertex Pharmaceuticals’ latest IgA nephropathy breakthrough.
Vertex Pharmaceuticals now has a high-value kidney story sitting on top of an already profitable rare disease portfolio. After this latest move in the share price, are investors paying a fair price for that package today?
Most Popular Narrative: 8% Undervalued
On the most followed view of Vertex Pharmaceuticals, the stock trades below an estimated fair value of $571.39 compared with the last close at $523.93. That gap rests on the idea that the kidney and endocrinology push can steadily reshape earnings power over time.
Expansion of the renal disease portfolio, including late stage programs like povetacicept in IgA nephropathy with what management describes as best in class numerical reductions in proteinuria and favorable auto injector dosing, and inaxaplin in APOL1 mediated kidney disease with significant UACR reductions and an interim 1 year eGFR readout planned in early 2027, is supported by growing regulatory acceptance of proteinuria and 1 year eGFR endpoints. This could support future revenue and earnings from a new disease area.
See why 140 investors see Vertex Pharmaceuticals as 8% undervalued.
Result: Fair Value of $571.39 (UNDERVALUED)
Still, the Vertex Pharmaceuticals story could change quickly if cystic fibrosis pricing outside the US tightens further or if the Crinetics acquisition proves harder to integrate than hoped.
Find out about the key risks to this Vertex Pharmaceuticals narrative.
Another View: Vertex Pharmaceuticals Through The P/E Lens
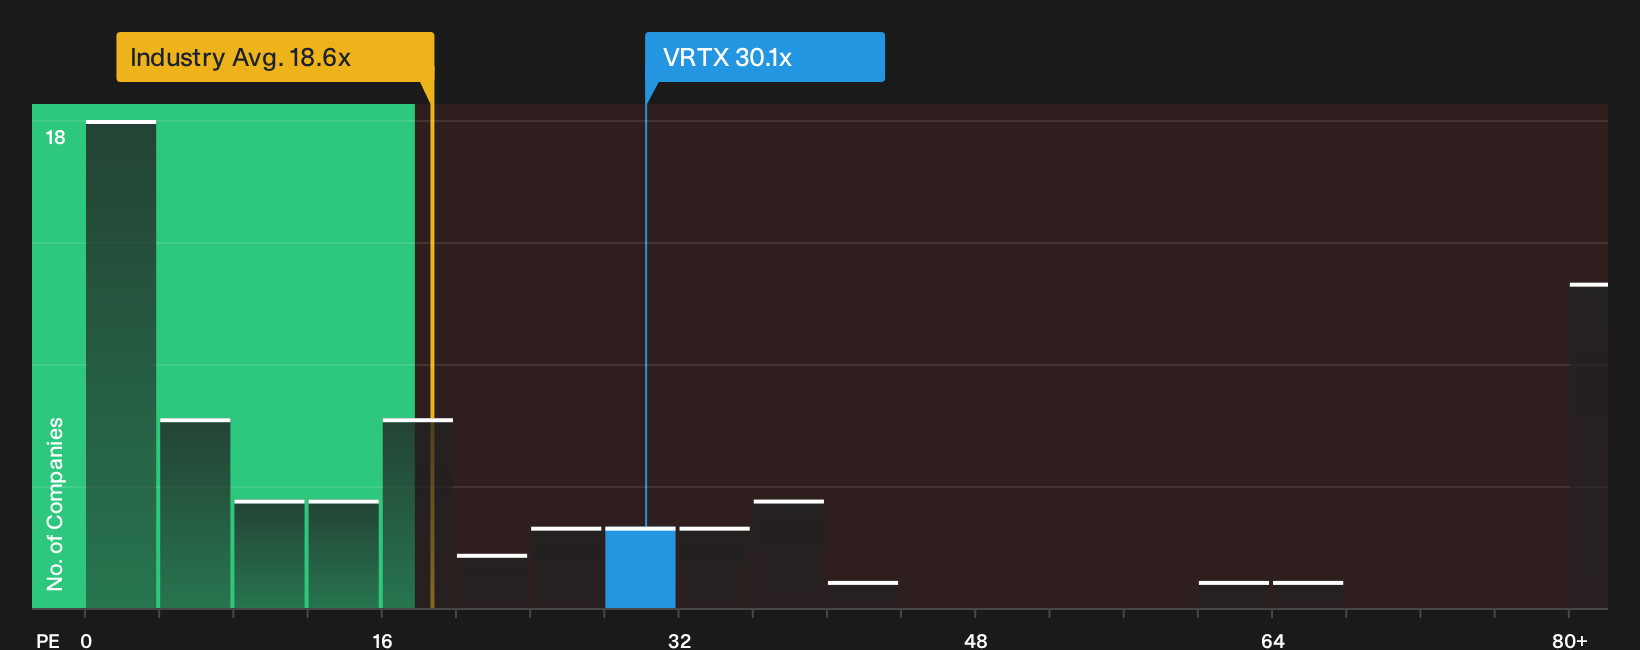
There is a different read on Vertex Pharmaceuticals when the focus shifts from fair value models to the plain P/E number. The shares trade on 30.1x earnings, above the US Biotechs average of 18.6x, yet below a fair ratio estimate of 33x, which highlights both valuation risk if sentiment cools and a potential opportunity if earnings continue to align with expectations.
If you prefer to anchor your work on simple earnings multiples, it is worth looking at how this pricing gap and the fair ratio compare with peers in detail. You can do this through See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Feeling upbeat about the Vertex Pharmaceuticals story or still on the fence? Take a close look at the numbers yourself, pressure test the assumptions, then weigh those against 3 key rewards.
Looking for more Vertex Pharmaceuticals investment ideas?
Do not stop with a single stock story. Use the Simply Wall Street screener to uncover fresh opportunities and build a watchlist that actually fits your style.
- Target future compounders by scanning companies that combine quality fundamentals with attractive pricing through the 29 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with robust finances using the list of solid balance sheet and fundamentals (24 results).
- Balance risk and opportunity by filtering for steadier performers through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com