


What’s Behind Smoore International Holdings (SEHK:6969) Latest Move?
Smoore International Holdings (SEHK:6969) has kicked off a sizeable share repurchase program covering up to 10% of its issued capital after releasing its latest quarterly and nine month earnings update.
Short term momentum for Smoore International Holdings has been soft, with the 30 day share price return down 9.81%, the year to date share price return down 30.77%, and the 1 year total shareholder return down 38.27%. However, the 3 year total shareholder return of 47.53% indicates earlier gains that recent weakness has eroded.
Spot opportunities that echo Smoore International Holdings' buyback and earnings story by scanning our curated list of 196 high quality undervalued stocks with resilient cash generation and solid balance sheets.The buyback and the latest profit figures send mixed signals. Is Smoore International Holdings leaning on sentiment, or does the current share price sit below what the underlying business performance supports?
Most Popular Narrative: 34% Undervalued
On the most followed narrative, Smoore International Holdings screens as undervalued, with a fair value of HK$12.61 against the last close at HK$8.37. This represents a wide gap that hinges on how sustainable its growth drivers really are.
The company is strategically investing in R&D for high-growth areas such as Heat-Not-Burn (HNB) products, beauty atomization, inhalation therapy, and special purpose atomization. These areas are expected to drive future revenue growth as the segments mature. Smoore is taking advantage of regulatory developments in Europe and the U.S. to adapt and develop compliant products, which could help stabilize and grow its market presence and support future revenue streams.
See why 2 investors see Smoore International Holdings as 34% undervalued.
Result: Fair Value of HK$12.61 (UNDERVALUED)
Still, the narrative around Smoore International Holdings can unwind quickly if tighter e cigarette rules bite harder than expected, or if a major customer pulls back orders.
Find out about the key risks to this Smoore International Holdings narrative.
Another View On Smoore International Holdings Valuation
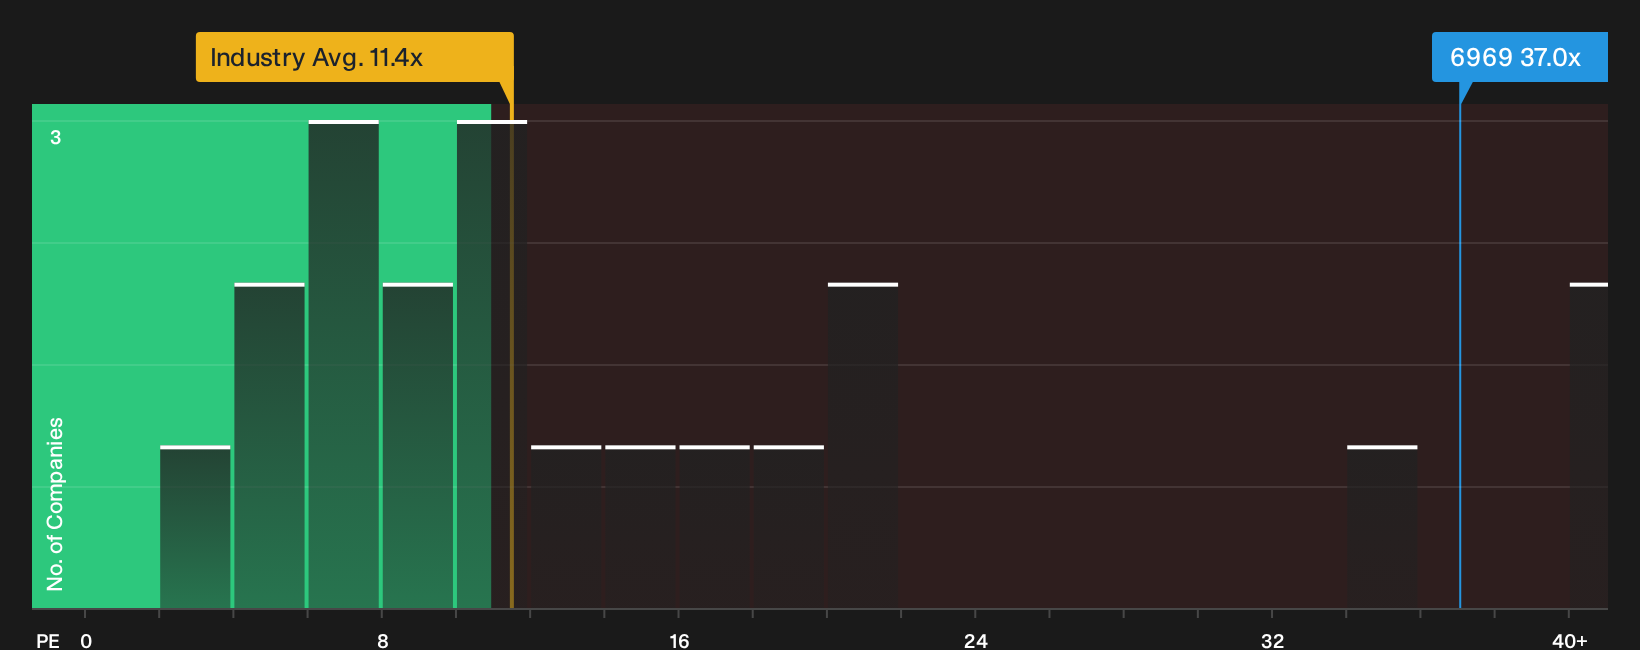
That popular 34% undervalued story leans on growth forecasts and a HK$12.61 fair value, yet Smoore International Holdings trades on a P/E of about 37x. The broader Asian Tobacco group sits near 11.4x, while the fair ratio points to 21.6x. That gap suggests investors are paying up, so the key question is whether the optimism is already priced in.
To see how those valuation gaps stack up in detail, including where the current P/E sits against the fair ratio and peers, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed story so far, right, with Smoore International Holdings showing both pressure and promise that pull sentiment in different directions. Act quickly, review the detailed data yourself, and weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Smoore International Holdings?
If you only stop at Smoore International Holdings, you could miss other setups that fit your goals even better. Cast a wider net and put more quality options on your radar.
- Spot potential turnaround candidates early and size positions with care by scanning the 123 elite penny stocks with strong financials that pair higher risk with stronger balance sheets and cash flows.
- Target mispriced opportunities with solid fundamentals by reviewing the curated 196 high quality undervalued stocks that already combine quality metrics with attractive valuations.
- Prioritise resilience and capital protection by focusing on the 222 resilient stocks with low risk scores that score well on financial health and volatility checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com