


Why Lumen Technologies (LUMN) Has Investors Watching Its Latest Move
Lumen Technologies (LUMN) has drawn fresh attention after rolling out new AI-driven tools for network resilience and launching Dual Path, a wavelength service built around physically diverse routes for enterprise connectivity.
These AI-driven launches arrive after a tough stretch for Lumen Technologies’ equity, with the 30-day share price return down 19.96% and the year-to-date share price return down 40.57%. At the same time, the three-year total shareholder return is roughly 3.5x, and recent product and partnership news may be starting to reshape how investors view both the firm’s risk profile and its longer term potential.
Scan beyond Lumen Technologies and line up other AI infrastructure plays moving on similar themes with the 55 AI infrastructure stocks in one place.
Lumen Technologies now sits at an awkward crossroads. The network story is getting louder while the share price has been sliding. The key question is whether it makes more sense to step in here or wait for a cleaner entry based on upcoming numbers.
Most Popular Narrative: 39% Undervalued
Lumen Technologies last closed at $4.57 while the most followed valuation narrative points to a fair value of $7.49. That gap raises a direct question for you about whether current pricing already reflects execution risks in AI infrastructure and debt restructuring.
Lumen's large pipeline of AI-driven network infrastructure and Platform Connectivity Fiber (PCF) contracts, particularly with hyperscalers and data center providers, positions the company to capture long-duration, higher-margin recurring revenues from explosive data growth, benefiting long-term revenue and margin expansion.
See why 62 investors see Lumen Technologies as 39% undervalued.
On these narrative assumptions, the stock is treated as trading at a sizeable discount to modeled value, supported by a 9.43% discount rate and revenue that analysts currently expect to decline at roughly 4.1% a year. That setup leans heavily on Lumen Technologies eventually lifting margins from a current loss of $1.0b to earnings of $923.7m by around 2029 to close the gap between today’s share price and the $7.49 fair value line.
Result: Fair Value of $7.49 (UNDERVALUED)
Still, the narrative around Lumen Technologies can shift quickly if legacy services keep shrinking faster than expected, or if heavy debt and refinancing needs start to squeeze flexibility.
Find out about the key risks to this Lumen Technologies narrative.
Another View: SWS DCF Flags Less Upside
The narrative around Lumen Technologies leans on analyst targets that imply upside. The SWS DCF model presents a cooler view, with an estimated future cash flow value of $4.09 compared with the current $4.57 share price. That comparison points to the stock trading above that intrinsic estimate. Which lens do you trust more when cash flows, not headlines, call the shots?
For a closer look at how that cash flow estimate is built and what would need to change for the picture to improve, Look into how the SWS DCF model arrives at its fair value..
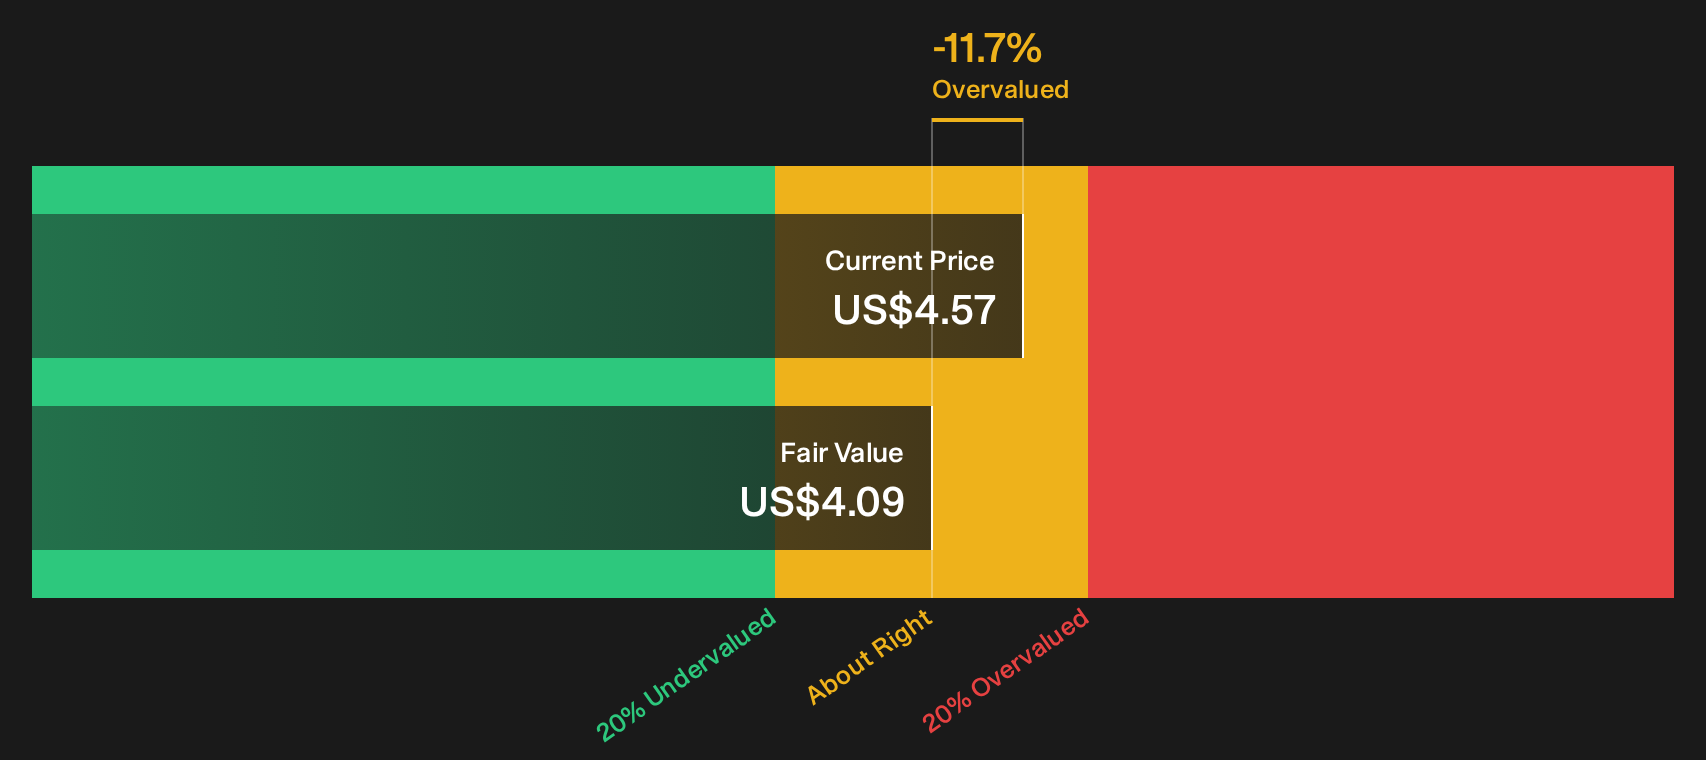
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lumen Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Lumen Technologies can feel confusing. Move quickly to test the assumptions against the data and decide where you stand using 2 key rewards and 2 important warning signs.
Looking for more Lumen Technologies investment ideas?
If you only focus on Lumen Technologies, you risk missing other opportunities that could fit your goals even better. Use the Simply Wall St screener to quickly pressure test fresh ideas against the same numbers driven logic used here.
- Target resilient upside by scanning a curated 29 high quality undervalued stocks that combines quality fundamentals with pricing that still sits below intrinsic estimates.
- Prioritise staying power by reviewing a list of solid balance sheet and fundamentals (24 results) that can better handle pressure when conditions turn against weaker peers.
- Get ahead of the crowd by combing through a 21 high quality undiscovered gems that most investors are not yet watching closely.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com