


Should Long Term Federal Contracts Require Action From Leonardo DRS (DRS) Investors?
- Leonardo DRS secured a 10 year NASA SEWP VI prime contract, new U.S. defense awards including a $500 million JIATF 401 IDIQ, and fresh Army thermal sight and sensing work, along with launching its cxMHR radar into initial production.
- These long duration contracts and new radar and infrared programs expand Leonardo DRS’s visibility on future government technology demand and operational workload across multiple business units.
- The discussion now turns to how Leonardo DRS’s investment narrative is shaped by the 10 year NASA SEWP VI award and related contracts.
Scan similar defense and government-tech plays by running your eye over 55 AI infrastructure stocks, which could also benefit from long-duration contracts and critical mission systems demand.
Leonardo DRS Investment Narrative Recap
To own Leonardo DRS, you need to believe its heavier R&D and capex in radars, infrared and naval power can keep translating into funded programs rather than one off contract spikes. The NASA SEWP VI award, alongside recent Army and JIATF work, gives the business more visibility on potential orders but does not remove execution risk on those investments.
In the near term, the key catalyst is how effectively management converts SEWP VI access and new sensing programs into steady task orders that support backlog and margins. The biggest risk is that prior patterns of slower revenue growth and softer backlog return, which would make that higher spend level feel heavier on free cash flow.
The NASA SEWP VI contract is the announcement that really ties this story together. It extends Leonardo DRS’s position as a prime contractor through 2036 and keeps 368 vetted products and services accessible to a wide range of federal buyers, from the Army and Navy to the Defense Logistics Agency and Foreign Military Sales customers.
That government wide vehicle does not guarantee volumes or pricing. However, it helps shorten sales cycles and keeps DRS’s technology in the conversation for IT, sensing, computing and services task orders. For investors watching catalysts, the focus now is on order flow through SEWP VI versus the heavier R&D and capex bill already running through the income statement.
Leonardo DRS is essentially being modeled as a steady compounder. Consensus numbers imply revenues of $4.6b and earnings of $458.3m by 2029, based on 7.1% yearly top line growth and an earnings increase of about $136m from $322.0m today.
Uncover why Leonardo DRS' fair value indicates a 56% potential upside to its current price, which could narrow quickly.
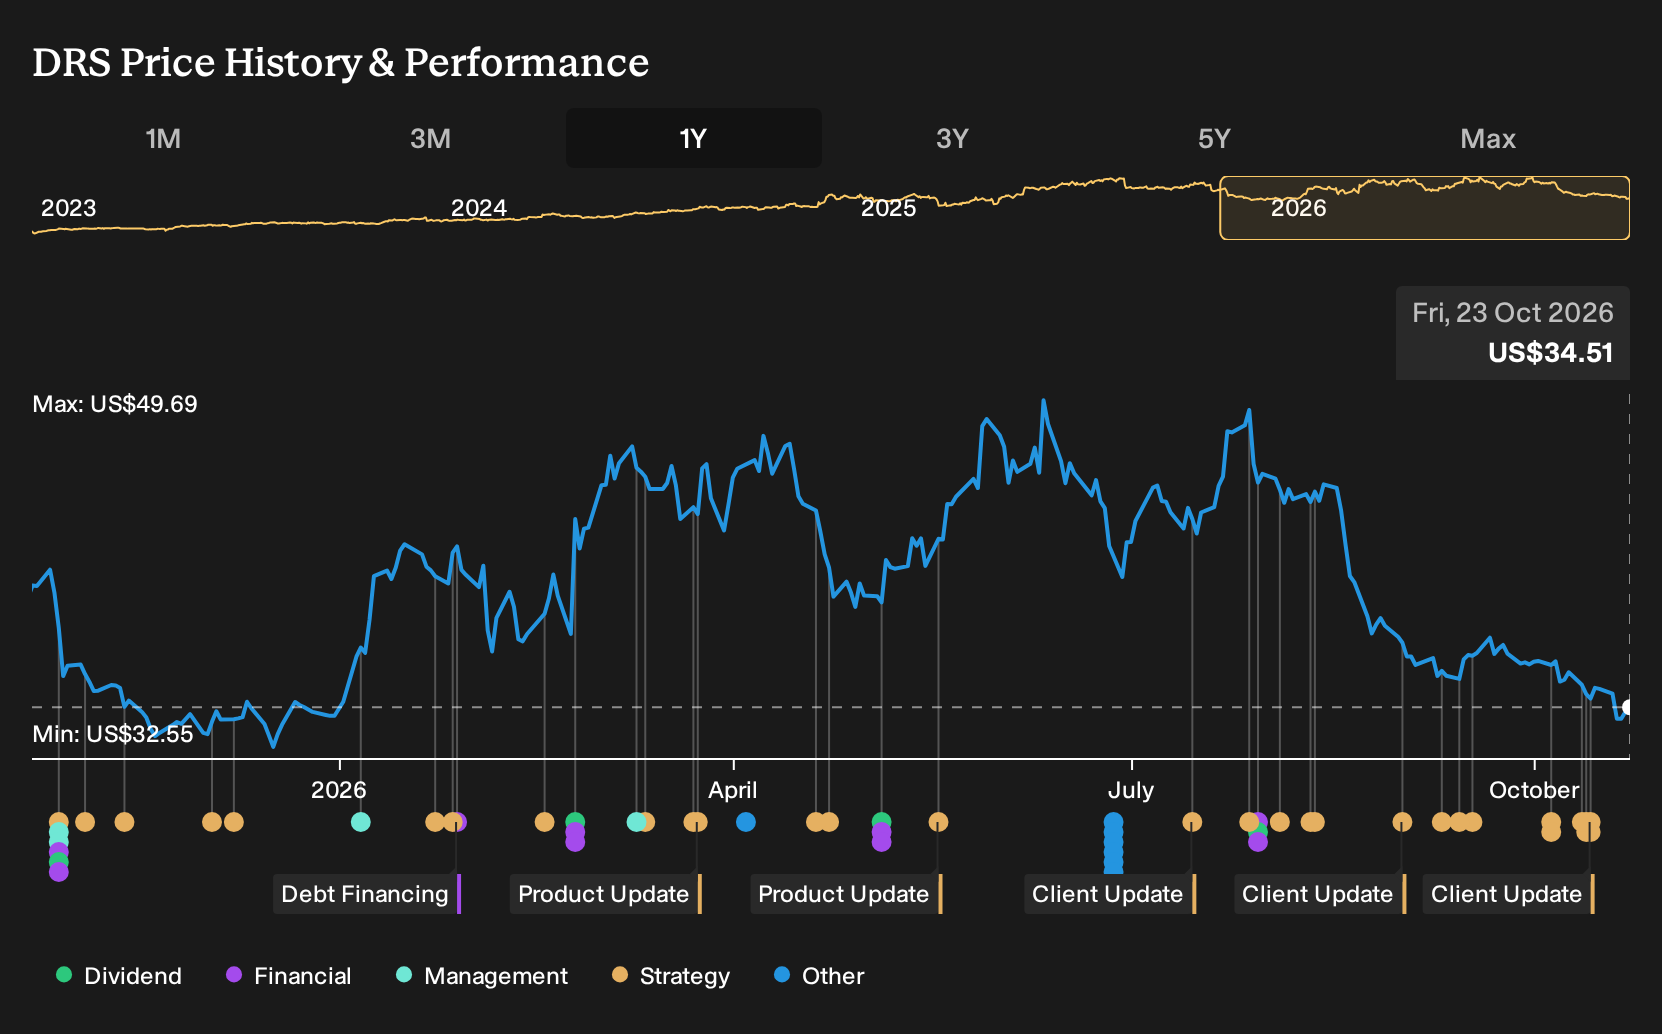
Exploring Other Perspectives
One alternate view treats the NASA SEWP VI award as a potential acceleration point. The most optimistic analysts were already modelling roughly 8.8% annual revenue growth and earnings of about $479.0 million by 2029 before this news. Opinions clearly differ widely. This fresh contract news could shift those expectations again.
Explore 4 other Leonardo DRS fair value estimates, including one that suggests there could be as much as 71% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Leonardo DRS research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Leonardo DRS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Leonardo DRS' overall financial health at a glance.
Looking for more investment ideas beyond Leonardo DRS?
If you want to stress test your Leonardo DRS thesis, comparing it with other opportunities is a smart next step. The Simply Wall St Screener can help you quickly filter for different styles of opportunities so you can see where this defense contractor fits in your wider watchlist.
- If you care most about resilient balance sheets and fundamentals, start with a list of solid balance sheet and fundamentals (24 results) to see how quality-focused businesses stack up.
- If value is your priority, line Leonardo DRS up against our 29 high quality undervalued stocks and see which other stocks currently screen as potentially mispriced based on their underlying numbers.
- If you prefer to hunt for less crowded opportunities, scan through a 21 high quality undiscovered gems and compare those quieter ideas with what you see in Leonardo DRS.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com