


Western Digital (WDC) Stock Trades At a Discount to Its Earnings
Western Digital has turned into one of the strongest performers in the memory sector in recent years, which puts a spotlight on whether the current share price around US$343.67 is still aligned with what its earnings can support. After such a powerful run and fresh headlines around AI driven storage demand, the core question for you is whether those profits justify where the stock trades today.
- Over the past 3 years the stock has delivered a very large gain of about 11x, which raises the stakes on whether its earnings profile has evolved enough to back that kind of rerating.
- Recent results tied to high capacity storage for AI and cloud workloads, along with higher shareholder payouts, suggest investors are now keying off how durable profit margins and cash generation from that AI driven demand may be.
- Your read on Western Digital is one view; the desks covering it have another. See what analysts think Western Digital's shares could be worth.
The issue now is whether Western Digital's earnings are strong and durable enough to make the current valuation look sensible at this price.
If you want to stress test this same earnings question beyond Western Digital and across a basket of AI related infrastructure plays, it is worth scanning 55 AI infrastructure stocks.
Is Western Digital a Bargain on Earnings?
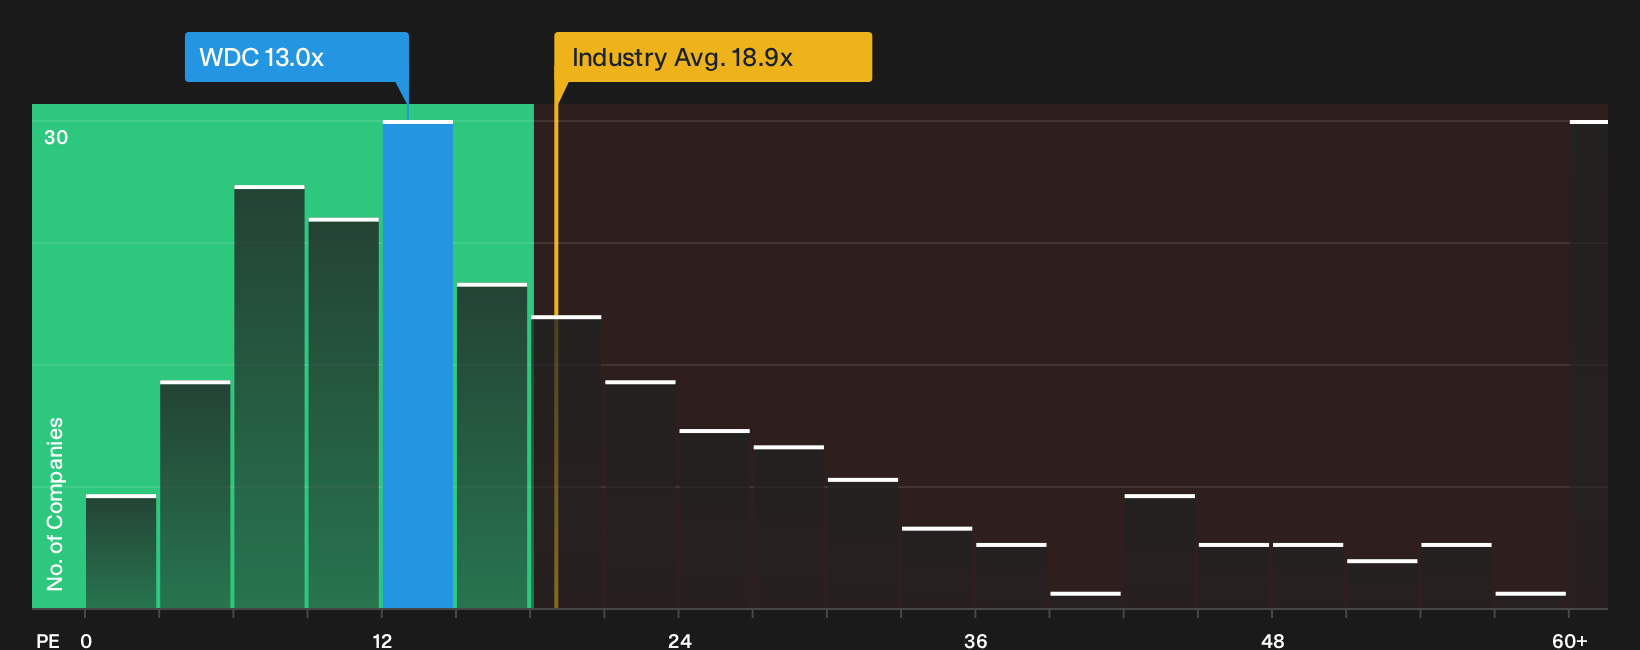
The P/E ratio works well for Western Digital because earnings are now a key focus after the recent AI storage driven surge. At roughly 13.0x earnings, the stock trades at a clear discount to both the wider tech sector on about 18.9x and a peer set closer to 28.6x. That gap suggests investors are not paying the same headline price for each dollar of Western Digital profit as they are for comparable chip and hardware names.
Because the firm specific fair P/E that blends growth, margins, size and risk points to a higher level than today’s multiple, the stock screens as undervalued on this earnings yardstick. Despite the strong fiscal 2027 Q1 beat and raised dividend, the current P/E still prices Western Digital below where this framework would place it if recent profitability proves sustainable. Explore the numbers behind Western Digital's P/E valuation.
The Western Digital Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Western Digital pick up where the valuation puzzle leaves off by spelling out which earnings, margin and growth paths would need to play out for the stock to be worth materially more or less than it is today on Western Digital's Community page. Where a single ratio or model gives one neat number, these storylines unpack the future that number relies on so you can watch whether those assumptions actually show up in the company’s results over time.
Western Digital bulls see far more earnings power in today’s price than the cautious side is willing to give credit for.
Bull case: 47% undervalued
"The current valuation suggests Western Digital is priced below what might be implied by its reported margins, free cash flow generation, and its capacity for share repurchases and dividends…"
Discover why this Narrative puts Western Digital at 47% undervalued.
Bear case: roughly fairly valued
"Here is the tension. That golden hour is priced as if it lasts…"
Explore why this Narrative puts Western Digital at roughly fairly valued.
One more Western Digital check that sits next to the share price
Before you lean too heavily on Western Digital's earnings and multiples, it is worth asking who is steering the ship and how their incentives line up with yours. See who runs Western Digital and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com