


Is Medpace Holdings (MEDP) Fully Valued After Its Q3 Earnings Beat?
Medpace Holdings (MEDP) has attracted fresh attention after its Q3 2026 report, with revenue of US$716 million and net income of US$137.46 million, alongside reaffirmed full year guidance and solid new business trends.
On the back of these Q3 results, Medpace Holdings has seen a clear pick up in momentum, with a 1 month share price return of 8.13% and a 90 day move of 13.54%. The 3 year total shareholder return of 167.38% and 5 year total shareholder return of 195.39% show how long term holders have already experienced a very strong run.
Spot opportunities beyond Medpace Holdings by scanning a curated 21 high quality undiscovered gems that reflect the same strong execution and investor interest driving this latest earnings reaction.After that run and a fresh US$1b buyback authorization, the real tension for Medpace Holdings is simple: Is most of the upside already priced in, or does the current valuation still leave meaningful room ahead?
Most Popular Narrative: 24.8% Overvalued
On Simply Wall St, the leading narrative for Medpace Holdings pegs fair value at $536 against a last close of $669.20. As a result, the story being told in that thesis leans toward a rich price tag relative to intrinsic value.
Medpace appears to be a high-quality CRO because it combines a differentiated small-biotech focus, strong therapeutic expertise, a global full-service platform, operating margins above 20%, low capital requirements, substantial cash and no funded debt.
The balanced conclusion is less promotional than “dominates a profitable niche.” Medpace has built a strong position in a difficult-to-replicate part of the CRO market, but its revenue is not locked in, its customers can be financially fragile, and founder control brings related-party governance considerations. At around 35 times management’s 2026 earnings guidance, the business quality is evident. The margin of safety in the share price is less obvious.
See why 7 investors see Medpace Holdings as 25% overvalued.
Result: Fair Value of $536 (OVERVALUED)
Still, the Medpace Holdings story could shift quickly if small biotech clients struggle to fund trials, or if cancellations start to eat into that US$3.01b backlog.
Find out about the key risks to this Medpace Holdings narrative.
Another View: What Medpace’s P/E Is Really Saying
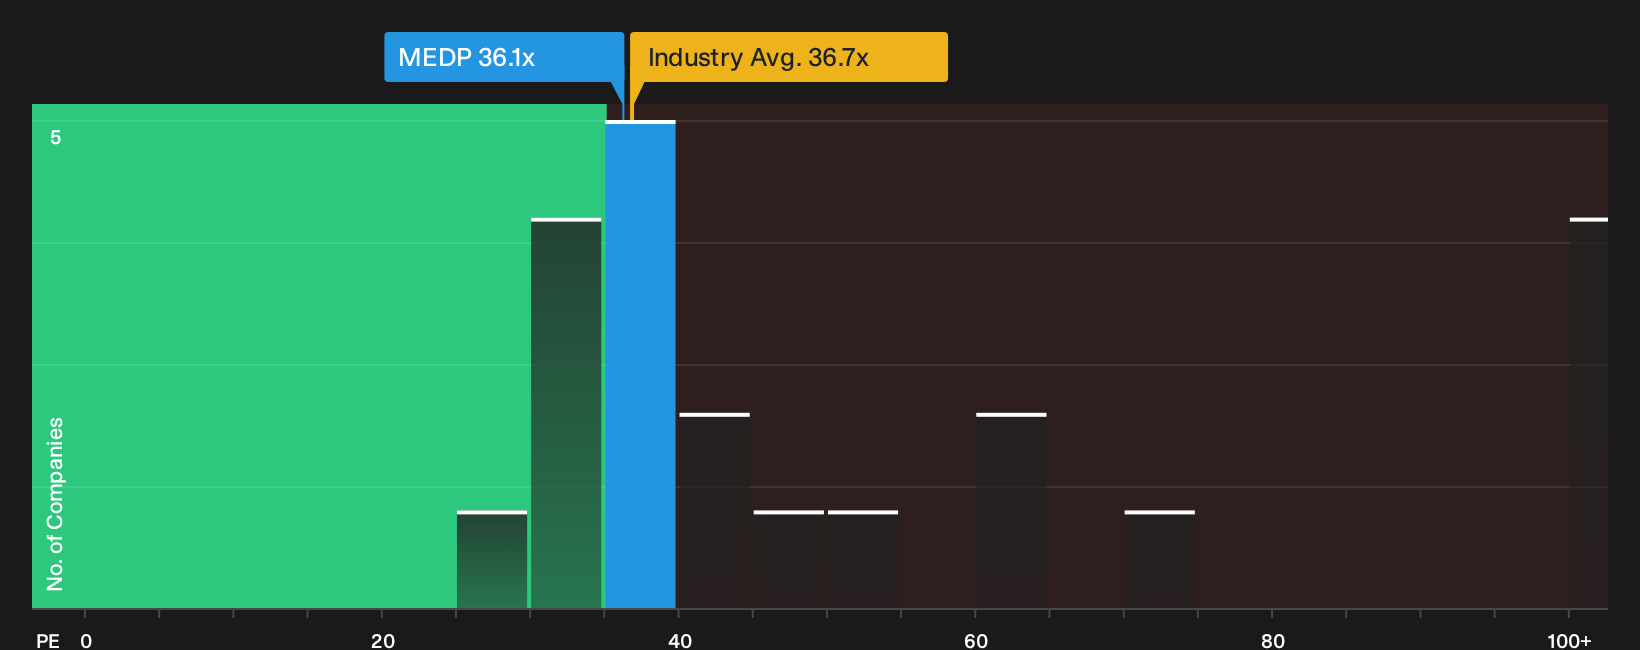
The DCF narrative flags Medpace Holdings as rich, yet the market’s own yardstick tells a more mixed story. At a 36.1x P/E, the stock trades below peer averages of 52.9x and close to the global Life Sciences sector on 36.7x, but well above a fair ratio of 22.4x that our models suggest the market could move toward. For investors, that blend of relative value and fair ratio premium raises a simple question: Is this a cushion against downside or a warning that expectations leave less room for error?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between Medpace Holdings’ quality and its pricing debate is normal, and the fastest way to cut through that is to test the numbers yourself. To see both the concerns and the upside investors are focused on, start with the 3 key rewards and 1 important warning sign.
Looking for more Medpace Holdings sized ideas?
If you stop with Medpace Holdings, you risk missing other setups with similar quality, pricing puzzles and risk profiles that might fit your portfolio even better.
- Target higher potential upside by reviewing a carefully filtered 29 high quality undervalued stocks that combines quality fundamentals with pricing that still looks restrained.
- Strengthen portfolio resilience by focusing on companies screened for robust finances through a list of solid balance sheet and fundamentals (24 results) that keeps weak balance sheets off your radar.
- Dial down risk by scanning a curated 30 resilient stocks with low risk scores built to spotlight businesses with more consistent profiles and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com