


Chevron (CVX) Climbed, What Is Driving Fresh Attention Now?
Chevron (CVX) has moved onto investors’ radar after a preliminary deal to pursue operatorship of Iraq’s West Qurna 2 field and a fresh push to expand drilling in Argentina’s Vaca Muerta shale.
Chevron’s recent news is landing on top of a sharp rerating in the shares, with a 1 month share price return of 14.07% and a 90 day gain of 22.74% helping push the stock to US$233.21. The year to date share price return of 49.59% and 5 year total shareholder return of 148.91% signal strong momentum that investors are now trying to reconcile with fresh projects and upcoming earnings catalysts.
Scan how Chevron’s move in Iraq and Argentina compares with other large energy producers by reviewing the hand picked 42 power grid technology and infrastructure stocks in the sector.
Bulls point to Chevron’s global projects and rising share price momentum. Bears worry the excitement now sits in the valuation. Which story do the numbers lean toward as you stress test this move?
Most Popular Narrative: 2% Overvalued
Chevron closed at $233.21 against a narrative fair value of $227.71, so the story investors follow has the shares modestly ahead of modeled worth while still hinging on execution in large projects.
Accelerating structural cost reductions, with US$3b of annual savings already delivered and Permian CapEx per barrel expected to be 25% lower in 2026 than in 2025, extend the earlier efficiency program and are described as setting Chevron up for higher net margins and stronger free cash flow conversion on future production. The integration of Hess, which is already reported as running ahead of the original synergy plan, together with ongoing portfolio high grading and disciplined CapEx at the lower end of guidance, supports the earlier view that acquisitions and optimization can be accretive for earnings per share and cash returns to shareholders.
See why 473 investors see Chevron as 2% overvalued.
Result: Fair Value of $227.71 (OVERVALUED)
Still, the Chevron narrative can be knocked off course if long term energy demand shifts faster than expected or if large projects like Venezuela and Tengiz encounter execution challenges.
Find out about the key risks to this Chevron narrative.
Another View: Cash Flows Paint Chevron As Undervalued
The first narrative has Chevron trading modestly above a $227.71 fair value. A different lens, the Simply Wall St DCF model, values the shares at $343.24, which is about 32.1% above the current $233.21 price. If cash generation wins out over headline multiples, which story earns more weight?
Our DCF model is fully transparent, so you can see every step and decide whether the cash flow assumptions line up with your own view of Chevron’s projects and risks. Look into how the SWS DCF model arrives at its fair value.
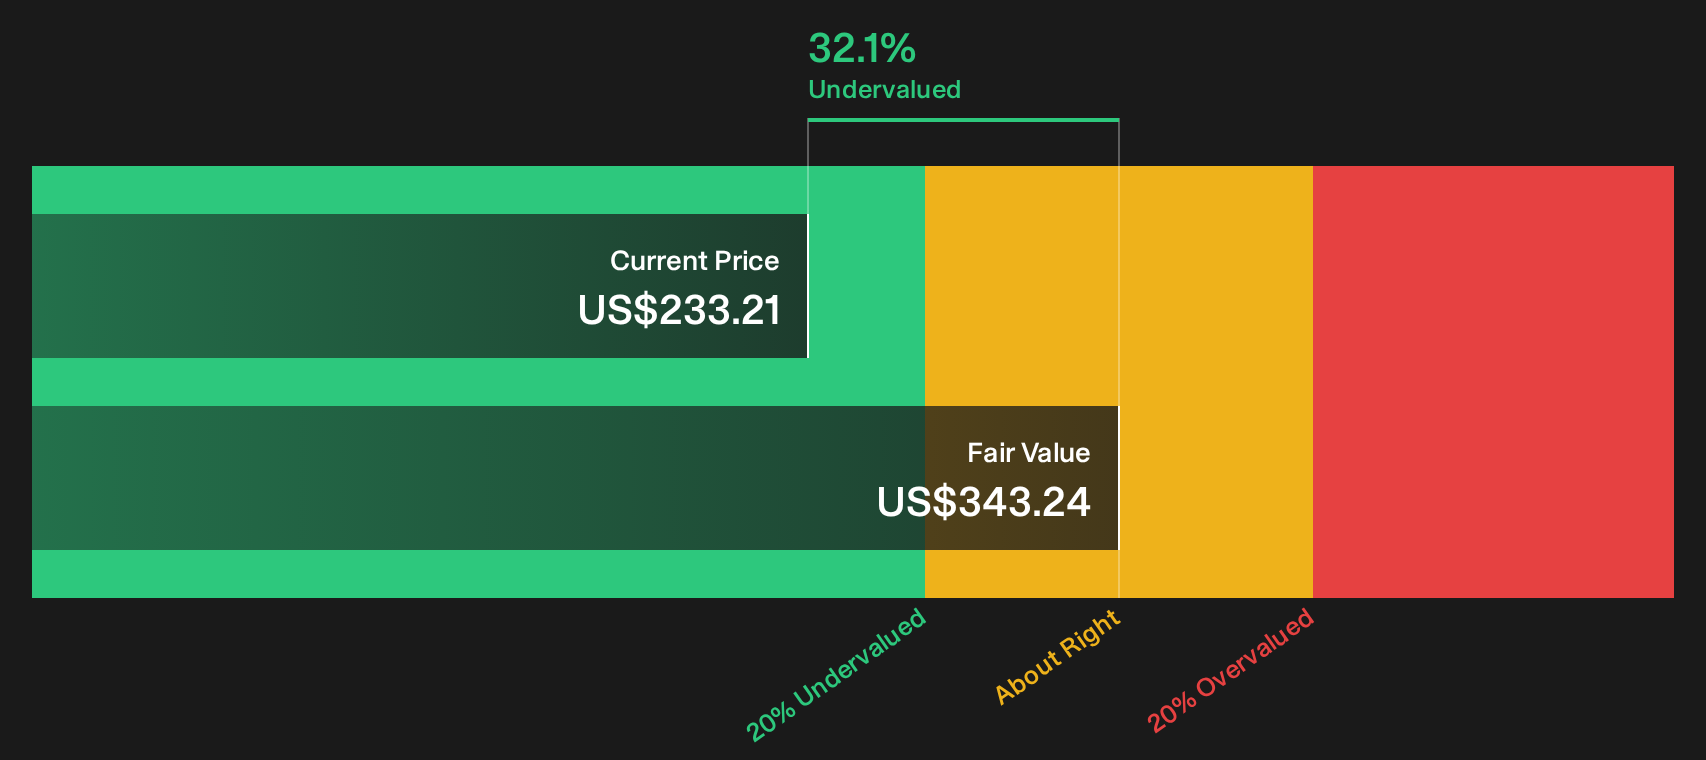
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Chevron for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Chevron is split, so take this as your prompt to move quickly, weigh the upside against the concerns, and dig into the underlying numbers yourself using the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Chevron?
If Chevron has you thinking harder about where the next opportunity might come from, do not stop here. Cast a wider net and pressure test your ideas.
- Hunt for potential mispriced opportunities by scanning the 29 high quality undervalued stocks that combine solid fundamentals with appealing entry points.
- Build a steadier income base by reviewing 5 dividend fortresses that focus on higher yielding payouts with supporting financial profiles.
- Dial back concentration risk by checking 30 resilient stocks with low risk scores that prioritize resilient balance sheets and more stable business profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com