


How Investors Are Reacting To Coupang (CPNG) Sartori Cheese Expansion
- Coupang’s expanded partnership with Wisconsin based Sartori Cheese, announced in October 2026, uses Rocket Fresh and its logistics network to move high value perishable U.S. dairy products efficiently to consumers across South Korea.
- The relationship highlights how Coupang’s infrastructure supports cross border commerce, with the platform helping generate more than US$5b of overseas sales of U.S. goods and services in 2025 for thousands of brands.
- We will now look at how Coupang’s role in scaling Sartori Cheese exports could influence the broader investment narrative around logistics.
Scan other logistics and cross border commerce plays that could see similar momentum to Coupang’s model by checking our curated list of 21 high quality undiscovered gems.
Coupang Investment Narrative Recap
To hold Coupang, you need to believe its heavy spend on logistics, technology, and new markets eventually turns into stronger margins without breaking the balance sheet. The Sartori Cheese news fits into that thesis. It showcases the same delivery backbone that supports Rocket Fresh, Eats, and Taiwan, but does not on its own change the near term earnings profile.
The bigger short term swing factor is whether Developing Offerings like Taiwan reduce their US$219m adjusted EBITDA loss on US$1.4b revenue. Elevated operating costs and regulatory hits in Korea sit on the other side of the ledger. If expenses stay sticky, Coupang’s path to cleaner profitability could remain drawn out.
The Sartori announcement is most relevant because it highlights Coupang’s cross border logistics as a potential earnings lever instead of just a cost center. Moving high value, time sensitive U.S. goods into Korea via Rocket Fresh illustrates how the same fixed infrastructure might support more categories and higher ticket baskets over time.
For potential catalysts, that context matters alongside management’s push into automation and AI, which some analysts currently associate with the possibility of better margins by mid 2027. The Zacks Rank #3 (Hold) framing keeps expectations aligned with the broader market. Execution on these partnerships and on Taiwan unit economics is what really needs watching from here.
Coupang Long Term Assumptions and Valuation Setup
Coupang's narrative projects US$48.0b revenue and US$1.3b earnings by 2029. This rests on analysts modeling 10.6% yearly revenue growth and an earnings swing of about US$2.1b from a current loss of US$767.0m.
Uncover why Coupang's fair value indicates a 69% potential upside to its current price, which could narrow quickly.
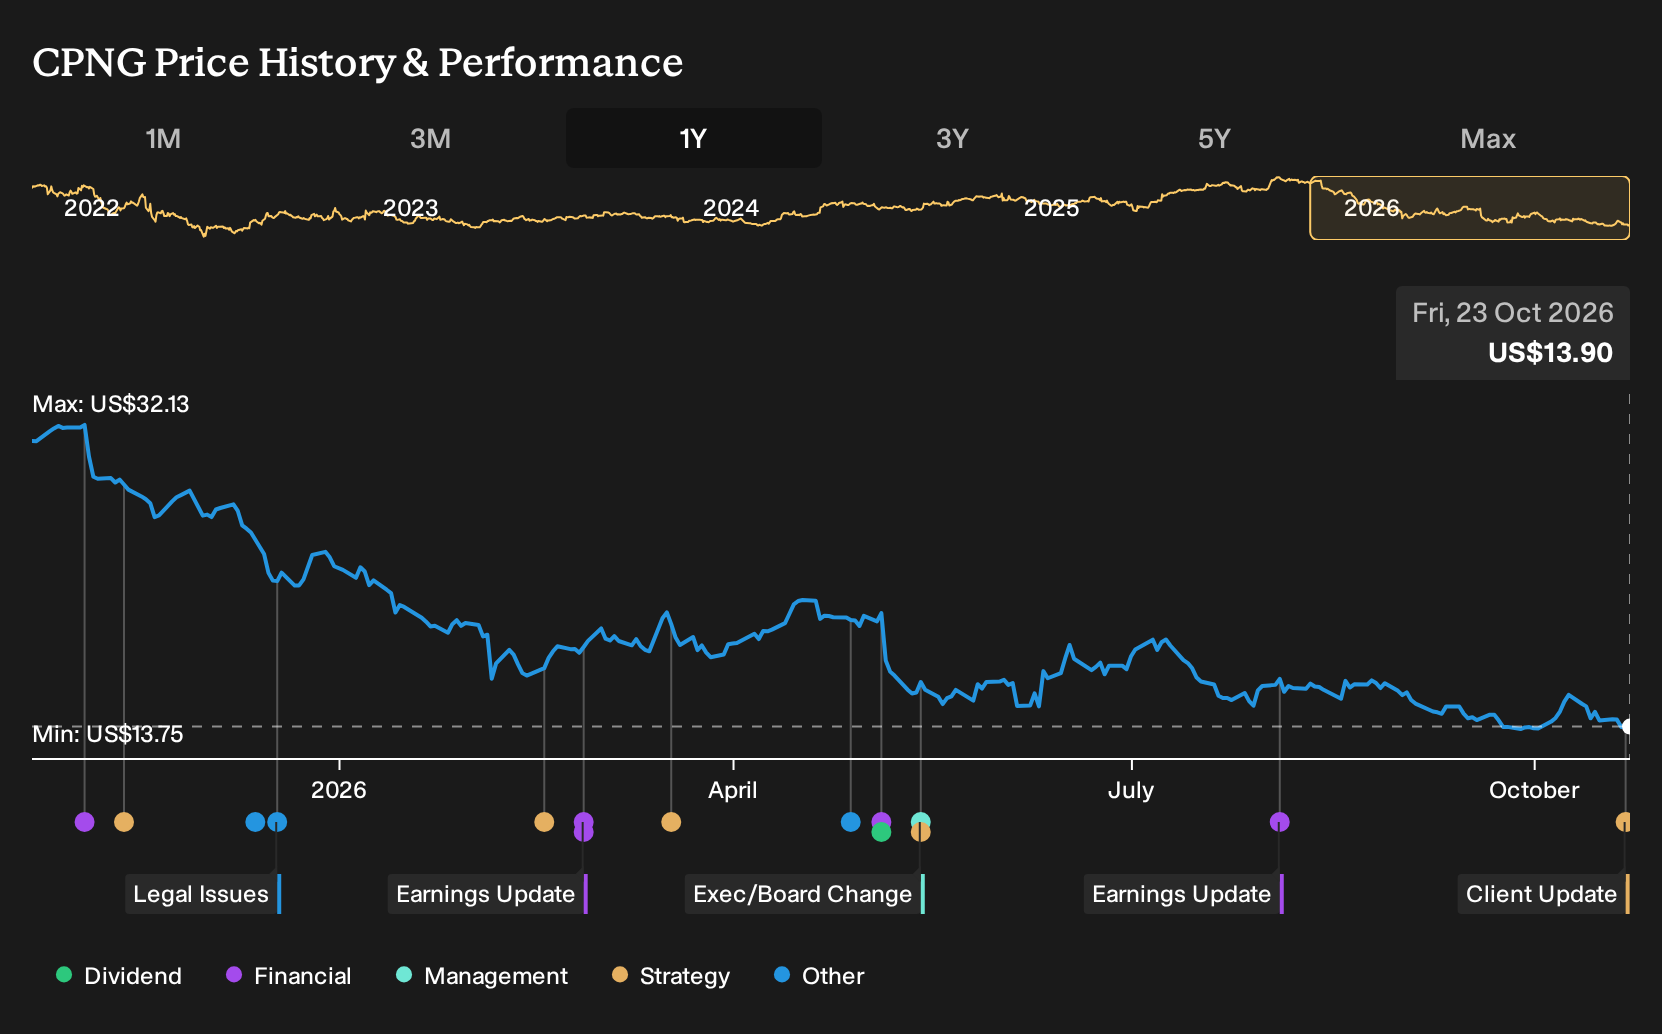
Exploring Other Perspectives
One alternate view treats regulatory and tax pressure as the real swing factor for Coupang. The most cautious analysts were penciling in about US$46.7b of 2029 revenue and US$975.8m of earnings before this Sartori news. That is a far more restrained story. Use it as a reference point and compare several narratives yourself.
Explore 5 other Coupang fair value estimates, including one that suggests it could be worth just $15.02.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Coupang research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Coupang. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coupang's overall financial health at a glance.
Looking For More Investment Ideas Beyond Coupang?
Coupang might be the headline story today, but your portfolio will usually benefit from having a wider bench of ideas. Use the Simply Wall St Screener to surface other businesses that fit the balance of quality, risk, and income that suits your own approach.
- If you want potential mispricing with quality in mind, scan our curated set of 27 high quality undervalued stocks that combine solid fundamentals with attractive valuations.
- For readers who care more about resilience than excitement, focus on companies in 30 resilient stocks with low risk scores and see which businesses score well on financial strength and risk metrics.
- If income is a priority, start with our universe of 5 dividend fortresses and shortlist the stocks that line up with your yield and payout preferences.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com