


Concor Shares Slid Even Though Profit Rose
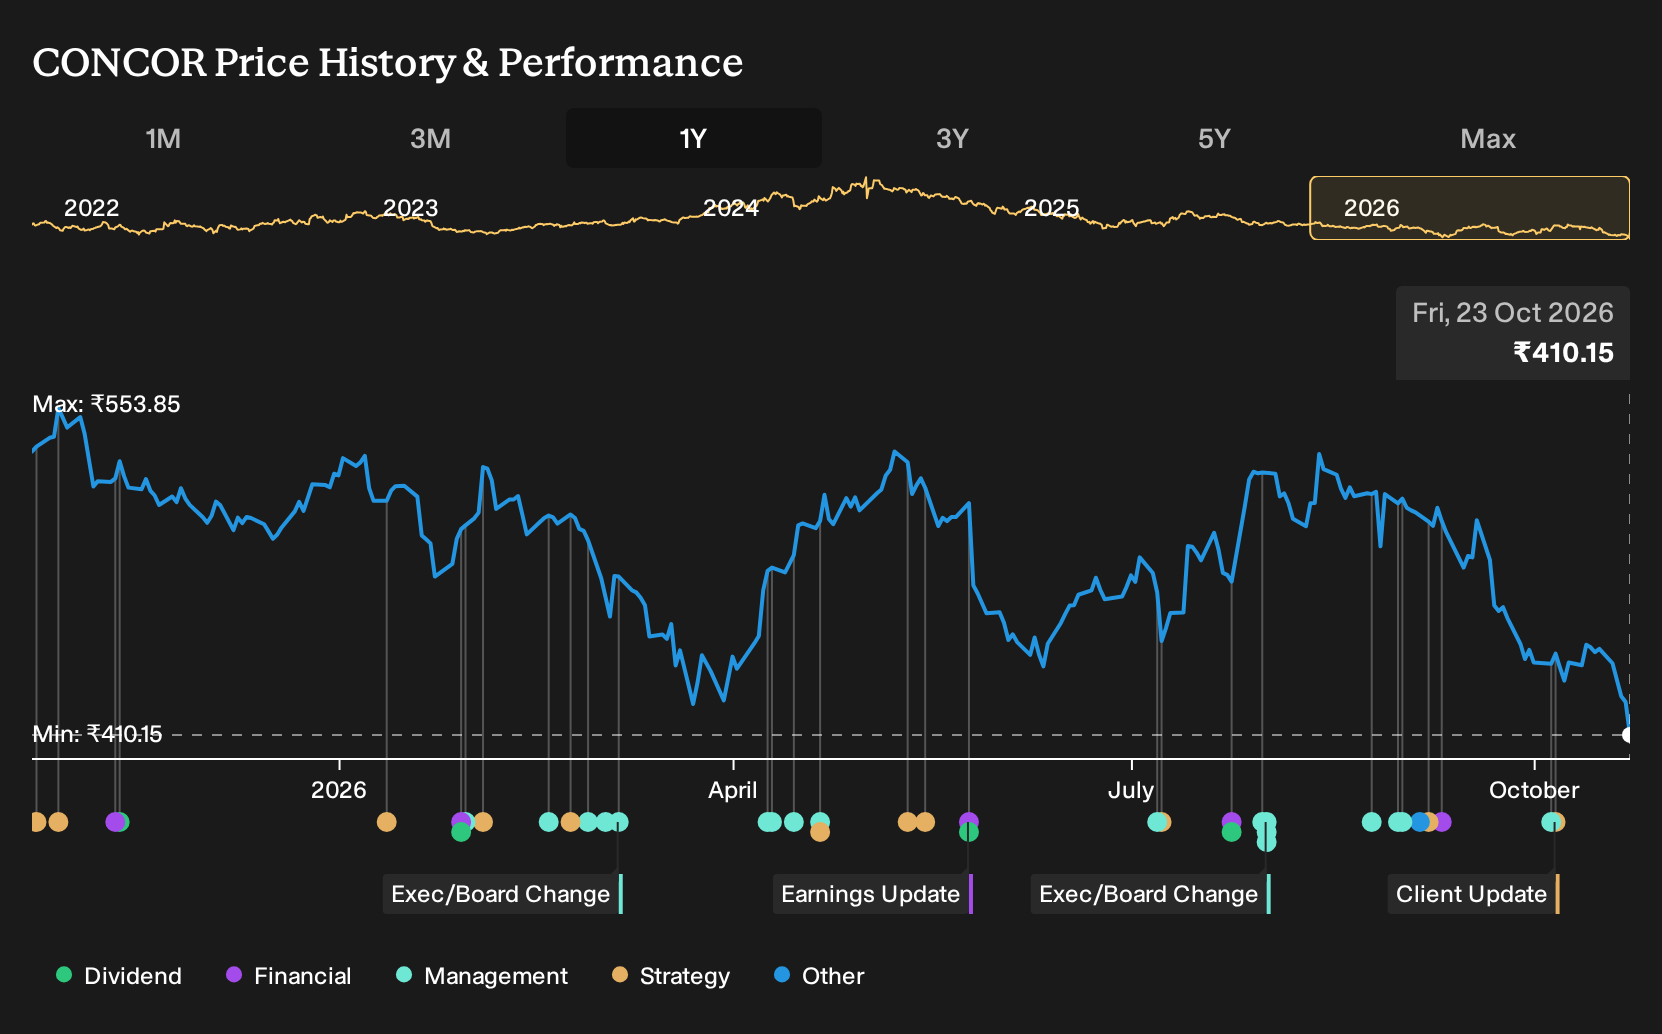
If you only glanced at Container Corporation of India’s recent headlines, the story might have sounded steady. For Container Corporation of India shareholders, the loss over the past year was 22.3%, including dividends. That outcome jars with quarterly numbers that showed revenue and net income both a touch higher by Q1 2027, even as net margin stayed flat. If you were weighing a position back in October 2025, what early clues could have hinted at this gap between business and return?
If the move has made Container Corporation of India harder to judge, start where the gap is still open and scan 192 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On Container Corporation of India
The shares cost ₹535 at the start of the period, and you were effectively choosing between two competing stories about where Container Corporation of India could head next.
The bullish narrative saw a Fair Value of ₹583, a price implied by assumptions such as revenue growth of 12.4% a year and profit margins reaching 15.2%, helped by the Western Dedicated Freight Corridor and logistics park build out.
The bearish view pointed to a Fair Value of ₹472, based on worries that better highways and Make in India production patterns would pull freight to roads and cap rail container volumes.
What The Results Changed For Container Corporation of India
The clearest new fact was Q1 2027 earnings. Container Corporation of India reported revenue of ₹21,597.6m and net income of ₹2,667.4m, only slightly above Q1 2026, while net margin held at 12.4%. That modest shift gave more weight to the cautious case that expected less punchy improvement in profitability.
The hinge assumption was margin expansion. When you test any logistics stock, track whether net margin actually moves toward the thesis, rather than looking only at whether sales and profit are a bit higher.
What You Would Be Paying For In Container Corporation of India Today
With Container Corporation of India now at ₹410, the selected Narrative’s Fair Value sits above the current price and rests on a rail-centric, efficiency-focused argument rather than on a quick sentiment rebound after a share price fall of 22.3% over the past year.
The core question for a buyer today is whether Dedicated Freight Corridor execution, higher JNPT rail share and scaled value-added logistics can arrive without undermining margin discipline, so the recent decline represents underappreciated rail share and efficiency, not an early warning on execution risk.
"Key Takeaways For Container Corporation of India: analysts expect rail-focused capex, DFC-linked volumes, and value-added logistics services to support higher throughput and margins over time. The main requirement is successful execution on DFC connectivity, higher rail share at JNPT, and scaling of first and last mile and bulk cement tank-container services without eroding margin discipline."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Where Container Corporation’s Question Echoes
Container Corporation of India raises one puzzle. Who gains when logistics grow more automated and asset-light?
Look one step away. Another transport platform is wrestling with the shift if autonomous vehicles become everyday reality.
It connects riders, couriers and freight, and takes a slice for coordinating activity. As human drivers matter less, the real contest becomes who owns demand and routing.
That business is investing heavily in autonomous partnerships and fleet access. The unresolved issue is whether its marketplace keeps enough economics once the driver disappears.
That argument has a Narrative and a number behind it. → See the company one Narrative values 74% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com