


There's A Lot To Like About Natoco's (TSE:4627) Upcoming JP¥27.00 Dividend
Readers hoping to buy Natoco Co., Ltd. (TSE:4627) for its dividend will need to make their move shortly, as the stock is about to trade ex-dividend. Typically, the ex-dividend date is two business days before the record date, which is the date on which a company determines the shareholders eligible to receive a dividend. It is important to be aware of the ex-dividend date because any trade on the stock needs to have been settled on or before the record date. Accordingly, Natoco investors that purchase the stock on or after the 29th of October will not receive the dividend, which will be paid on the 28th of January.
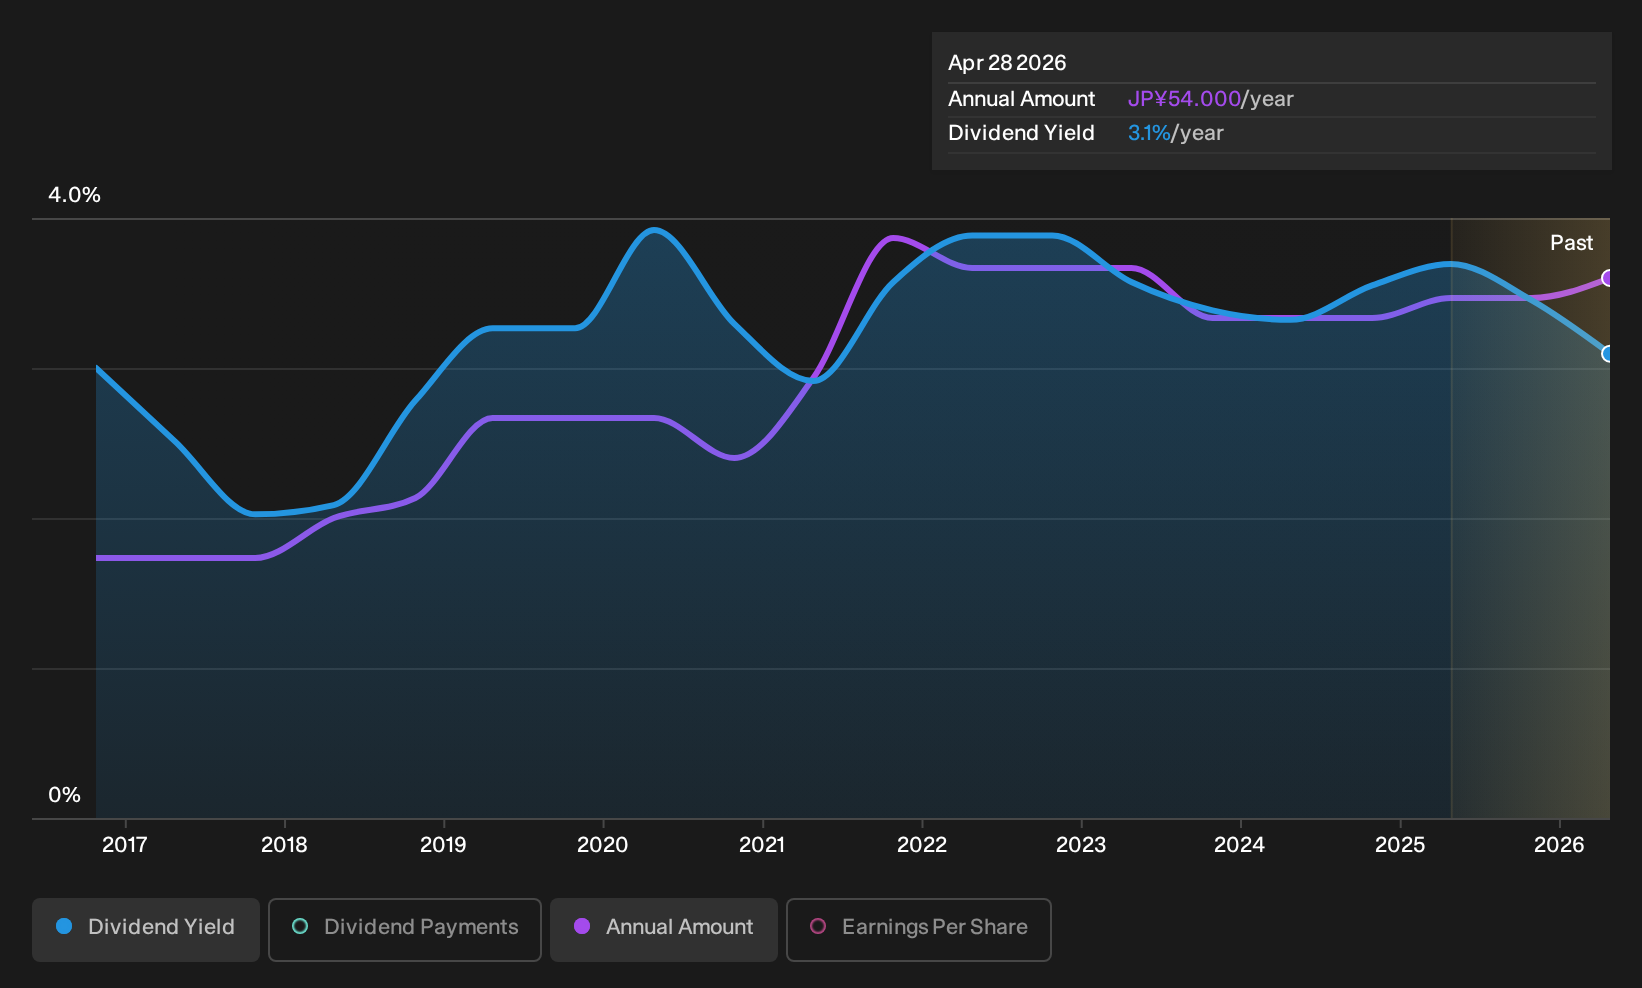
The company's next dividend payment will be JP¥27.00 per share. Last year, in total, the company distributed JP¥54.00 to shareholders. Calculating the last year's worth of payments shows that Natoco has a trailing yield of 2.7% on the current share price of JP¥1995.00. If you buy this business for its dividend, you should have an idea of whether Natoco's dividend is reliable and sustainable. So we need to check whether the dividend payments are covered, and if earnings are growing.
Dividends are usually paid out of company profits, so if a company pays out more than it earned then its dividend is usually at greater risk of being cut. That's why it's good to see Natoco paying out a modest 27% of its earnings. Yet cash flow is typically more important than profit for assessing dividend sustainability, so we should always check if the company generated enough cash to afford its dividend. Luckily it paid out just 14% of its free cash flow last year.
It's encouraging to see that the dividend is covered by both profit and cash flow. This generally suggests the dividend is sustainable, as long as earnings don't drop precipitously.
View our latest analysis for Natoco
Click here to see how much of its profit Natoco paid out over the last 12 months.
Have Earnings And Dividends Been Growing?
Businesses with strong growth prospects usually make the best dividend payers, because it's easier to grow dividends when earnings per share are improving. If earnings fall far enough, the company could be forced to cut its dividend. This is why it's a relief to see Natoco earnings per share are up 9.0% per annum over the last five years. The company is retaining more than half of its earnings within the business, and it has been growing earnings at a decent rate. Organisations that reinvest heavily in themselves typically get stronger over time, which can bring attractive benefits such as stronger earnings and dividends.
The main way most investors will assess a company's dividend prospects is by checking the historical rate of dividend growth. Natoco has delivered 6.8% dividend growth per year on average over the past 10 years. It's encouraging to see the company lifting dividends while earnings are growing, suggesting at least some corporate interest in rewarding shareholders.
The Bottom Line
Has Natoco got what it takes to maintain its dividend payments? Earnings per share have been growing moderately, and Natoco is paying out less than half its earnings and cash flow as dividends, which is an attractive combination as it suggests the company is investing in growth. It might be nice to see earnings growing faster, but Natoco is being conservative with its dividend payouts and could still perform reasonably over the long run. It's a promising combination that should mark this company worthy of closer attention.
While it's tempting to invest in Natoco for the dividends alone, you should always be mindful of the risks involved. For example, we've found 3 warning signs for Natoco (1 shouldn't be ignored!) that deserve your attention before investing in the shares.
If you're in the market for strong dividend payers, we recommend checking our selection of top dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.